Summary
Yes, buying off-plan in São Paulo is riskier now. Developers launched 154,769 homes in the 12 months to August 2026 but sold 121,064, and unsold new stock jumped 50.7% in a year to 98,018 units.
Demand hasn't collapsed: sales are up about 10% in a year. The risk is local. Your unit will compete with similar ones finishing near the same metro station at the same time.
Studios are the weak spot. Unsold mid- and high-end units of up to 30 m² rose 71% in the year to June 2026, to about 10,900, or 12 months of sales.
The INCC construction index rose 6.66% in the year to September 2026, against 3.64% for São Paulo asking prices. On R$500,000 over three years, that gap can eat about R$50,000 of your launch discount.
So a launch price is not automatically a bargain. Compare your all-in cost at delivery with finished apartments nearby, which is where sellers are cutting prices.
Credit is still expensive: the Selic is 13.75% and private banks charge about 11.8% plus TR. Most foreign non-residents can't get a Brazilian mortgage at all, so plan to pay in cash.
Walking away costs money: under Lei 13.786/2018 the developer can keep up to 25% of what you paid, or up to 50% when the project has patrimônio de afetação.
Patrimônio de afetação protects you if the developer goes bust, but not against overpaying, delays or a weak resale market.
Developers are not in a general crisis, but cancellations are real: EZTEC had a record first half of 2026 while cancellations reached about 14.4% of its second-quarter gross sales.
The mid- and high-end market is softer: its unsold stock now takes about 13 months to sell, against 7 in 2024. That gives buyers room to negotiate 10% to 15% off slow launches.
The Airbnb exit is narrower too: São Paulo has 34,925 active listings (up 66%), occupancy is around 40%, and since May 2026 a building can require two-thirds of owners to approve short stays.
Our view: off-plan still works with a solid developer, a registered patrimônio de afetação, cash in hand, a real discount to finished units and little similar supply nearby. Generic investor studios bought on a brochure promise are the deals to skip.


What changed for São Paulo off-plan buyers in 2026?
Supply. Developers are launching much faster than buyers are absorbing, and the unsold stock is piling up.
Secovi-SP counted 154,769 new homes launched in the city in the 12 months to August 2026, up 25%, against 121,064 sold, up about 10%. That's about 33,700 more homes launched than sold, and unsold new stock reached 98,018 units in August, up 50.7% in a year.
Demand is still big. Developers sold 10,813 new homes in August 2026 alone, 36.9% more than in August 2025. But the value of 12-month sales fell about 4%: buyers are moving to cheaper homes, mostly Minha Casa, Minha Vida (MCMV) units, which made up 71% of August sales.
What it means for you: there's less room for a mediocre unit, an optimistic financing plan or a price that only looks cheap in the sales office.
| São Paulo new-build market | Latest reading | Comparison | What it tells us |
|---|---|---|---|
| New-home sales, 12 months to Aug. 2026 | 121,064 units | +10.2% year-on-year | Demand remains very large |
| Launches, 12 months to Aug. 2026 | 154,769 units | +25% year-on-year | Supply is growing much faster |
| Unsold new stock, Aug. 2026 | 98,018 units | +50.7% year-on-year | More competition for every new project |
| New-home sales in August 2026 | 10,813 units | +36.9% on Aug. 2025 | No collapse in buyer demand, but 71% were MCMV units |
Is São Paulo actually becoming oversupplied with new apartments?
Not citywide, but in some products and some streets, yes.
Buyers are still absorbing more than 120,000 new homes a year, and MCMV stock (about 59,100 units, 60% of the total) still sells in about eight months at the current pace. The slow part is the rest: mid- and high-end stock now needs about 13 months to sell, against 7 months in 2024.
The danger is local. You compete inside a small radius: one metro station, one neighborhood, one apartment type. Ten thousand sales a month citywide don't help if four towers full of similar studios finish near the same station.
What to do: before signing, map the projects under construction and launched within 1 km, with their delivery dates. That tells you more than any citywide figure.
Are small off-plan apartments in São Paulo becoming especially risky?
Yes, especially studios under 30 m². They still sell, but they are piling up faster than anything else.
In the mid- and high-end segment, unsold units of up to 30 m² rose 71% in the year to June 2026, to about 10,900, or 12 months of sales (Secovi-SP data reported in September 2026; subsidized units aren't in this count). The 30 to 45 m² band still dominates the market: in July 2026 it was 61% of launches and 67% of sales.
The problem comes later. Many compact apartments are bought by investors, not families. When several nearby buildings finish, owners end up advertising almost the same unit to the same tenants and buyers.
A 35 m² apartment next to Avenida Paulista, Faria Lima or a busy metro interchange handles that competition much better than a generic 25 m² unit where developers still have plenty of land to build.
The table below is from Secovi-SP's January 2026 survey: small units sold fastest at launch. That says nothing about how easy they will be to rent or resell once finished.
| São Paulo unit size | Share of launches (Secovi-SP, Jan. 2026) | Share of sales | Monthly VSO (share of stock sold) |
|---|---|---|---|
| Under 30 m² | 21% | 23% | 7.8% |
| 30–45 m² | 70% | 68% | 11.6% |
| 45–65 m² | 8% | 6% | 7.3% |
| 66–85 m² | 1% | 1% | 3.0% |
| 86 m² and above | Very small | About 2% | Roughly 1.7–2.2% |
Can INCC wipe out the discount on a São Paulo off-plan apartment?
Yes. INCC indexation can eat a big part of the launch discount before you get the keys.
FGV's INCC construction cost index rose 6.66% in the 12 months to September 2026. São Paulo asking prices rose 3.64% over the same period (FipeZAP). Off-plan contracts usually index the balance you still owe to the INCC until delivery, so the R$500,000 or R$700,000 on the brochure is not your final cost.
The two indexes measure different things. But if your balance climbs at about 6.7% a year while similar finished apartments rise about 3.6%, part of your discount disappears automatically.
Say R$500,000 (about $99,000) stays fully indexed at 6.66% a year for three years: it becomes about R$607,000. The same R$500,000 growing at 3.64% a year becomes about R$557,000. That's a gap of about R$50,000 (about $9,900). It's an illustration, not a forecast, but it shows why the index clause matters.
| Illustrative three-year example | Starting amount | Annual rate used | Amount after three years |
|---|---|---|---|
| Balance indexed to INCC | R$500,000 | 6.66% | About R$607,000 |
| Property value (asking-price trend) | R$500,000 | 3.64% | About R$557,000 |
| Gap | — | — | About R$50,000 |
| What the example shows | — | — | Indexation can absorb much of an apparent discount |
What to do: ask for the payment schedule with the INCC clause in writing, pay more upfront if the developer gives a real discount for it, and check whether indexation switches to IPCA plus interest after delivery.
Is buying a São Paulo apartment at launch still automatically cheaper?
No. It can be cheaper, but you have to prove the discount.
A developer launches at R$700,000 (about $139,000), raises the list price during construction and later advertises the same floor plan at R$850,000 (about $168,000). The first buyer seems to have made R$150,000. In reality, much less.
That buyer paid INCC adjustments. Later buyers often get incentives that never show in the list price: better payment plans, covered fees, upgrades. And at delivery, the first buyer competes with finished apartments in the buildings next door.
Compare your expected all-in cost at delivery with what finished apartments nearby actually sell for. FipeZAP's 2026 buyer survey found an average 9% discount on asking prices, and 14% when buyers negotiated one, so start from that, not from the developer's future brochure price.
Are developers giving hidden discounts on unsold launches right now?
Yes, and with stock at a record, this is where buyers have the upper hand in 2026.
With 98,018 unsold new homes in the city and mid- and high-end stock taking about 13 months to sell, developers rarely cut the list price openly. They prefer better payment plans, covered ITBI or registration fees, furniture, and bigger bonuses for brokers.
What to do: ask the sales team which finished or nearly finished units are still in stock, since those are where developers are most flexible. On a launch that has been selling slowly for months, aim for 10% to 15% off: FipeZAP found that buyers who negotiate get 14% off on average. Get every incentive written into the contract, not promised by the broker.
Are mortgage rates making São Paulo off-plan purchases more dangerous?
Yes, for anyone who needs a bank loan at handover. The building can turn out fine and the deal can still go wrong.
In September 2026, Banco Central data show regulated TR-linked housing loans at 7.98% a year at Caixa and about 11.8% to 11.9% at Bradesco, Santander and Itaú, plus TR. The Selic was cut from 14% to 13.75% on September 16, 2026, and the next Copom meeting is on November 3-4. The Focus survey expects 13.25% by the end of 2026.
An off-plan buyer usually takes the main loan two or three years after signing. Rates may be lower by then, but nobody knows what the bank will offer at handover. On a loan of several hundred thousand reais, a few points change the monthly payment a lot.
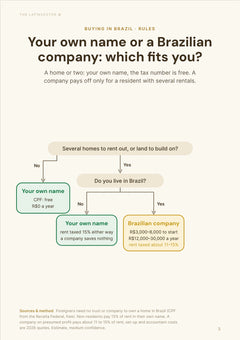
For a foreigner, the question is often simpler: Brazilian banks generally ask for residency or nationality, so most non-residents pay cash. If you don't have residency, don't sign a plan that depends on a mortgage at delivery.
| Bank / financing reference | Annual rate (Sept. 2026) | Position in current range | Off-plan implication |
|---|---|---|---|
| Caixa, regulated TR | 7.98% + TR | Lowest among major lenders | Depends on your profile and credit line |
| Bradesco | 11.77% + TR | High | Financing assumptions need a large buffer |
| Santander | 11.85% + TR | High | Same problem |
| Itaú | 11.87% + TR | High | Same problem |
| Selic | 13.75% | Still very restrictive | Credit conditions remain difficult |
What happens if the bank lends less than a São Paulo off-plan buyer expected?
You pay the difference, in cash, at handover.
Say you count on the bank financing R$600,000 (about $119,000) at delivery. Between signing and the keys, your income can fall, you can take on other debt, bank rules can change, or the finished apartment can be valued lower than expected. Any of these can shrink the loan.
The developer won't cover the gap. Banks lend against the finished apartment and your finances, not the developer's story about what the unit will be worth.
What to do: make sure you could still close if the loan came in 20% or 30% below plan, and ask the developer in writing what happens if you can't (extra time, a direct installment plan, or a penalty).
Can a buyer easily cancel an off-plan apartment in São Paulo?
No. Leaving an off-plan contract is expensive.
Under the distrato law (Lei 13.786/2018), if you cancel, the developer can keep up to 25% of what you paid, or up to 50% when the project has patrimônio de afetação, plus the broker's commission. The same law lets the developer deliver up to 180 days late without penalty if the contract says so.
Courts, contract terms and the reason for cancelling all matter, so you won't automatically lose half your money. But money paid during construction is not savings you can take back when plans change.
It's also why cancellations rise when credit is tight: ABRAINC counted 41.4% more cancellations nationally in Q1 2026 than a year earlier, and they were 17.8% of sales in the mid- and high-end segment.
Does patrimônio de afetação really protect São Paulo off-plan buyers?
Yes, against the developer's other debts and a bankruptcy. Not against much else.
Under Lei 10.931/2004, the land and assets of a project can be legally ring-fenced from the developer's general estate. If the developer gets into serious trouble, those assets are shielded from unrelated creditors, and buyers can organize to finish the project or decide what to do with it.
It has limits. A ring-fenced project can still be late, badly built or stuck in hard decisions if the developer fails. And it does nothing if you paid too much or can't afford the mortgage.
What to do: check that the afetação is registered on the project's matrícula at the property registry. A salesperson's word is not enough.
| Buyer risk | Does patrimônio de afetação help? | Remaining exposure | What to check |
|---|---|---|---|
| Developer bankruptcy | Substantially | Completion may still become complicated | Registered project structure |
| Developer's unrelated debts | Yes | Project-specific liabilities remain | Incorporation documents |
| Construction delay | Limited protection | Buyer still suffers the delay | Delivery clauses |
| Bad resale price | No | Buyer takes the market loss | Comparable finished units |
| Expensive mortgage | No | Buyer takes the financing risk | Cash buffer |
| Voluntary cancellation | No automatic escape | Buyer can lose up to 50% of what was paid | Distrato provisions |
Are São Paulo developers themselves getting into trouble?
Some are under more pressure than others, but there's no broad developer crisis.
Cyrela reported about R$3.8 billion of launches and R$2.6 billion of contracted sales in the second quarter of 2026, and about R$4.7 billion of sales in the first half. EZTEC had a record first half for sales, about R$1.44 billion gross and R$1.28 billion net, yet second-quarter cancellations reached about R$97 million, 14.4% of gross sales. Even looked weaker: its second-quarter net sales fell to about R$156 million, around 65% below a year earlier.
These companies target different buyers and launch at different times, so don't compare them too closely. But the gap is wide enough that the developer you pick is part of the risk.
What to check: cash and debt in the latest quarterly report, how fast its projects sell, its cancellation rate, and its record of delivering on time. Listed developers publish all of this on their investor-relations sites.
Could today's São Paulo construction boom hurt buyers only after delivery?
Yes. A lot of today's risk will only show up when apartments are finished and investors start competing with each other.
About 600 new residential condos are due for delivery in São Paulo in 2026, 13% more than in 2025, and almost 60% of them have small units (Lello). With 154,769 launches in the last 12 months, more waves are coming.
Once delivered, your unit no longer competes with the developer's other units only. It competes with every owner trying to rent or resell a similar apartment nearby, including buyers from projects launched in the same boom. That's sharpest along transit corridors, where the city's master plan encourages dense building.
A project that sells fast today can still hand over into a crowded rental market three years later. Fast off-plan sales and easy renting after delivery are not the same thing.
Can you still count on Airbnb for an off-plan studio in São Paulo?
Not safely. The short-stay exit that sold many studios has narrowed in 2026.
AirROI counted 34,925 active São Paulo listings in the 12 months to September 2026, up 66%, with occupancy around 40%. A one-bedroom grossed about R$32,800 (about $6,500) a year on average, before the 16% host fee, cleaning, condo fees and the 15% tax withheld from non-residents' rental income.
The rules are tighter too. In May 2026, the STJ ruled that offering units on platforms like Airbnb in a residential building can require the approval of two-thirds of the owners, and in September 2026 it picked a case (Tema 1.443) to set a binding rule, with similar cases on hold until then. Units built as social housing (HIS and HMP), common among new studios, can't legally be used for short stays at all.
What to do: check the unit isn't classed HIS or HMP, get the future building rules (convenção) on short stays in writing, and run your numbers on a long-term lease. If the deal only works on Airbnb, skip it.
Is São Paulo's strong housing demand enough to make off-plan buying safe?
No. Demand gives the market a strong base, but it won't rescue an overpriced or badly placed unit.
Secovi-SP counted 121,064 new homes sold in the city in the 12 months to August 2026. Nationally, ABRAINC-Fipe showed new-home sales up 11.4% in January to April 2026.
The split is what matters. MCMV unit sales rose 17.1%, while real sales in the middle- and high-income segment fell 10.3%, even as launches there rose 14.6%. In São Paulo, MCMV units were 71% of new-home sales in August 2026.
Much of the demand is in cheap subsidized housing with its own financing. If you're paying R$1.5 million (about $297,000) for an investor apartment, those sales numbers don't justify your price.
| Current market evidence | Recent result | What we learn |
|---|---|---|
| São Paulo new-home sales, 12 months to Aug. 2026 | 121,064 units | Citywide demand remains huge |
| Brazil new-home sales, Jan.–Apr. 2026 | +11.4% | Demand held up despite expensive credit |
| MCMV unit sales, Jan.–Apr. 2026 | +17.1% | Lower-ticket housing is driving much of the growth |
| Middle/high-income real sales, Jan.–Apr. 2026 | -10.3% | More expensive housing is weaker |
| Middle/high-income launches, Jan.–Apr. 2026 | +14.6% | Developers are still adding supply there |
Are expensive off-plan apartments in São Paulo more vulnerable right now?
Yes. The middle and upper end sells much more slowly than the headline numbers suggest.
In Secovi-SP's January 2026 survey, economic housing sold 12.1% of its stock in the month, against 5.4% for the rest of the market. Higher up it got slower: about 3% for R$700,000 to R$1.4 million units, about 2.2% for R$2.1 million to R$5 million, and about 1.6% above R$5 million.
New luxury has slowed further since. Brain counted high-end and luxury new-home sales down 39% in the first half of 2026, and launches down 53%.
Exceptional locations still sell for their own reasons. The awkward zone is the middle: too expensive for MCMV, too ordinary to be scarce. That's where we'd refuse to pay an off-plan premium today.

Does buying near the metro still protect a São Paulo off-plan investment?
Usually, yes, but a station surrounded by new towers can create its own oversupply.
Compact apartments depend on location: people accept less space in exchange for convenience. Research by Idea BR for REV3 on São Paulo MCMV projects launched between 2023 and 2025 found they sold better near the metro.
But "near the metro" is now on every brochure. The city's master plan pushes dense building along transit corridors (the Eixos de Estruturação da Transformação Urbana), so the same station that makes your project attractive can draw five, ten or twenty others.
What to do: map projects under construction and launched within a 10- to 15-minute walk. If hundreds of similar apartments arrive around your delivery date, the metro alone won't make your unit scarce.
What would make a São Paulo off-plan apartment too risky for us today?
When the deal needs several optimistic assumptions to work at the same time.
First, an apartment whose indexed cost at delivery already sits close to the price of similar finished units nearby. You take construction, timing and financing risk, so you should be paid for it.
Second, heavy leverage: a deal that only works with a big future loan at a good rate has no cushion.
Third, a wall of near-identical units nearby, especially tiny investor studios.
Fourth, weak developer finances, unclear incorporation documents, or no registered patrimônio de afetação. Also check when the condo fee starts: the STJ ruled in October 2025 that a buyer registered on the matrícula owes it even before getting the keys.
Last, a pitch built on future appreciation. With São Paulo asking prices up 3.64% in a year, about 0.9% less than inflation, a deal that needs 10% a year to look good needs too much to go right.
So is buying off-plan in São Paulo riskier now?
Yes, moderately. Credit is expensive, INCC indexation can raise your final cost, and a record pipeline of 98,018 unsold new homes means more competition after delivery in some neighborhoods.
We don't see a citywide new-build crisis. Sales are still above 120,000 homes a year, and big developers are still selling.
The risk has moved to the individual deal. Off-plan still makes sense when the developer is solid, the afetação is registered, you can pay without counting on a mortgage, the indexed cost is clearly below similar finished units, and there's no wall of similar supply coming.
We'd be much tougher on generic investor units: a tiny apartment bought because it's "near the metro", with a brochure yield and a promise that prices will rise before completion. Buying early, on its own, no longer makes a São Paulo deal clever.
Our methodology
This article estimates whether buying off-plan in São Paulo has become riskier, by looking at what decides the outcome: new supply against sales, unit size and price band, construction-cost indexation, mortgage rates, cancellation rules, project protections, developer results, the short-stay exit and competition after delivery.
New-home launches, sales and unsold stock come from Secovi-SP's monthly survey (August 2026, published in October), with the unit-size and price-band breakdowns from its January and July 2026 surveys. Building costs come from FGV's INCC, asking prices from FipeZAP (September 2026), discounts from FipeZAP's buyer survey, mortgage rates and the Selic from the Banco Central do Brasil, and the national split between MCMV and mid- to high-end housing from ABRAINC-Fipe. Developer figures come from company quarterly reports for the second quarter of 2026, condo deliveries from Lello, luxury data from Brain, and short-term rental figures from AirROI only.
Rules come from official texts: Lei 13.786/2018 on cancellations, Lei 10.931/2004 and Lei 4.591/1964 on project ring-fencing and incorporations, the STJ for short-term rentals and condo fees before delivery, and the city's master plan for transit corridors.
We checked these figures in October 2026. Conversions use about 5.05 reais per US dollar and 5.65 reais per euro.
Limits: asking prices are not sale prices; Secovi-SP covers new homes only; launches minus sales is not a count of unwanted apartments; the INCC and price indexes measure different things; and the three-year INCC example is an illustration, not a forecast.
Key sources used for this analysis include Secovi-SP's monthly market survey, Secovi-SP's August 2026 survey, Secovi-SP August 2026 data via Portas, Secovi-SP's January 2026 report, Portas on studio stock, Portas on compact launches, Secovi-SP June 2026 data via Banco Safra, INCC (FGV) via Partnr, FipeZAP sale index (September 2026), FipeZAP discount survey via Portas, Banco Central do Brasil mortgage rates, Banco Central do Brasil (Selic, September 2026), Focus survey of 19 October 2026 via InfoMoney, ABRAINC-Fipe indicators (May 2026), ABRAINC-Fipe release, Cyrela Investor Relations, Suno on EZTEC's second quarter 2026, Brain via Mercado&Consumo, Portas on 2026 condo deliveries, AirROI São Paulo, STJ decision of May 2026, STJ on Tema 1.443, STJ on condo fees before delivery, Exame on HIS and HMP units, Lei 13.786/2018 on distrato, Lei 10.931/2004 on patrimônio de afetação, Lei 4.591/1964 on incorporations and São Paulo City Hall on the transit corridors.