Summary
Yes, if the flat can earn about 6% to 7% gross or more. A Buenos Aires City average of 5.70% gross (Zonaprop, September 2026) is fine but thin once you pay to buy, run and tax it.
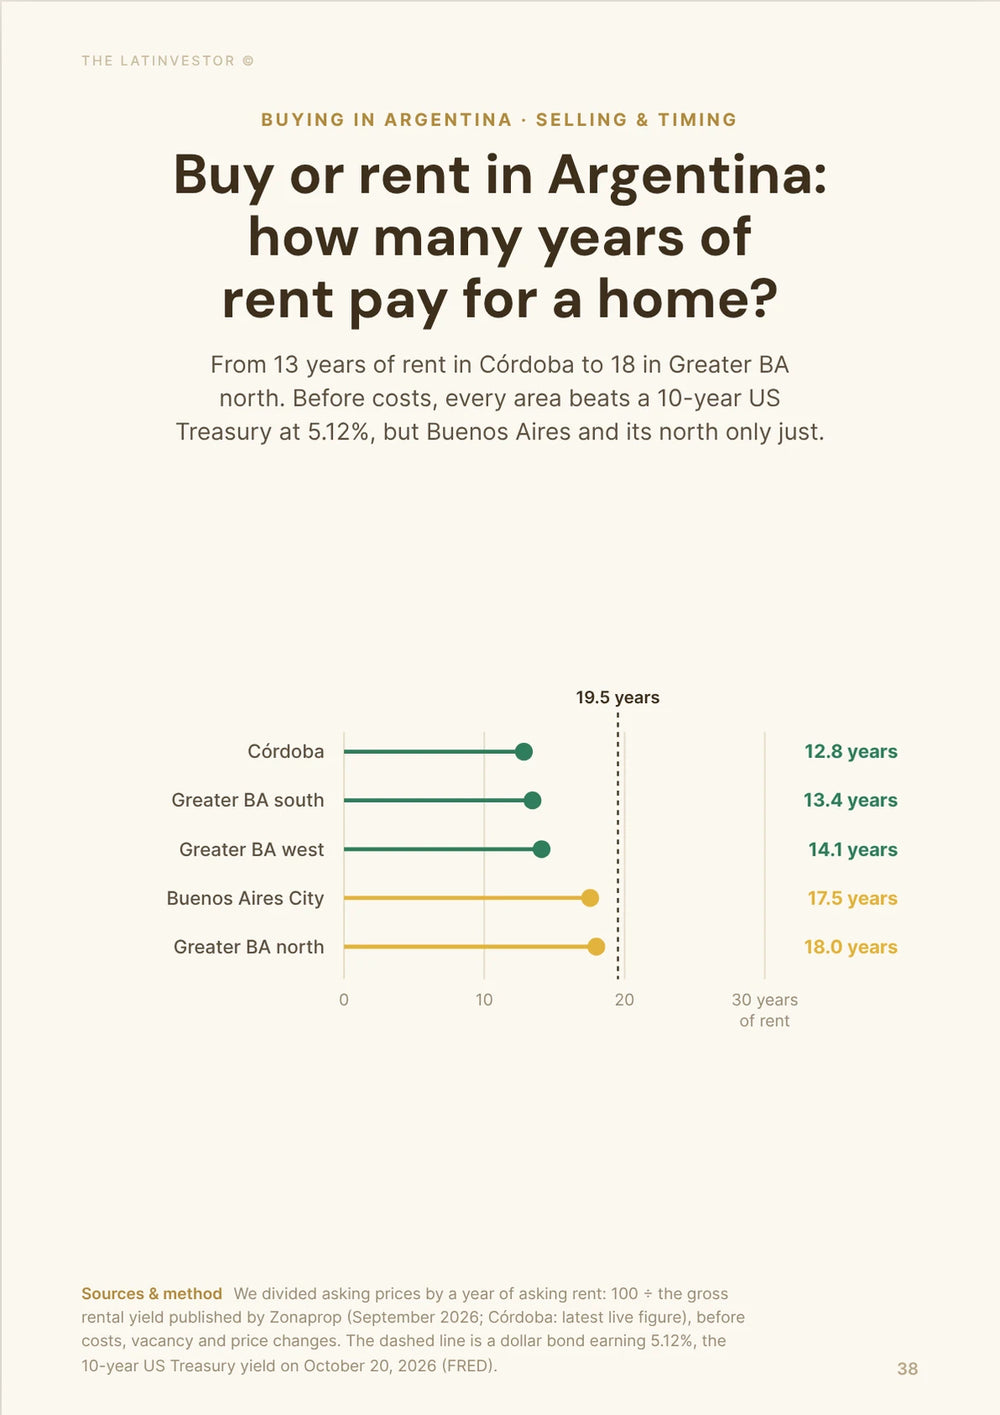
Yields have recovered and held: Buenos Aires City was at 2.3% in 2020 and is at 5.70% now, about 17.5 years of rent to repay the price.
Argentina is several markets: Córdoba shows 7.80% gross on Zonaprop's latest reading (March 2026), GBA South 7.44%, GBA West 7.10% and Rosario 5.99%.
Gross is not what you keep. On a USD 100,000 Buenos Aires flat, buying costs of 6% to 9% and one empty month take the 5.70% to about 4.8% to 4.9% before repairs, management and tax.
Rents now trail inflation: CABA asking rents rose 20.8% from January to September 2026, against about 23.6% inflation.
That is the price of deregulation. Since DNU 70/2023 you agree length, currency and index freely, but rental listings are 3.6 times their February 2023 low, so tenants have choice.
Prices have flattened: CABA asks USD 2,484 per m², 11.3% below its peak, and flats actually sold at about USD 2,097 per m² in September, down 0.4% in a year.
The easy rebound is over. The CABA yield slipped from 5.76% in July to 5.70% in September, so a good return now comes from the flat and the price you pay.
Cheaper areas pay more rent per dollar: a 50 m² flat in Lugano grosses about 9.5% on asking figures, one in Palermo about 4.6%.
Small units often yield more outside the capital (Córdoba studios about 6.71% vs 5.19% for three-bedrooms, Global Property Guide), but in Buenos Aires size matters less than the neighbourhood.
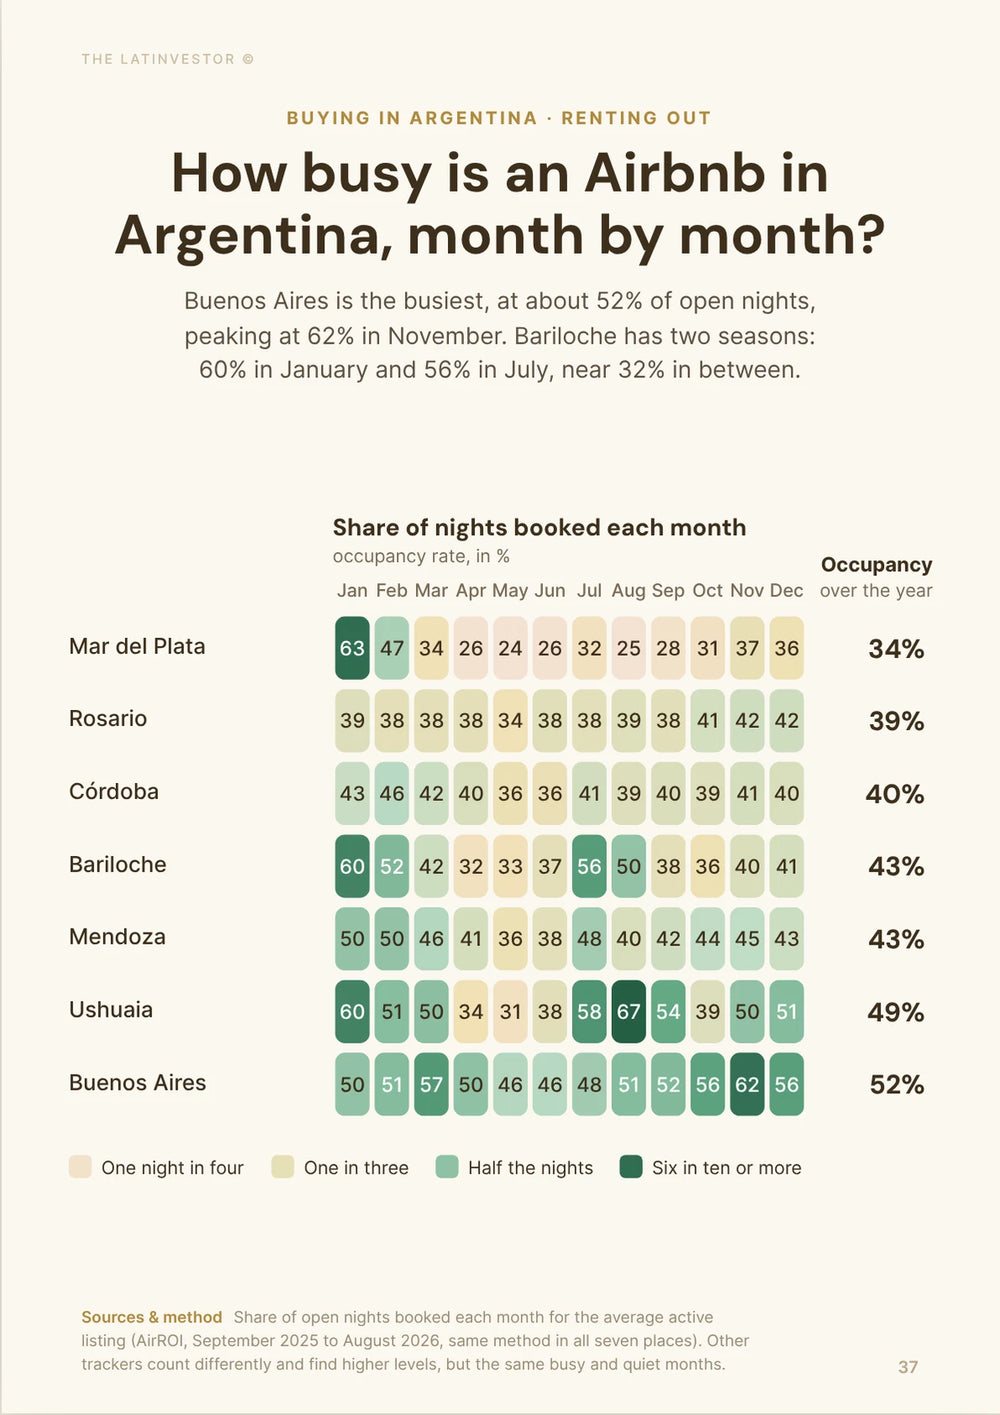
Airbnb is no automatic win: an average Buenos Aires one-bedroom grossed about USD 7,550 over the past year at 48% occupancy, before a 15.5% host fee and running costs.
Resale is fine in the mass market: Buenos Aires notaries recorded 41,583 sale deeds from January to August 2026, only 2.3% fewer than a year earlier, with mortgages down 34%.
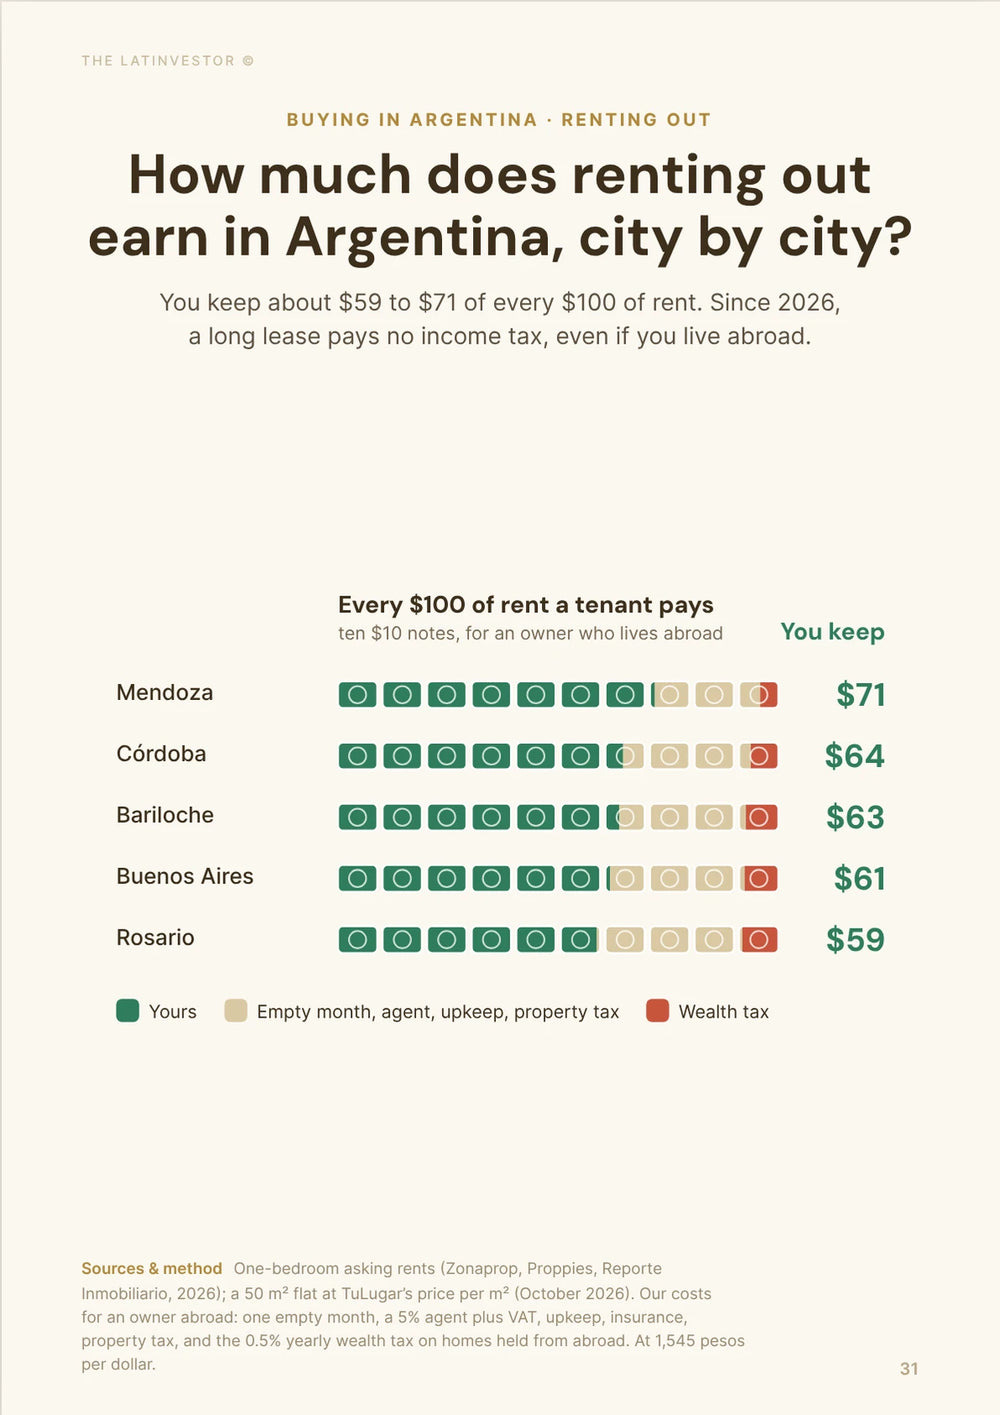
If you live abroad, budget 21% of gross rent in withholding until an adviser confirms the 2026 exemption applies to you: that takes a 5.3% gross flat to about 3.7%.
Our answer: buy with cash, negotiate below asking, and aim for 6% to 7% gross on a compact, ordinary flat in a liquid area; below 5% the rental case is weak.


What has changed for rental property in Argentina since 2020?
Rents, prices and lease rules now line up far better for landlords than a few years ago, and the yield recovery has held through 2026.
BBVA Research's 2026 real-estate review found that gross residential yields had roughly doubled from their 2020 lows across most big Argentine markets.
Zonaprop's September 2026 readings confirm it: 5.70% gross in Buenos Aires City, 7.44% in GBA South and 7.10% in GBA West. Its latest Córdoba reading (March 2026) is 7.80%, and Rosario (May 2026) 5.99%.
In 2020 Zonaprop measured just 2.3% in Buenos Aires City. At that level a flat needed more than 43 years of gross rent to repay its price. Today it is about 17.5 years in the city and 12.8 years in Córdoba.
That is enough to reopen the investment case. The harder question is what is left after costs, tax and risk.
| Market (Zonaprop) | Gross yield | Years of gross rent to repay price | What it tells us |
|---|---|---|---|
| Buenos Aires City (Sept 2026) | 5.70% | 17.5 years | Works again, with a moderate margin |
| Córdoba (Mar 2026, latest) | 7.80% | 12.8 years | Much stronger income case |
| GBA South (Sept 2026) | 7.44% | 13.4 years | Best reading around the capital |
| GBA West (Sept 2026) | 7.10% | 14.1 years | Clearly above the city |
| Rosario (May 2026) | 5.99% | 16.7 years | Close to Buenos Aires |
Is a 5.70% rental yield in Buenos Aires actually good?
It is decent, but an average deal at that level leaves little room for mistakes.
Take a USD 100,000 flat at the citywide average. Gross rent is USD 5,700 a year before anything goes wrong.
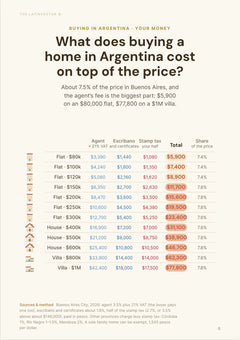
Buying adds to the money tied up. In Buenos Aires a buyer typically pays about 6% to 9% of the price in stamp tax, notary, registry and agent fees, so the flat really costs USD 106,000 to 109,000.
The same USD 5,700 is then 5.38% or 5.23% on the money actually invested. One empty month takes it to about 4.9% to 4.8%, before repairs, insurance, management or extraordinary building charges.
Global Property Guide estimates Argentine net yields at about 1.5 to 2 points below gross. So a normal 5.70% Buenos Aires flat ends up near 4% for a resident, and lower for a foreign owner (see the tax section).
That gives a clear threshold: a flat close to 7% gross is far more interesting than one barely reaching 5%.
| USD 100,000 flat | Rent received a year | Money actually committed | Yield before other costs |
|---|---|---|---|
| Headline gross yield | USD 5,700 | USD 100,000 | 5.70% |
| With 6% buying costs | USD 5,700 | USD 106,000 | 5.38% |
| With 9% buying costs | USD 5,700 | USD 109,000 | 5.23% |
| One empty month + 6% costs | USD 5,225 | USD 106,000 | 4.93% |
| One empty month + 9% costs | USD 5,225 | USD 109,000 | 4.79% |
| Same + 21% non-resident withholding (6% costs) | USD 4,128 | USD 106,000 | 3.89% |
Are Buenos Aires rents still rising faster than inflation?
No. They are now rising a little more slowly than inflation, so do not count on another big real jump in rent.
Zonaprop puts the average asking rent for a 50 m² two-room flat in CABA at ARS 898,154 a month in September 2026, about USD 580. That is 28.7% more than a year earlier, against 33.4% inflation (INDEC).
From January to September 2026, asking rents rose 20.8% while consumer prices rose about 23.6%, a real fall of about 2.3%. September's 1.3% rise was the smallest monthly increase of the year.
Greater Buenos Aires is weaker still: two-room rents there rose about 14% to 15% over the same months, a real fall of 7% to 8%.
This fits the longer trend. After the old rental law was repealed at the end of 2023, rent growth slowed sharply from the extreme rates of 2023 and early 2024, because many more flats came back on the market.
For a purchase today, assume rents roughly track inflation and treat anything better as a bonus.
Did Argentina really make rental contracts better for landlords?
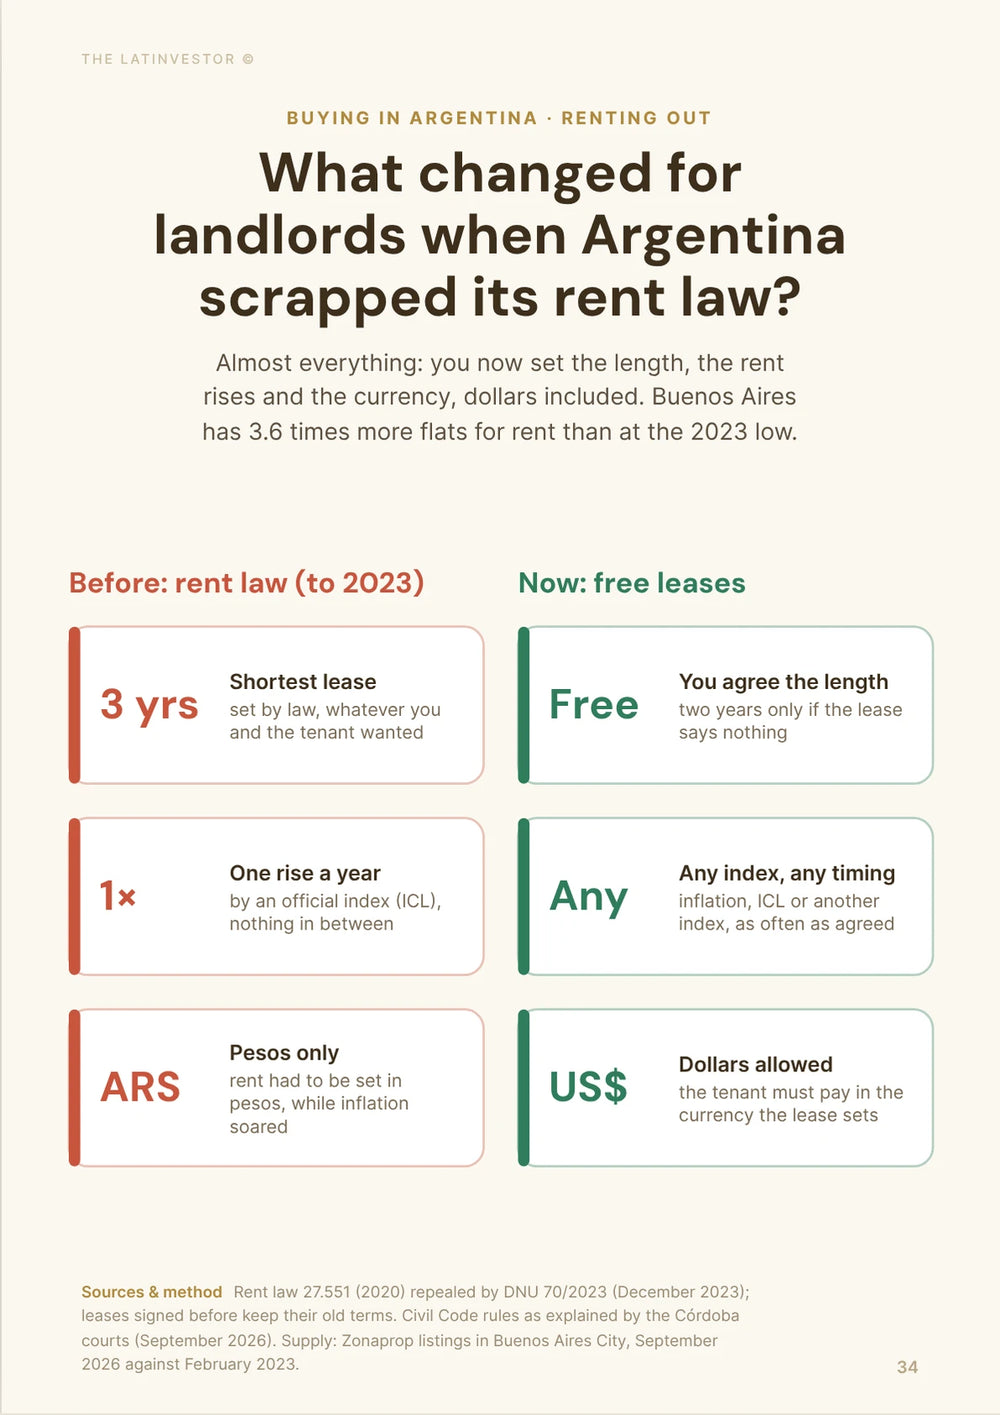
Yes. Since DNU 70/2023 repealed the 2020 rental law, landlord and tenant set most of the terms themselves under the Civil and Commercial Code.
They agree the length of the lease. For a home rental with no term written in, the default is two years.
They choose the currency. Rent can be set in pesos or dollars, and the tenant cannot insist on paying in a different currency from the one agreed.
They choose the index and how often rent is updated: inflation (IPC), ICL, UVA or another public or private index. Rent is still paid at least monthly.
That matters with 33.4% annual inflation: a rent frozen for a year loses a quarter of its value. Quarterly or four-monthly updates fix most of that.
Dollar rents do not turn a local flat into a dollar bond. Most tenants earn pesos, so a dollar rent only works if their income keeps up. And contracts signed under the old law keep their old terms until they end, so check this if you buy with a tenant in place.
| Lease issue | Current rule | Why a landlord cares |
|---|---|---|
| Contract length | Freely agreed | Easier to fit the lease to the flat |
| Default home rental term | Two years if nothing is written | Clear fallback |
| Rent currency | Pesos or dollars | More ways to handle currency risk |
| Rent updates | Index and frequency agreed (IPC, ICL, UVA…) | Better protection against inflation |
| Old contracts | Keep pre-DNU terms until they end | Check before buying with a tenant |
Did deregulation flood Buenos Aires with rental apartments?
Yes. A lot of housing came back to the long-term market, which is healthy for the market and less good for owners hoping for a shortage.
Zonaprop recorded a 62% jump in CABA rental listings in the first month after the repeal.
It kept going. La Nación reported on 19 October 2026 that rental listings in Buenos Aires are 3.6 times their February 2023 low.
That explains today's softer rents: landlords got contract freedom at the same time as tenants got far more choice.
Flats that sat empty, were listed for sale or had moved to temporary rentals became normal long-term rentals again.
So you compete on price and quality. A badly located flat with high building fees will not find a tenant at any price just because the city is short of rentals. It no longer is.
Are Buenos Aires property prices still cheap today?
Still below the old peak, but you have missed the bottom.
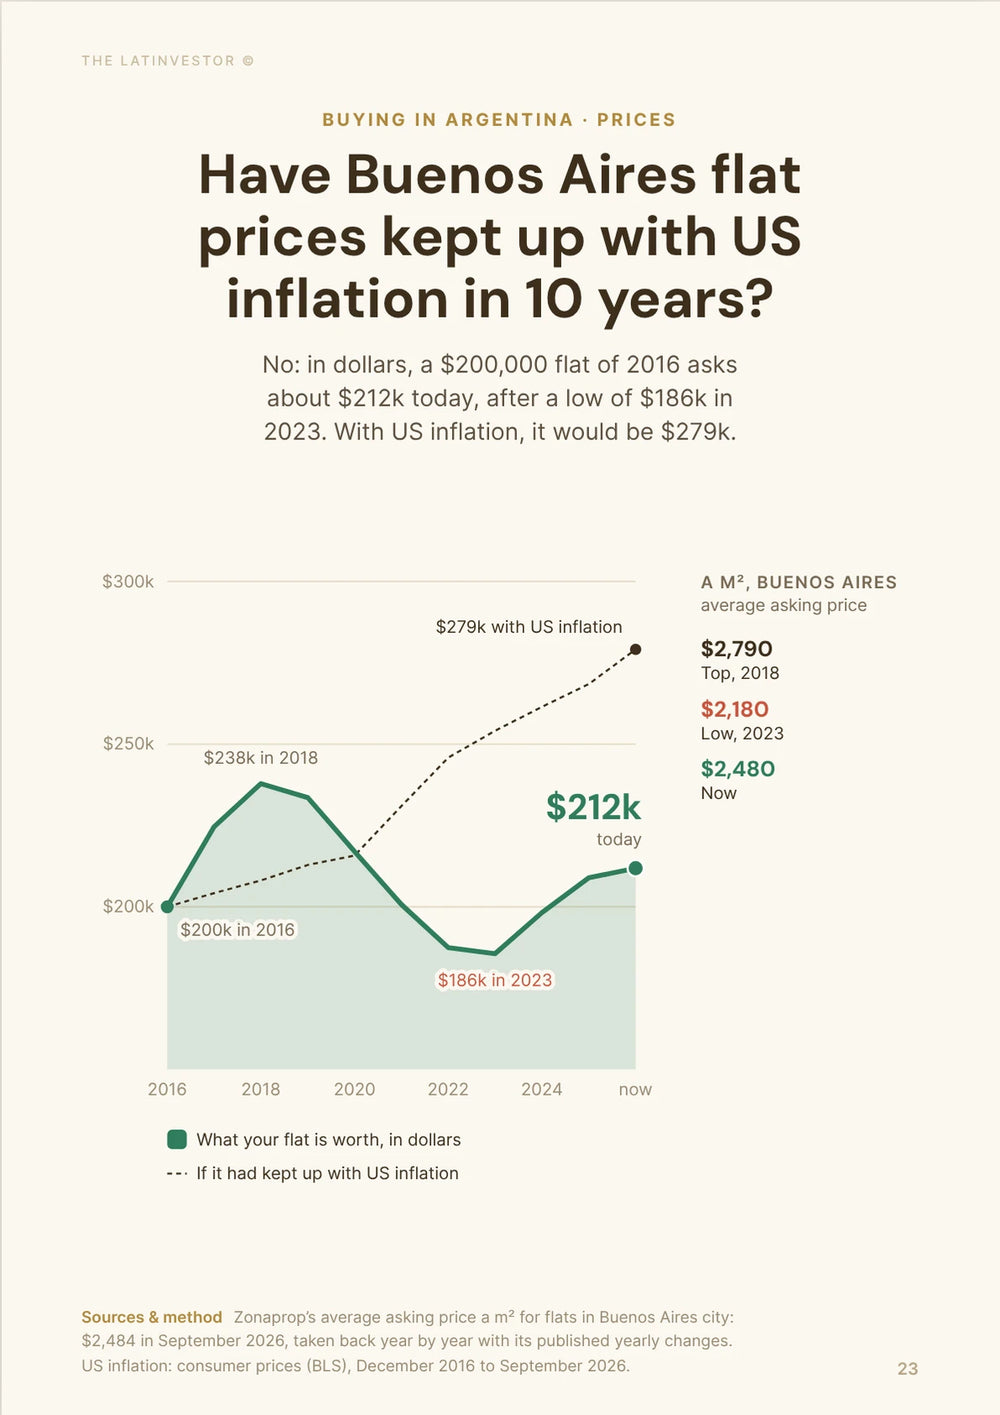
Zonaprop puts the average CABA asking price at USD 2,484 per m² in September 2026, up 0.3% in the month and 1.4% since January, and still 11.3% below the peak of its series.
Closing prices are calmer: used flats actually sold at about USD 2,097 per m² in September, down 0.4% in a year (RE/MAX, UCEMA and Reporte Inmobiliario). Start your sums there, not from listings.
So the market has recovered without turning into a boom.
Zonaprop's model flats ask about USD 110,000 for a 40 m² studio, USD 131,000 for a 50 m² one-bedroom (two-room, or 2 ambientes, locally) and USD 180,000 for a 70 m² two-bedroom.
Used flats are usually the better rental buy. La Nación reported in July 2026 that a used flat costs about 32.6% less on average than a new one, and the city statistics office (IDECBA, Q2 2026) found new-build premiums of about 21% for studios, 37% for two-room and 55% for three-room flats.
A new flat rarely rents for that much more. A well-kept used flat bought at the right price usually gives the better yield.
| Typical CABA apartment (Zonaprop, Sept 2026) | Size | Average asking price |
|---|---|---|
| Studio | 40 m² | USD 110,000 |
| One-bedroom / 2 ambientes | 50 m² | USD 131,000 |
| Two-bedroom / 3 ambientes | 70 m² | USD 180,000 |
| Citywide average, asking | — | USD 2,484/m² |
| Citywide average, closing (used) | — | USD 2,097/m² |
Has the easy part of the Buenos Aires rental recovery already happened?
Yes. Most of the yield recovery is done, so you need a good individual deal rather than a market that reprices for you.
BBVA Research's long series shows the cycle: yields fell to extreme lows around 2020, then climbed for several years as peso rents caught up, dollar prices stayed low and the rental law changed.
That mix was a gift for anyone buying near the bottom.
Today it is calmer. CABA prices are flat in dollars, rents trail inflation, and Zonaprop's CABA yield slipped from 5.76% in July to 5.70% in September 2026.
That does not make 5.70% bad. It means the automatic catch-up is over.
An average flat at an average price gives an average return. To do better you need something the averages miss: a discount on the asking price, low building fees, a layout tenants want, a street where rent is high next to the price, or a flat you can fix up cheaply.
Is Córdoba actually better than Buenos Aires for rental property?
On gross yield, yes, by a clear margin, though the gap is probably smaller than the headline.
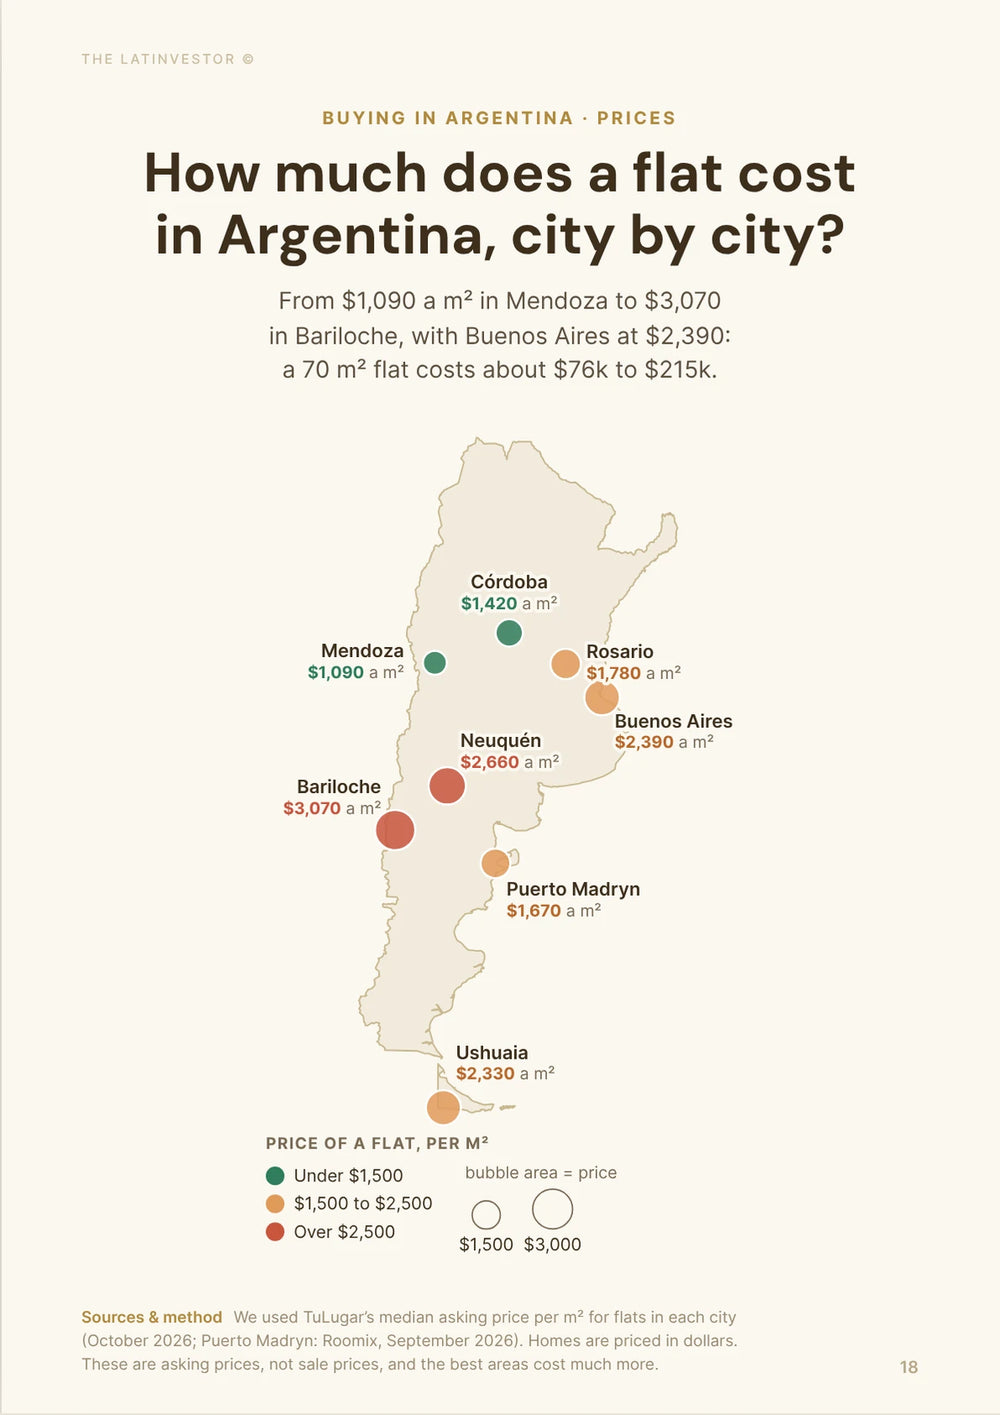
Zonaprop's latest Córdoba reading is 7.80% gross, about 12.8 years of rent to repay the price, against more than 17 years in Buenos Aires City. Prices are low: about USD 1,420 per m² on TuLugar in October 2026.
On USD 100,000, 7.80% means USD 7,800 of rent a year against USD 5,700 at 5.70%: USD 2,100 more before costs.
Two caveats. Zonaprop has not updated Córdoba since March 2026, and Proppies, which tracks one-bedroom flats, found a lower 6.8% in September. Global Property Guide's sample puts Córdoba at 5.99% on average and studios at about 6.71%.
The sources disagree on the size of the gap, not its direction: Córdoba pays more rent per dollar.
Buenos Aires keeps real advantages: a much bigger market, more foreign demand and easier resale. Córdoba has to pay you for a smaller market, and the neighbourhood matters a lot there.
If cash flow is your main goal, look at Córdoba before defaulting to Buenos Aires. Budget buying costs of about 6% to 7% there.
Where else in Argentina are rental yields attractive now?
Several markets reach about 6% to 7.5% gross, so Buenos Aires City is not the obvious default.
GBA South stood at 7.44% in September 2026 (13.4 years of rent to repay the price) and GBA West at 7.10%. GBA North, priced like the city, was at 5.56%.
Rosario is close to the capital: 5.99% gross and 16.7 years on Zonaprop's May 2026 reading.
Global Property Guide gives different numbers because it uses its own sample: 5.46% for Argentina as a whole in Q2 2026, Córdoba about 5.99%, Rosario 4.12%.
That disagreement is the lesson. There is no single Argentine rental yield: change the area, the flat size or the sample and the number moves by a point or two.
A 7% flat in a liquid part of Córdoba can beat a 4.5% flat in an expensive Buenos Aires suburb. But a very high yield in a weak spot is a trap if tenants are hard to find or buyers vanish when you sell. City averages are a filter; the decision is flat by flat.
| Market | Latest Zonaprop gross yield | Main reason to look | Main thing to check |
|---|---|---|---|
| Córdoba | 7.80% (Mar 2026) | Strong current income | Neighbourhood and resale depth |
| GBA South | 7.44% (Sept 2026) | Low entry prices | Location quality varies sharply |
| GBA West | 7.10% (Sept 2026) | Cheaper entry than the city | Train lines and tenant demand |
| Rosario | 5.99% (May 2026) | Competitive entry price | Local demand and liquidity |
| Buenos Aires City | 5.70% (Sept 2026) | Deepest rental and resale market | Higher purchase price |
Which Buenos Aires neighborhoods make the most sense for a landlord?
The best yields are away from the expensive areas foreign buyers know best.
Zonaprop names Lugano and Nueva Pompeya as the best CABA neighbourhoods for rental income in September 2026.
The usual foreign shortlist starts with Palermo, Recoleta, Belgrano or Puerto Madero. Their prices reflect that popularity.
The figures show the gap. A two-room flat asks ARS 660,673 a month in Lugano (about USD 425) against ARS 1,005,424 in Palermo, but a square metre costs USD 1,071 in Lugano and USD 3,409 in Palermo. On those asking figures a 50 m² flat grosses about 9.5% in Lugano and about 4.6% in Palermo. TuLugar puts Palermo at 4.7% and Recoleta at 4.3%.
That does not mean buying the cheapest spot on the map. Tenant demand, safety, transport, building quality and resale all count, and asking rents in cheap areas are not always what tenants sign.
The right question: where do tenants pay a lot of rent next to the sale price? If income comes first, that often means less fashionable areas. If you want foreign tenants, capital safety and an easy resale, a lower yield in a prime area can be a fair choice.
Are small apartments better rental investments in Argentina?
Often in the provinces, not always in Buenos Aires. Check the numbers flat by flat.
Global Property Guide's Q2 2026 Córdoba sample shows the classic pattern: about 6.71% gross for a studio and 6.56% for a one-bedroom, then 5.49% for two bedrooms and 5.19% for three.
Rosario is steeper in the same dataset: studios about 5.17%, one-bedrooms 4.66%, two-bedrooms 3.65% and three-bedrooms 3.02%.
Buenos Aires breaks the rule. Zonaprop's 70 m² model flat asks about 37% more than the 50 m² one (USD 180,000 vs 131,000) and rents for about 35% more (ARS 1,214,267 vs 898,154 a month), so both gross about 5.2% to 5.3%. In San Isidro, Global Property Guide even shows three-bedrooms at 8.54%.
Small units still have real advantages: less capital, a wide pool of students, young professionals and couples, and the option to spread money over several flats.
The best rental is often boring: a compact flat near transport, universities or offices, bought at a price that fits the rent.
How much do taxes, vacancy and expenses cut Argentine rental returns?
Running costs take about 1.5 to 2 points off gross yield, and for a foreign owner tax can take more than another point.
That is Global Property Guide's estimate of the gap between gross and net in Argentina.
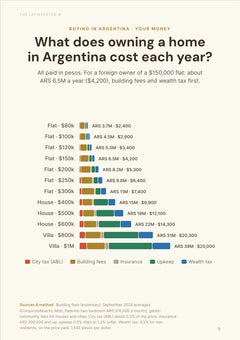
Every empty month removes 8.3% of a year's rent. Older buildings bring surprise repairs and extraordinary building charges; CABA building fees (expensas) averaged ARS 379,774 a month in September 2026 (about USD 245), up 28.6% in a year (ConsorcioAbierto). Tenants usually pay ordinary expensas, but big works fall on the owner. Furnished rentals add furniture and utilities, and an owner abroad will need a local manager.
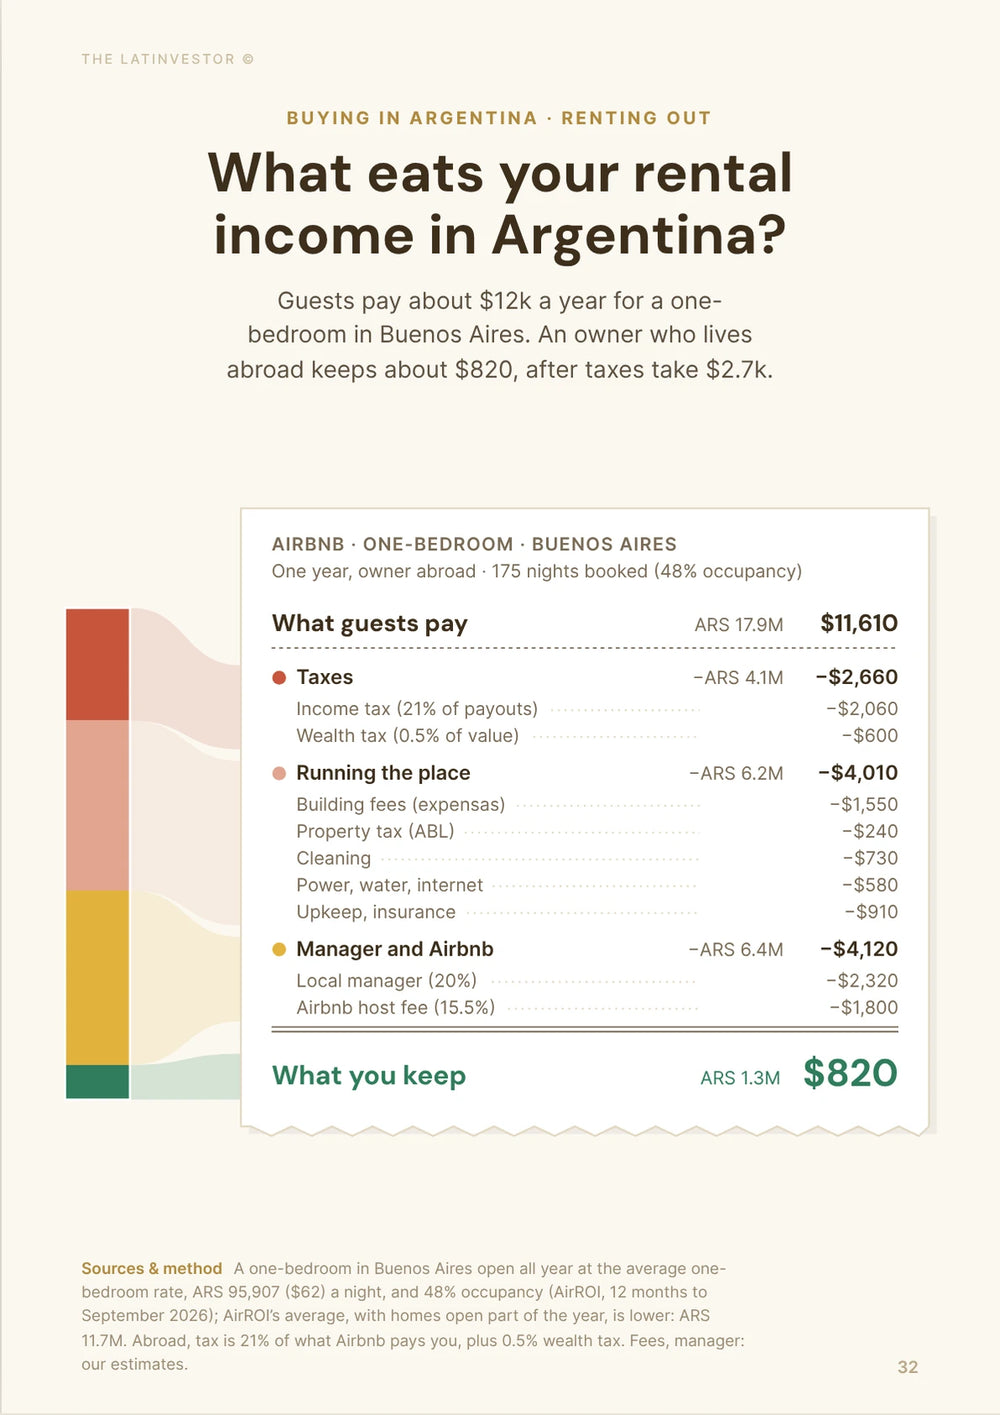
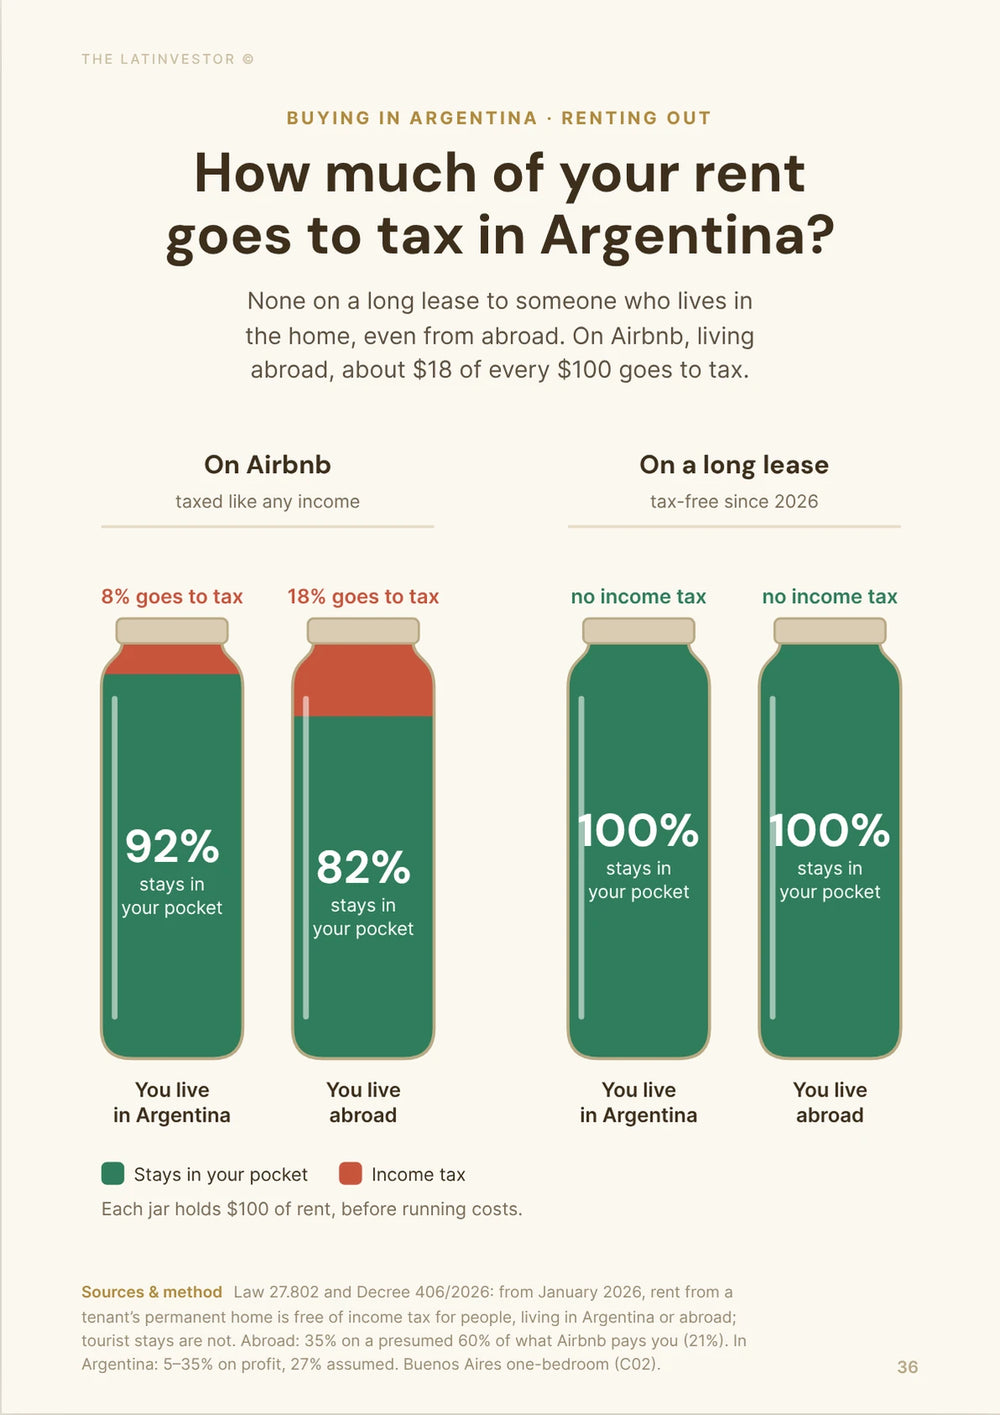
Tax depends on who you are. Since 1 January 2026, a resident individual renting a home to a tenant as their permanent residence pays no income tax on that rent (Decree 406/2026). For landlords living abroad the decree is silent, so the default is a 35% withholding on a presumed 60% net, which is 21% of gross rent. Non-resident owners also pay wealth tax (Bienes Personales) of 0.5% a year on the property's tax value, through a local representative. Landlords still register with ARCA and invoice.
This is where weak deals show. A 7.5% gross flat that loses 2 points to costs still leaves about 5.5%. A 5% flat with the same drag falls to about 3%.
That is why the entry yield matters so much. Mortgages are scarce, buying costs are high and Argentina has plenty of other risks: a thin starting yield makes the whole thing fragile.
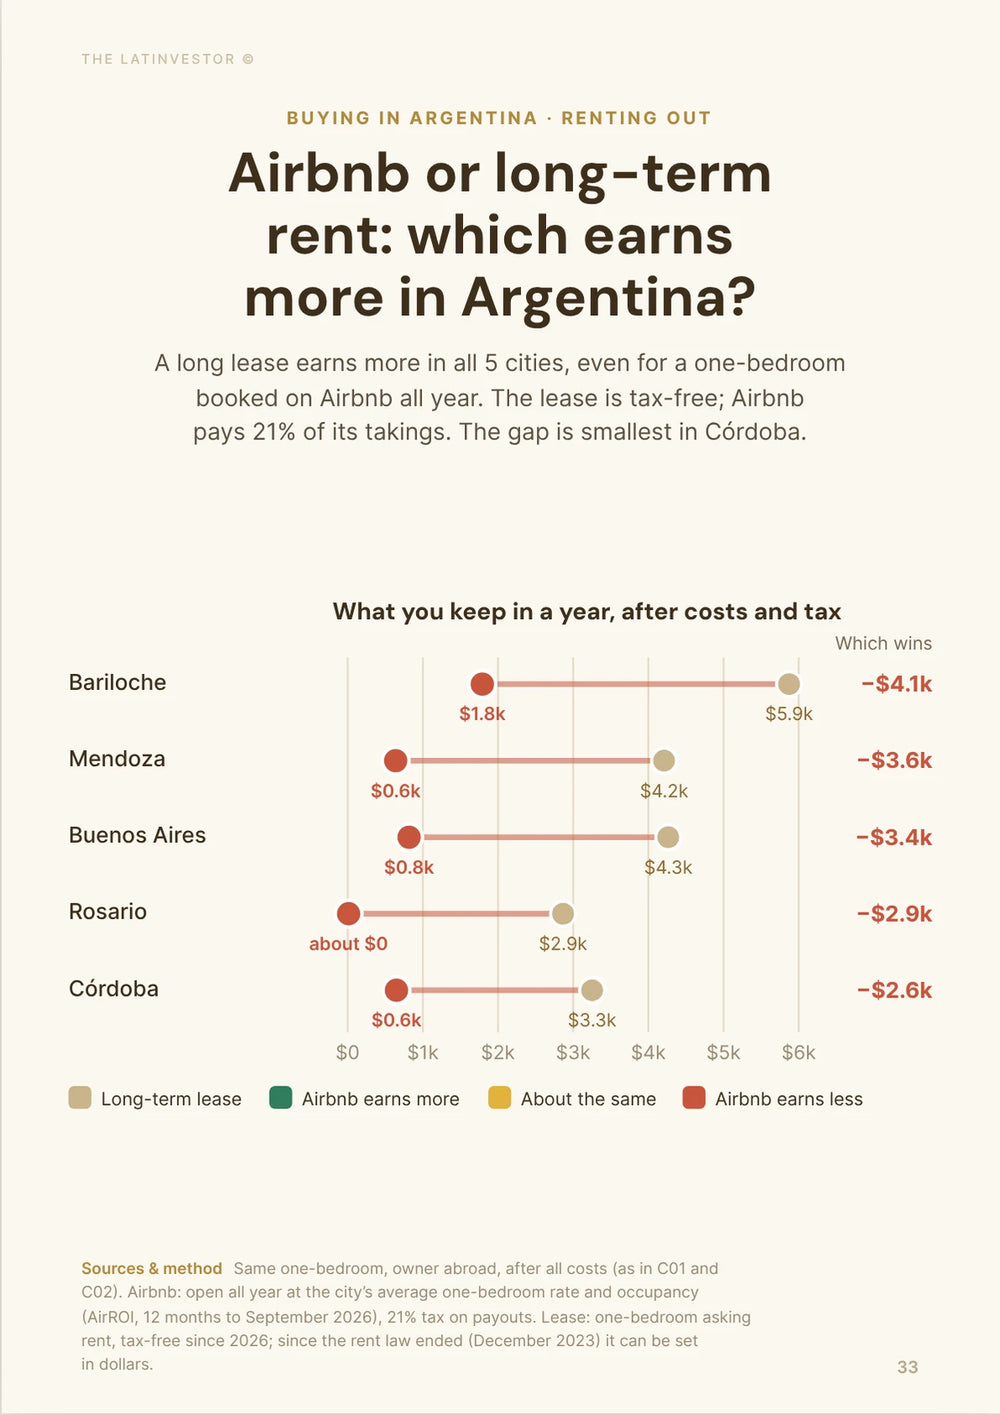
Is Airbnb more profitable than a normal rental in Buenos Aires?
The best flats, yes. The average one, barely, and with far more work, cost and rules.
AirROI tracked about 22,600 active Airbnb listings in Buenos Aires from October 2025 to September 2026, at 48% average occupancy. An average entire one-bedroom earned about ARS 10.9 million over the year, about USD 7,550 at the ARS 1,443 per dollar AirROI used.
A long lease on a 50 m² two-room flat at Zonaprop's September asking rent brings about ARS 10.8 million a year (about USD 6,950). So the average Airbnb is only about 9% ahead on revenue, before Airbnb's 15.5% host fee, cleaning, utilities, internet, furniture, linen and someone to handle check-ins.
The upside is real in the right spot. TuLugar's September 2026 data shows active Palermo listings at 71% occupancy and USD 73 a night, about USD 1,517 a month gross.
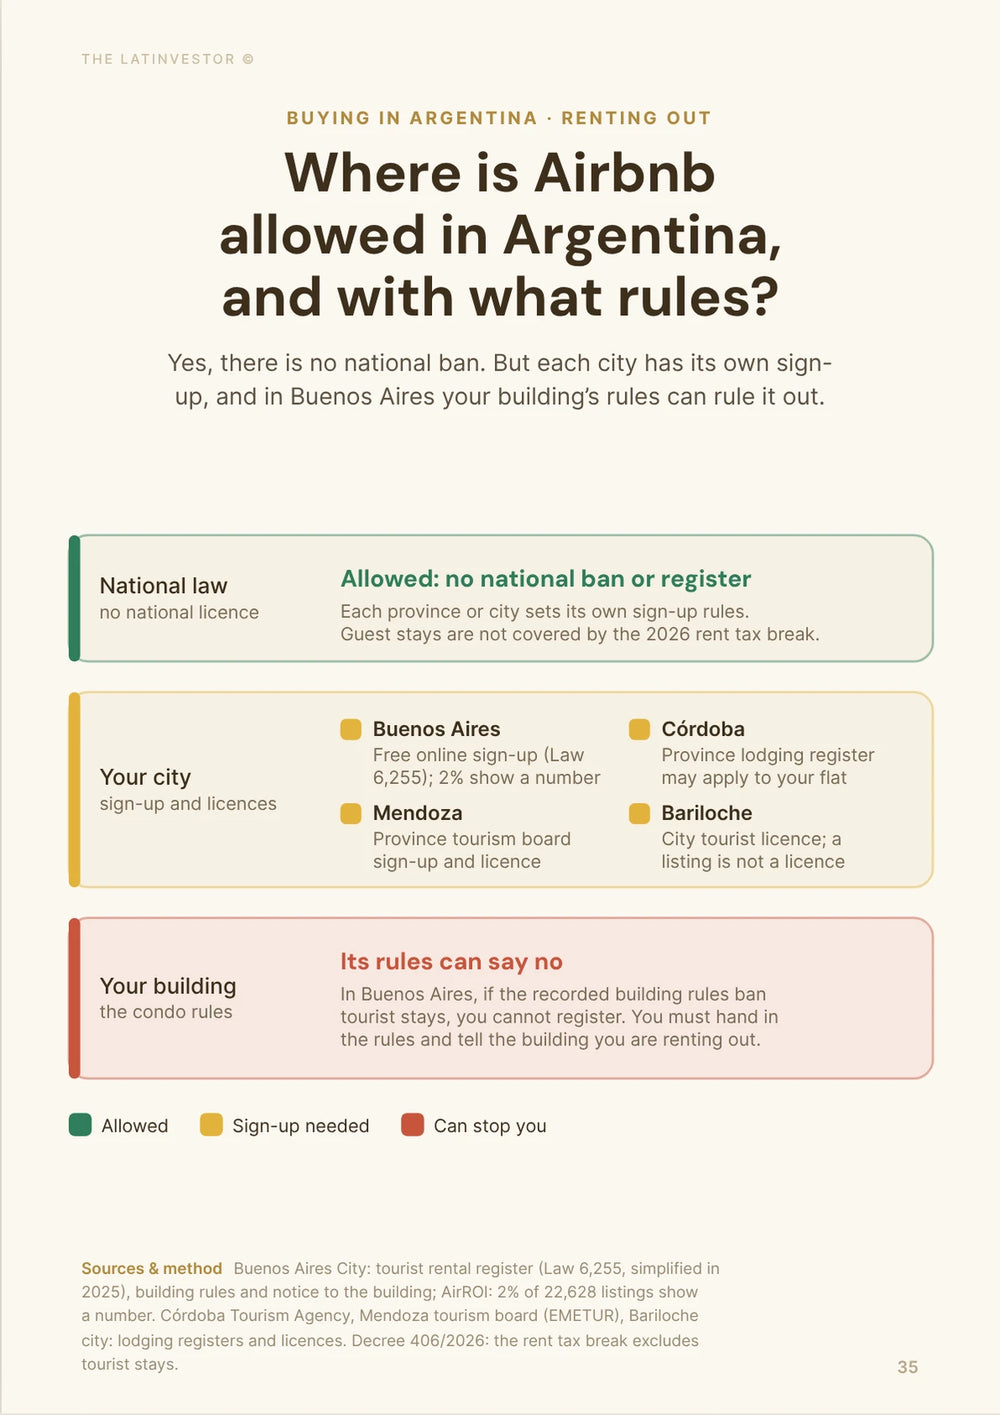
Rules and tax cut the other way. Buenos Aires City requires tourist rentals to be registered in its temporary tourist rental registry (Law 6,255), with proof of ownership, civil-liability insurance and the building's rules, which must not forbid it. Tourist rentals get no 2026 income-tax exemption: a non-resident should budget about 21% of gross, plus the city's gross-income tax.
So compare net income, not monthly revenue. Buying a weak long-term rental and hoping Airbnb will rescue it is a bad plan.
Can you actually resell a Buenos Aires rental property easily today?
In the mass market, yes. Cash buyers keep sales high even as mortgages cool.
The Buenos Aires Colegio de Escribanos counted 6,055 sale deeds in August 2026, 4.9% fewer than a strong August 2025, and 41,583 from January to August, only 2.3% fewer than a year earlier.
Mortgages tell a different story: 6,170 mortgage deeds from January to August, down 34%, or about 15% of sales. Nationally, 14,237 mortgage loans were granted from January to July 2026, against 25,160 a year earlier.
So sales are holding up without credit: cash and other non-mortgage buyers carry the market.
The average deed from January to August was worth about USD 119,000, the price of a small Buenos Aires flat. Buy around that level and you sell into the busiest part of the market, not a thin luxury niche.
If credit picks up again, the pool of buyers grows. Treat that as a possible bonus, not a reason to buy now.
| Buenos Aires resale indicator | Latest reading | What it tells you |
|---|---|---|
| Sale deeds, August 2026 | 6,055 (−4.9% y/y) | Still high activity |
| Sale deeds, Jan–Aug 2026 | 41,583 (−2.3% y/y) | Market close to last year |
| Mortgage deeds, Jan–Aug 2026 | 6,170 (−34% y/y) | Credit has cooled |
| Mortgage share of sales, Jan–Aug | ~15% | Cash buyers carry the market |
| Average deed, Jan–Aug 2026 | ~USD 119,000 | Mass-market price level |
Will you pay tax on Argentine rent if you live abroad?
Plan on it. The 2026 rent exemption clearly covers residents; for landlords living abroad it is not confirmed.
Decree 406/2026, published on 1 June 2026, exempts from income tax, from 1 January 2026, rent an individual earns when the tenant uses the home as their only permanent residence. It says nothing specific about non-residents. Tax firm Estudio Piccinini wrote on 29 June 2026 that it is unclear whether the exemption reaches them.
Until that is settled, the tenant or agent should withhold 35% on a presumed 60% net, which is 21% of gross rent. On a USD 131,000 one-bedroom renting at Zonaprop's September average (about USD 6,950 a year, 5.3% gross), that is about USD 1,460 a year. Add up to USD 655 of wealth tax at 0.5% (less in practice, since tax values are usually below market) and you are near 3.7% before vacancy and repairs.
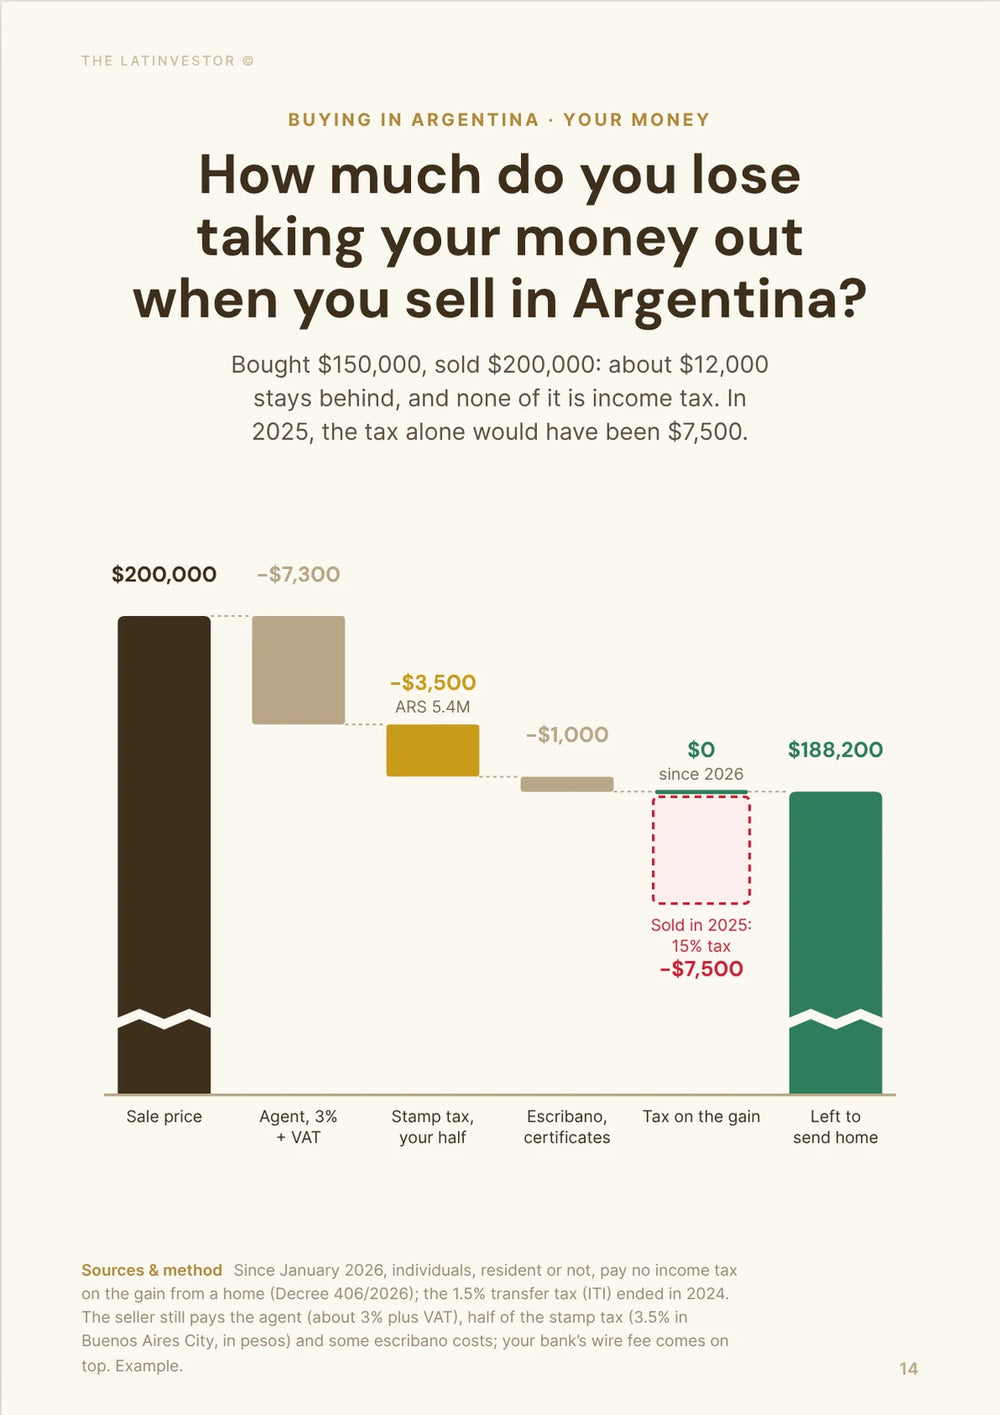
What to do: ask an Argentine tax adviser in writing whether your lease qualifies, make sure the contract says the flat is the tenant's permanent home, and run your numbers with the 21%. If the exemption is confirmed later, take it as a bonus. The good news is at the exit: since January 2026 individuals, residents and non-residents alike, pay no income tax on the gain when they sell (Law 27.802 and Decree 406/2026).
How far below the asking price should you buy a rental flat in late 2026?
Below it, always. With flat prices and plenty of listings, the asking price is an opening bid.
Two figures frame the talk. The closing-price survey behind the RE/MAX, UCEMA and Reporte Inmobiliario index puts the average real negotiation in Buenos Aires at about 4.75%. And used flats closed at about USD 2,097 per m² in September 2026, against USD 2,484 asked on Zonaprop: the samples differ, so that 15.6% gap is not a discount, but it shows how far listings can sit above real deals.
A discount goes straight into your yield. Pay USD 124,800 instead of USD 131,000 for a flat renting at about USD 6,950 a year and the gross yield goes from 5.3% to 5.6% without a single extra peso of rent.
What to check before you offer: the deeds of similar flats in the same building or block (ask the notary or agent), the building's expensas and any planned extraordinary works, the signed rent of comparable flats (ask two local agents, not just the portal), and whether the building's rules allow short-term rentals if that is your plan.
Does the strong peso help or hurt a rental bought in 2026?
It has helped owners collecting rent this year and made buying more expensive for anyone arriving with dollars. It can turn.
The wholesale dollar rose only about 4.9% between January and October 2026 (to about ARS 1,526), while consumer prices rose about 23.6%. CABA rents rose 20.8% over January–September, so a peso rent buys about 15% more dollars than in January.
The other side: Argentina got more expensive in dollars. Building fees, repairs and agents' fees, all set in pesos, cost more for a foreign owner, and construction costs rose 31.3% in a year (INDEC, September 2026).
Forecasters surveyed by the central bank (REM, September 2026) expect the dollar around ARS 1,614 at the end of 2026, and several banks see about ARS 1,950 to 2,100 by the end of 2027. If rent updates lag a devaluation, your dollar income drops. Write updates every three or four months into the lease and always do your sums in the currency you spend.
Is rental property worth buying in Argentina?
Yes, when the flat can really earn about 6% to 7% gross or more. Average low-yield deals need much more caution.
The market is very different from a few years ago. Yields have recovered from 2.3% in 2020 to 5.70% in Buenos Aires City, Córdoba shows 7.80% on Zonaprop's latest reading and the southern and western suburbs of Buenos Aires 7.1% to 7.4%.
Landlords can now negotiate length, currency and index freely. But rental listings are 3.6 times their 2023 low and rents trail inflation, so the extra freedom does not mean higher rents.
Prices help: CABA asking prices are 11.3% below their peak and closing prices slipped 0.4% in a year. You are buying after the bottom but before any boom.
Resale works: 41,583 Buenos Aires sale deeds from January to August 2026 despite a 34% drop in mortgage deeds.
The weak point is net return. Buying costs add 6% to 9% to the capital, running costs take 1.5 to 2 points of yield, and a landlord living abroad may lose 21% of gross rent to withholding. A flat that starts near 5% gross ends up unimpressive very quickly.
So the bar is simple.
| Gross yield at purchase | Our view today | Why |
|---|---|---|
| Below 5% | Usually weak as a pure rental | Costs and tax leave very little |
| 5%–6% | Only with another clear advantage | Location, resale or price gains must compensate |
| 6%–7% | Good territory | Enough income to absorb normal friction |
| 7%–8% | Strong, if the rent is real | Income becomes truly attractive |
| Above 8% | Find out why first | May hide vacancy, location or resale problems |
For a cash buyer who can hold several years, the best buys are ordinary flats: compact, bought below asking, with low building fees and steady tenant demand all year. Córdoba deserves a serious look for income; Buenos Aires still has the deepest pool of tenants and future buyers.
Prestige flats are hard to justify when their rent does not keep up with their price, and so are deals that only work with fast price gains or another big rise in real rents.
Argentina is past the stage where every rental looked broken, and past the easy rebound. Good flats bought well can be really attractive; average ones give average returns, and the price you pay now matters more than the Argentina story.
Our methodology
This article asks whether buying rental property in Argentina is worth it in 2026. It covers gross and net yields, buying and running costs, rents against inflation, lease rules, rental supply, prices, flat size, neighbourhoods, Airbnb, tax for residents and foreign owners, the peso and resale, with most weight on Buenos Aires and comparisons with Córdoba, Rosario and Greater Buenos Aires.
Gross yields come from Zonaprop's rent-to-price indices (Buenos Aires City and GBA for September 2026, Rosario for May 2026, Córdoba for March 2026, its latest), cross-checked with Global Property Guide (Q2 2026), Proppies and TuLugar, with BBVA Research for the long cycle. Rents come from Zonaprop's CABA index and its neighbourhood figures via Infobae; asking prices from Zonaprop and closing prices from the RE/MAX, UCEMA and Reporte Inmobiliario index; new versus used from La Nación and IDECBA; buying costs from the Colegio de Escribanos, AGIP and La Nación; building fees from ConsorcioAbierto; sales and mortgage deeds from the Buenos Aires Colegio de Escribanos; Airbnb from AirROI and TuLugar, never mixed in one calculation; rental supply from Zonaprop and La Nación.
Tax and legal rules come from Decree 406/2026 and Law 27.802 (income tax on rent and resale), Estudio Piccinini's June 2026 note on non-resident landlords, DNU 70/2023 and the Civil and Commercial Code (leases), ARCA's landlord registration rules and Buenos Aires City's tourist-rental registry. Inflation comes from INDEC and exchange-rate forecasts from the central bank's REM survey.
We checked these figures in October 2026. Peso amounts are converted at about ARS 1,550 per US dollar (official and MEP rates were within 1% of each other on 22 October 2026, the blue rate about ARS 1,570), and euro amounts at about ARS 1,740 per euro. AirROI's revenue is converted at its own rate of ARS 1,443 per dollar.
Where we had no direct figure, we said so or gave a range. Córdoba and Rosario have no Zonaprop yield after March and May 2026; net yields use Global Property Guide's general estimate of 1.5 to 2 points of costs, not a measured figure; the Lugano and Palermo yields are our own rough sums from asking prices; and the 21% withholding for non-residents is the default rule, not a final position on the 2026 exemption.
Key sources used for this analysis include BBVA Research's Argentina Real Estate Outlook 2026, Zonaprop's CABA rental-yield index, Zonaprop's CABA rent index, Zonaprop's sales-price index, Zonaprop's Córdoba yield index, Zonaprop's GBA South yield index, Zonaprop's Rosario yield index, Revista Mercado on CABA prices (October 2026), Infobae on CABA rents by neighbourhood, Reporte Inmobiliario's closing-price index, Global Property Guide's Argentina yields, Proppies' Córdoba rental index, TuLugar's September 2026 report, AirROI's Buenos Aires data, Airbnb's host fees, the Buenos Aires Colegio de Escribanos (August 2026 deeds), La Nación on buying costs, La Nación on new versus used flats, Decree 406/2026, Estudio Piccinini on non-resident landlords, DNU 70/2023, the Civil and Commercial Code, Buenos Aires City's tourist-rental registry, ARCA's landlord registration guidance, INDEC's consumer-price series, Infobae on September 2026 inflation and Infobae on the dollar (October 2026).