
Summary
Only the cheap ones: at UVA + 6.5% to 7.5% a UVA mortgage can work for a buyer with stable peso income who plans to stay; at 9.5% to 12%, as charged to borrowers without the right salary account, it rarely does.
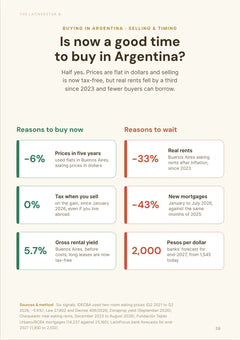
Buyers did not disappear, credit did: Buenos Aires City deeds fell only 2.3% from January to August 2026, while deeds with a mortgage fell 34%, and new mortgages nationwide fell 43% from January to July.
"UVA + 6.7%" is not a 6.7% loan. You pay 6.7% on a balance that also rises with inflation, which was 33.4% over the 12 months to September 2026 and 1.9% in September alone.
The real test is your own pay: INDEC's wage index rose 35.7% over the year to June 2026, but registered private-sector wages, the ones banks lend against, rose only 29.6%.
The rate gap is huge. On a 30-year loan of about ARS 152 million (75% of a USD 131,000 one-bedroom), the first payment is about ARS 983,000 at 6.7% and ARS 1.51 million at 11.5%, and total payments go from 2.3 to 3.6 times the loan in real terms.
At the best rates, owning costs about the same as renting each month: that one-bedroom rents for about ARS 898,000 (Zonaprop, September 2026), only ARS 85,000 less than the 6.7% payment, but you need USD 32,750 down plus 6% to 9% in buying costs.
Prices will not bail out a bad loan: Buenos Aires asking prices are up only 1.4% since January and closing prices are down 0.4% over 12 months.
The bank's 25% payment-to-income cap means about ARS 3.9 million of monthly income at 6.7%; we would aim for 20%, which means about ARS 4.9 million.
After five years of payments you still owe about 94% of the loan in UVA at 6.7%, so the peso balance can look bigger than what you borrowed.
The strong peso made UVA debt dearer for dollar earners: a UVA balance grew roughly 18% in dollar terms from January to September 2026.
The last UVA crisis did not end in mass default (about 1.6% of borrowers in arrears in 2022), but it took payment freezes and relief to get there; do not count on another rescue.
Bank cushions such as Banco Nación's wage-index (CVS) cover or ICBC's term extension buy time, not cheaper debt.
A 30-year term only pays off if you stay long; a bigger deposit helps as much as a lower rate: borrowing 40% instead of 80% halves the payment to about ARS 524,000.
New state money (two FGS auctions of ARS 200 billion each, loans capped at UVA + 7.5%) gives anyone quoted 9.5% or more a reason to shop around, and Banco Ciudad's 6.5% offer ends on 31 December 2026.
Bottom line: with a rate at or below 7.5%, a payment near 20% of income, 25% or more down and a long stay, a UVA mortgage is worth it; with a double-digit rate, maximum borrowing or a short horizon, keep renting and save.


Are UVA mortgages still easy to get in 2026?
They are available, but far fewer people are taking them than in 2025.
Mortgage credit came back in 2024 after years when a bank loan was out of reach for most Argentines. The central bank (BCRA) counted about 43,700 new mortgage borrowers in 2025, almost all on UVA loans.
2026 cooled fast. Banks granted 14,237 mortgages from January to July 2026, against 25,160 a year earlier: down 43% (BCRA data compiled by Fundación Tejido Urbano).
Buenos Aires City shows where the problem is. The Colegio de Escribanos recorded 41,583 sale deeds from January to August 2026, only 2.3% fewer than a year earlier. Deeds with a mortgage fell 34%, to 6,170.
The fall is easing month by month: mortgage deeds were down 54.8% year on year in May, 37.1% in June, 31.2% in July and 20.8% in August.
So people are still buying homes. What got harder is making today's mortgage pricing work.
| Buenos Aires City market (2026) | Deeds | Change vs. year earlier | What we see |
|---|---|---|---|
| All sale deeds, January–August | 41,583 | -2.3% | Overall market holding up |
| Mortgage deeds, January–August | 6,170 | -34% | Credit is the weak spot |
| Mortgage deeds in May | 587 | -54.8% | Low point |
| Mortgage deeds in June | 765 | -37.1% | Still well below 2025 |
| Mortgage deeds in July | 959 | -31.2% | Decline easing |
| Mortgage deeds in August | 1,059 | -20.8% | 17.5% of all deeds that month |
What are you actually paying for with a UVA mortgage?
You borrow at a real interest rate and let inflation reprice the debt in pesos every month.
The loan is expressed in Unidades de Valor Adquisitivo (UVA). The UVA follows Argentina's CER inflation index, so the peso value of what you owe and of each payment rises as the UVA rises.
The bank charges its interest on top.
That is why "UVA + 6.7%" is nothing like a 6.7% fixed mortgage elsewhere. The 6.7% is roughly the real interest rate; inflation comes on top through the UVA.
Banks use this structure for a reason. A 20- or 30-year loan in plain pesos would need a huge starting rate to protect the lender from inflation. UVA keeps the first payment low and makes long loans possible.
You get a cheaper start in exchange for carrying the inflation risk later.
Has inflation fallen enough to make a UVA mortgage safer today?
Yes, much safer than in the crisis years, but monthly indexation is still big enough to hurt a tight budget.
INDEC measured 1.9% inflation in September 2026, 33.4% over 12 months and about 23.6% from January to September. Forecasters in the BCRA's September 2026 survey (REM) expect about 30% for 2026 as a whole.
That is far from the double-digit monthly rates of the recent shock.
The UVA itself shows what borrowers live with. It stood at ARS 2,165.66 on 22 October 2026, up from about ARS 2,018 at the start of July: about 7.3% in less than four months.
A 1.9% monthly pace is much easier for salaries to follow than 10% or 20% a month. But 1.9% every month still adds up to about 25% a year.
Today's UVA borrower faces a manageable inflation path, not a harmless one.
| Inflation measure | Latest reading | What it means for a UVA borrower |
|---|---|---|
| Monthly CPI, September 2026 | 1.9% | Payments rise slowly, but every month |
| 12 months to September 2026 | 33.4% | Existing payments still rise a lot in pesos |
| January–September 2026 | About 23.6% | Your balance in pesos rose about as much |
| REM forecast for 2026 (September survey) | About 30% | Forecasters expect a slow, not sudden, slowdown |
| UVA value, 22 October 2026 | ARS 2,165.66 | Up about 7.3% since early July |
 Buying in Argentina as a Foreigner
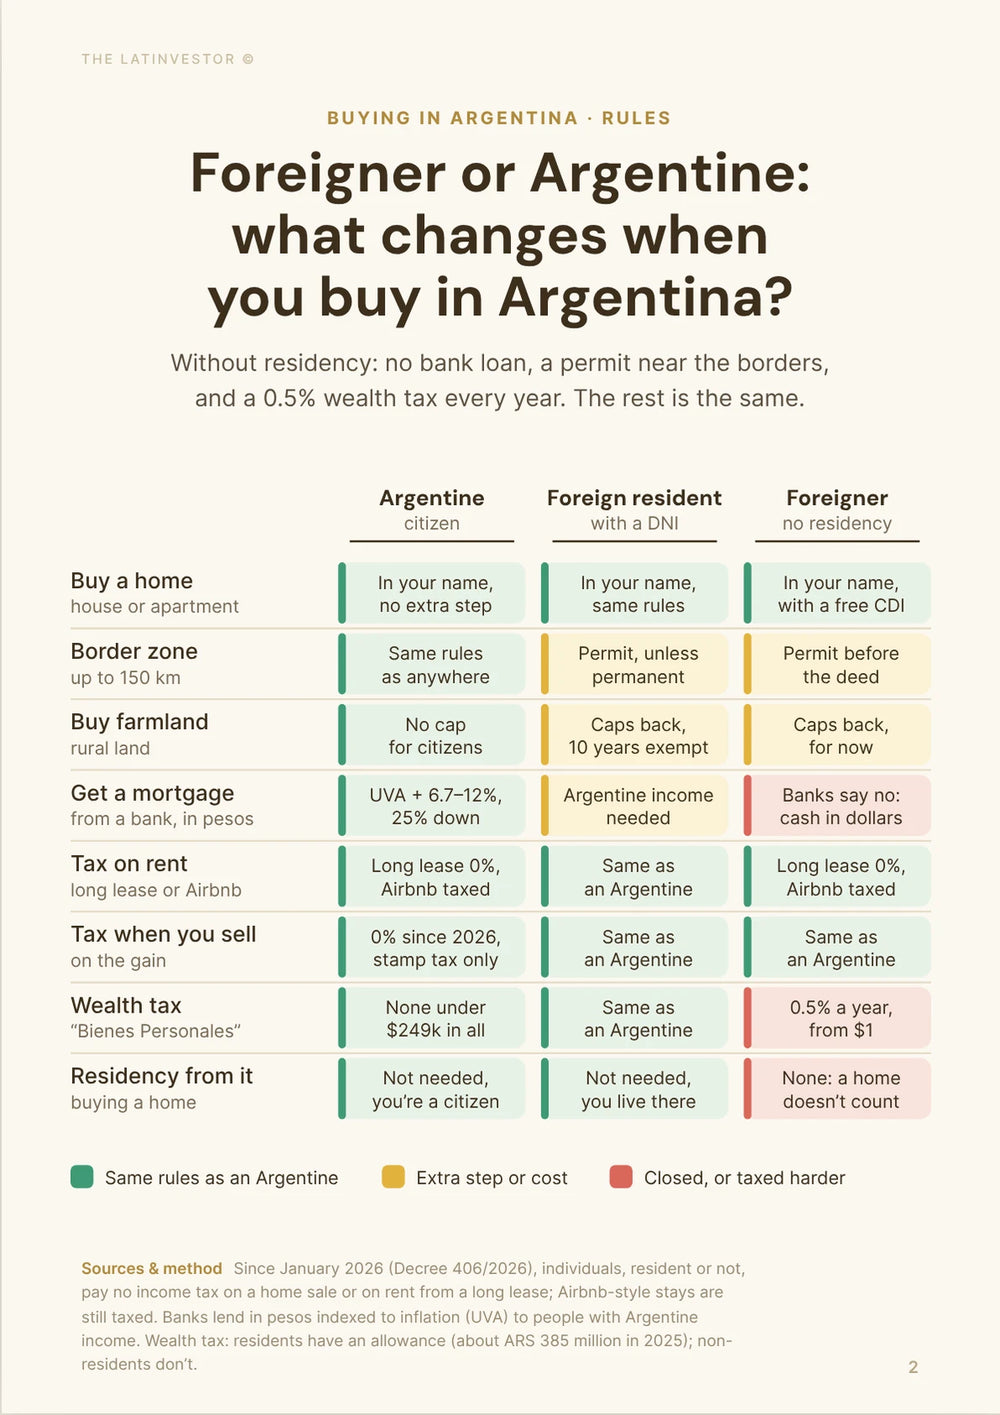
Are Argentine salaries keeping up with UVA payments?
On average yes, but the average hides the workers banks actually lend to.
INDEC's wage index was 35.7% higher in June 2026 than a year earlier. That headline is pulled up by informal wages, which rose 59.5%.
Registered private-sector wages rose only 29.6% and public-sector wages 30.1%, below the 33.4% annual inflation INDEC measured in September. These are the documented salaries banks use to approve a mortgage.
This is the most important personal test for a UVA borrower.
A household whose pay is updated with inflation every few months can absorb UVA well. Someone with one salary review a year has much less protection. For the self-employed it depends on how fast they can raise their prices.
Small gaps add up. If UVA rises 30% while your income rises 20%, a payment that took 20% of your income now takes about 21.7%. A few years of that turns a comfortable mortgage into a hard one, without any crisis.
Look at your own pay history over the last three years, not the national average.
How cheap are the best UVA mortgages right now?
The cheapest are genuinely interesting; above roughly 9% real interest they get hard to justify.
Banco Ciudad charges UVA + 6.5% on first homes in Buenos Aires City up to 80 m², an offer valid until 31 December 2026; its general line is 7.5%.
Banco Nación charges UVA + 6.7% to customers paid through the bank who buy a single home, and UVA + 12% otherwise. It lends up to 75% of the price over up to 30 years.
ICBC charged 6.9% to salary customers in September 2026. BBVA charges 7.5% with salary and insurance at the bank, 9.5% with salary only and 11.5% without.
These are not interchangeable offers. Going from 6.7% to 11.5% does much more than raise the first payment a bit: it changes how much interest you pay for decades and how slowly the debt falls.
| Bank / mortgage (October 2026 unless stated) | Rate over UVA | Maximum term | Main condition |
|---|---|---|---|
| Banco Ciudad, first home up to 80 m² | 6.5% | 25 years | Buenos Aires City; offer until 31 Dec 2026 |
| Banco Nación, single home | 6.7% | 30 years | Salary paid at Banco Nación; 75% max |
| ICBC, salary customer (September 2026) | 6.9% | 20 years | Salary deposited at ICBC |
| BBVA, salary plus insurance | 7.5% | 30 years | Salary and insurance at BBVA |
| Banco Ciudad, general line | 7.5% | 25 years | Standard UVA line |
| BBVA, salary only | 9.5% | 30 years | No insurance package |
| BBVA, no salary at the bank | 11.5% | 30 years | Standard offer |
| Banco Nación, other borrowers | 12% | 30 years | No salary at the bank or not a single home |
Does the difference between 7% and 10% really matter that much?
Yes. A few points of real interest change the first payment by hundreds of thousands of pesos and the total cost by a lot more.
Take a USD 131,000 one-bedroom in Buenos Aires (Zonaprop's 50 m² model apartment, September 2026) financed at 75%: a loan of about ARS 152 million (USD 98,250) over 30 years, repaid in equal real installments (French system).
At 6.7%, the first payment is about ARS 983,000 (USD 635). At 7.5% it is about ARS 1.06 million, at 9.5% about ARS 1.28 million and at 11.5% about ARS 1.51 million. These are pure installments, before insurance and fees.
Inflation will raise all of them in pesos, so the useful comparison is in constant UVA terms.
Over 30 years, payments at 6.7% add up to about 2.3 times the amount borrowed in real terms. At 9.5% it is about three times, at 11.5% about 3.6 times.
Expensive loans also shrink slowly. After five years, the 6.7% borrower still owes about 93.8% of the loan in UVA; at 11.5%, about 97.4%.
A three- or four-point gap on a 30-year UVA mortgage is huge.
| Rate over UVA | First payment on ARS 152m, 30 years | Total real payments | Loan left after 5 years |
|---|---|---|---|
| 6.5% | ARS 963k | 2.28× the loan | 93.6% |
| 6.7% | ARS 983k | 2.32× the loan | 93.8% |
| 7.5% | ARS 1.06m | 2.52× the loan | 94.6% |
| 9.5% | ARS 1.28m | 3.03× the loan | 96.2% |
| 11.5% | ARS 1.51m | 3.57× the loan | 97.4% |
| 12% | ARS 1.57m | 3.70× the loan | 97.7% |
 70+pages
Is buying with a UVA mortgage cheaper than renting in Buenos Aires now?
At the best rates, the monthly payment is close to rent. The cash you need upfront is the real difference.
Zonaprop puts the average asking rent for a 50 m² one-bedroom (two rooms) in Buenos Aires City at about ARS 898,000 a month (USD 580) in September 2026. That is up 28.7% over 12 months, less than the 33.4% inflation over the same period.
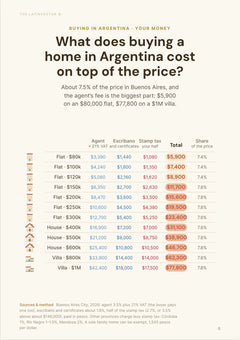
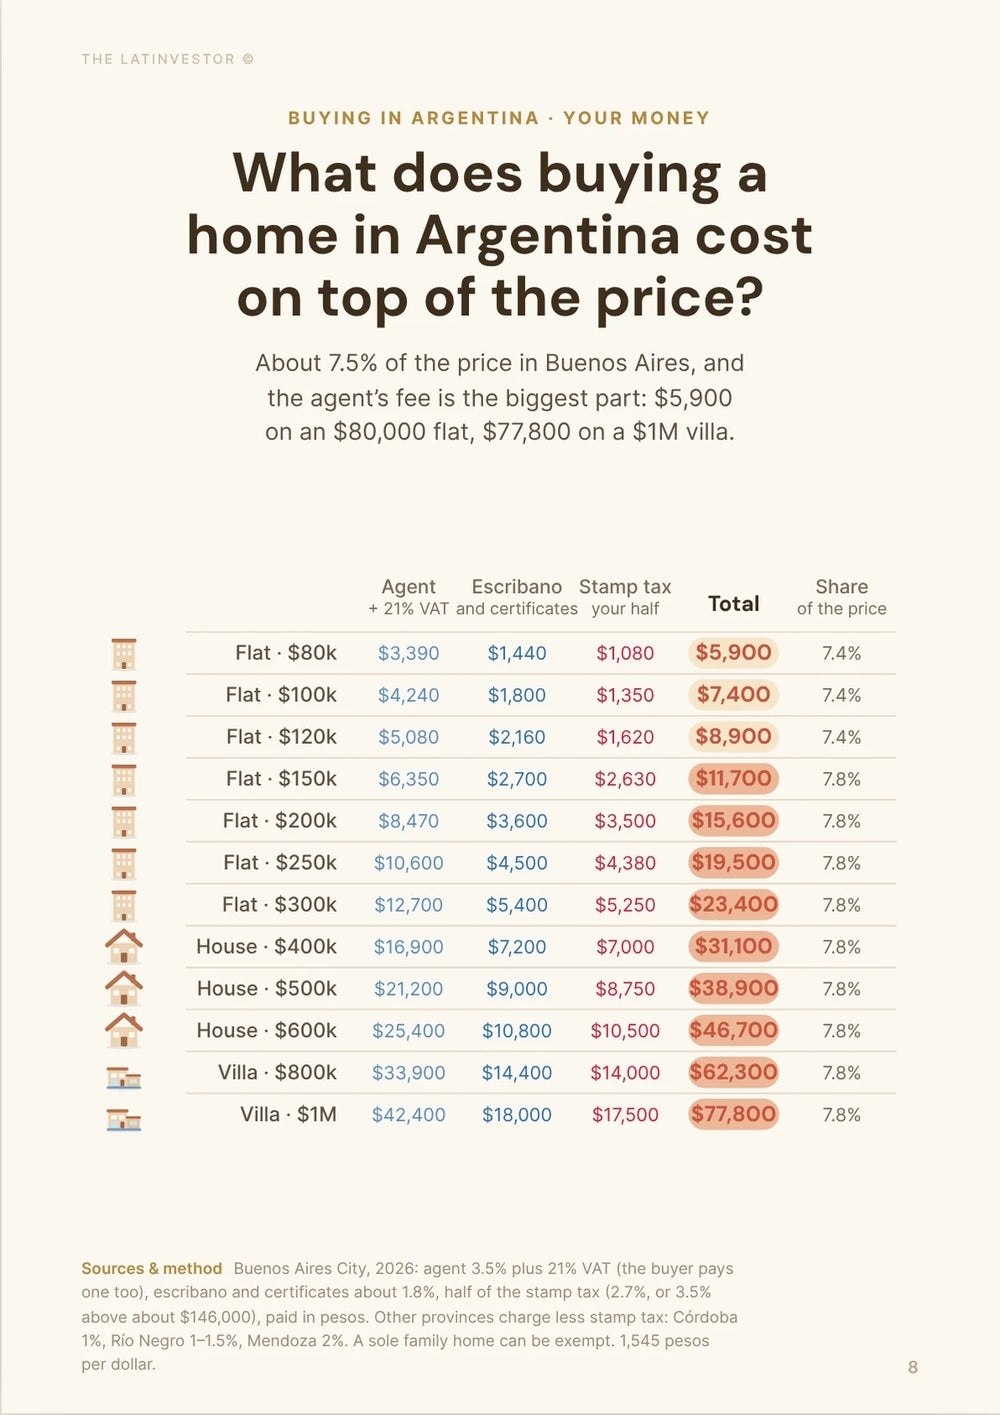
The same apartment costs about USD 131,000 to buy. At 75% financing, you borrow about ARS 152 million and need USD 32,750 for the deposit, plus about 6% to 9% of the price in buying costs in the City (USD 7,900 to USD 11,800).
At UVA + 6.7% over 30 years, the first payment is about ARS 983,000; at 7.5%, about ARS 1.06 million.
That is only about ARS 85,000 to ARS 167,000 a month above the average rent, before the costs only an owner pays (property tax, repairs, extraordinary building charges).
Renting still lets you keep more than USD 40,000 in your pocket and move whenever you want.
But the old picture, where a mortgage payment was miles above rent, no longer holds for the best offers.
| 50 m² one-bedroom, Buenos Aires City | Approximate amount |
|---|---|
| Asking price (Zonaprop, September 2026) | USD 131,000 |
| 25% deposit | USD 32,750 |
| Buying costs (6% to 9%) | USD 7,900 to 11,800 |
| Mortgage at 75% | About ARS 152m (USD 98,250) |
| Average asking rent | About ARS 898k a month |
| First payment at UVA + 6.7% | About ARS 983k |
| First payment at UVA + 7.5% | About ARS 1.06m |
Are Buenos Aires home prices rising fast enough to make the mortgage worth it?
No. Prices are too flat to rescue an expensive loan, so the purchase has to make sense as a home first.
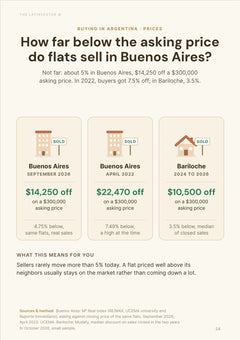
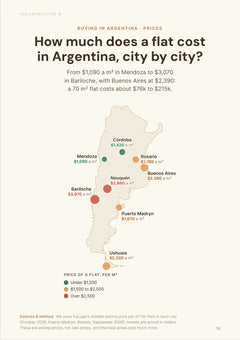
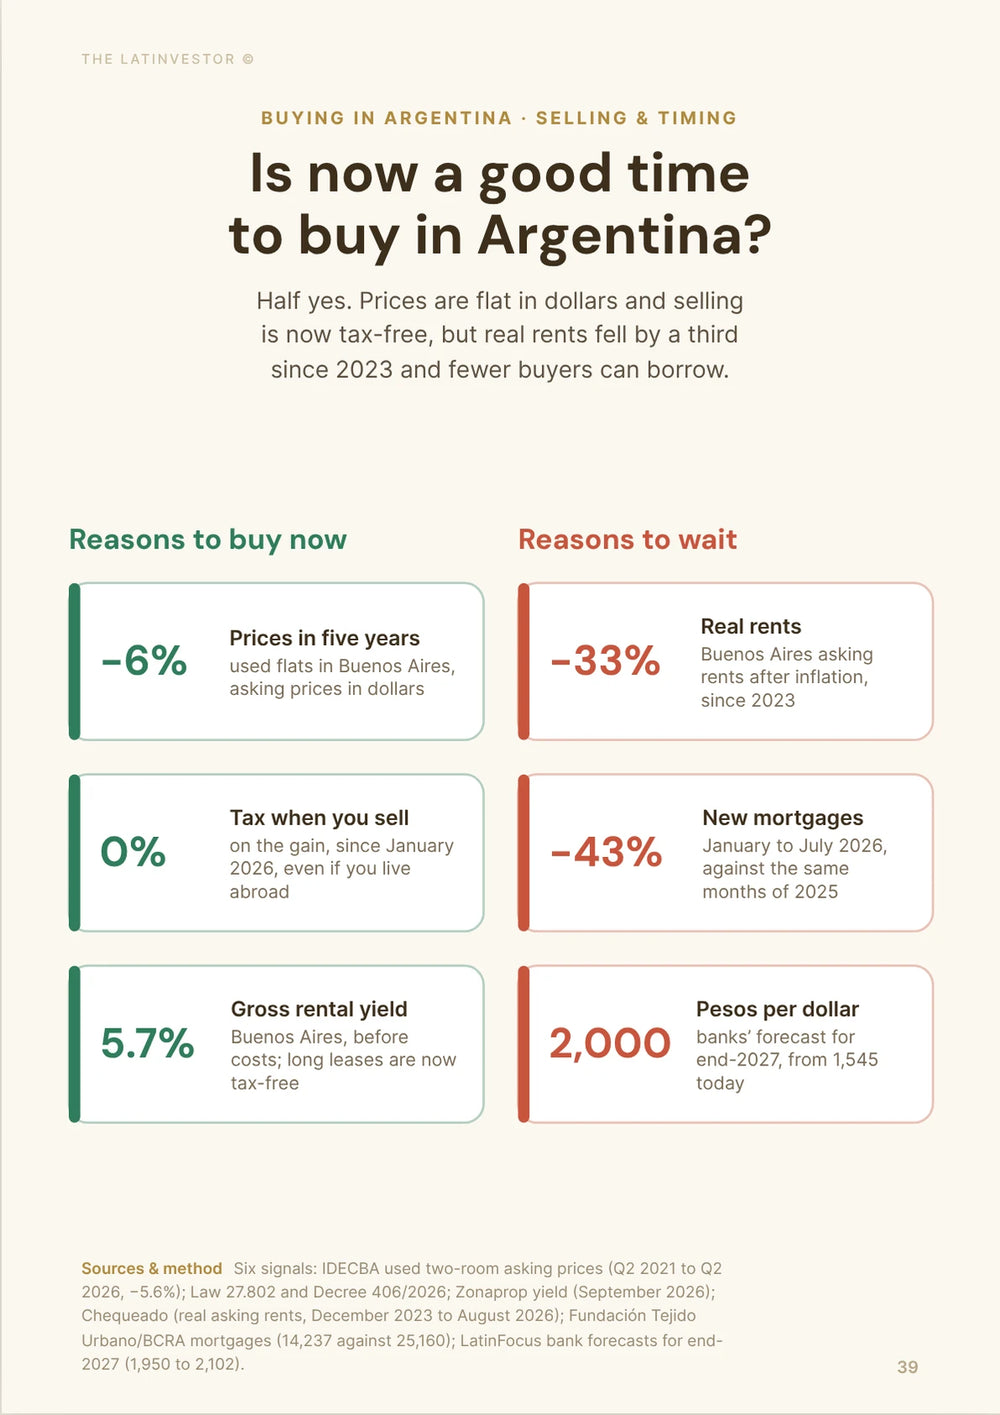
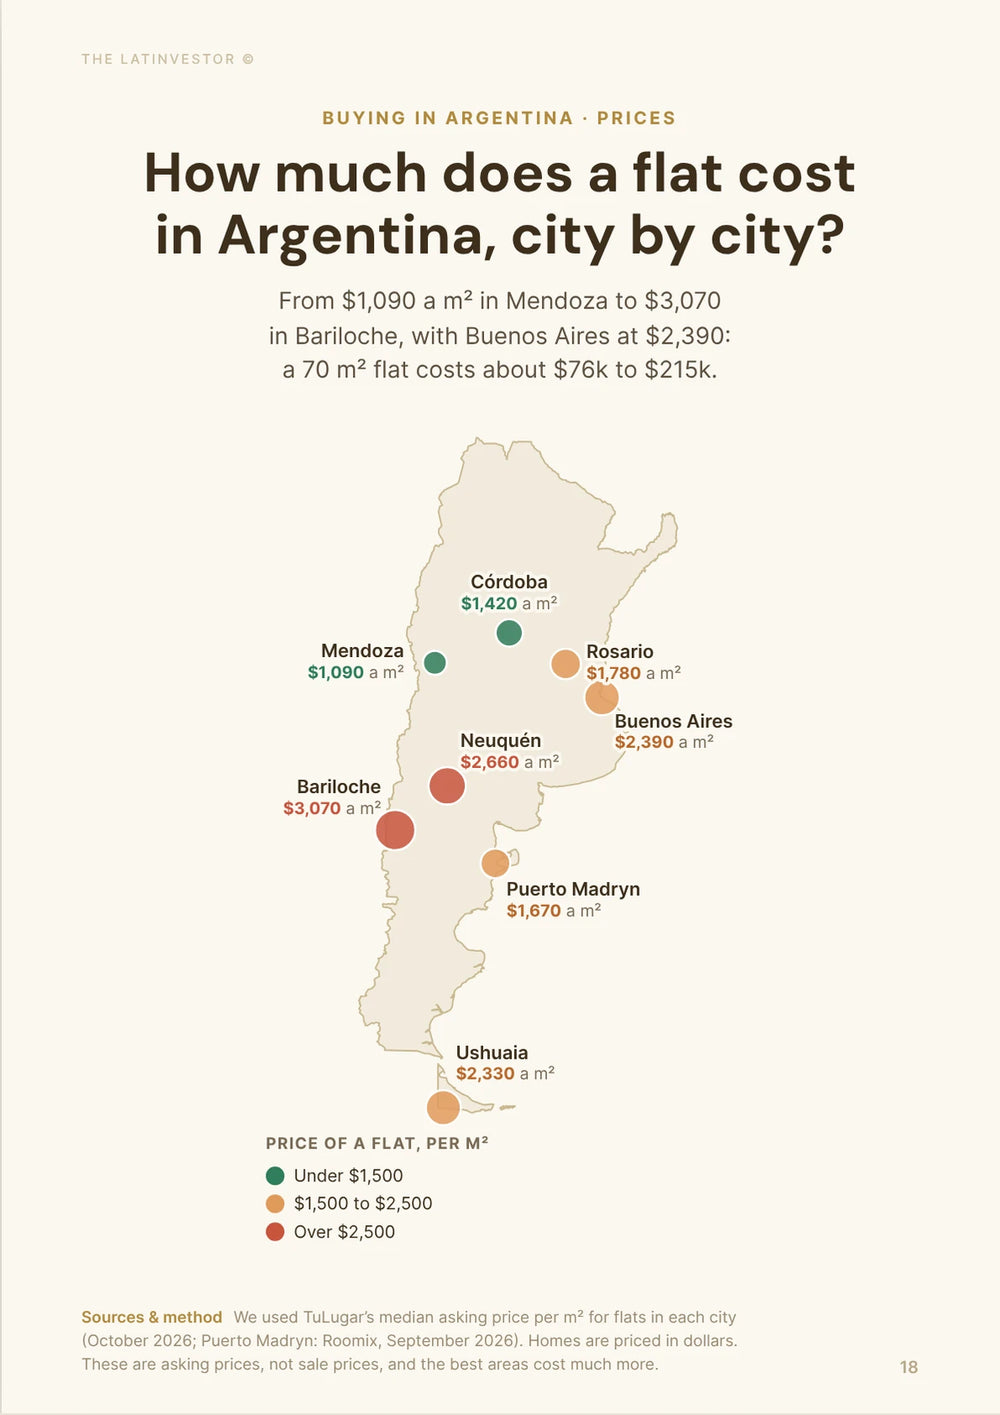
Zonaprop put the average Buenos Aires City asking price at USD 2,484/m² in September 2026, up only 1.4% since January and still 11.3% below its record.
Closing prices tell the same story: about USD 2,097/m² in September 2026, 0.4% lower than a year earlier (M² Real survey by RE/MAX, UCEMA and Reporte Inmobiliario).
The average deed in August 2026 was worth about USD 119,270, up 10.3% in pesos but down 2.7% in dollars on a year earlier (Colegio de Escribanos).
Sales volumes are decent, yet prices have barely moved in dollars.
For someone buying a home to live in, that is not bad news: you are not buying at the top of a bubble.
For an investor borrowing at UVA + 9.5% or 11.5%, flat dollar prices do nothing to offset that real interest cost.
How much income do you really need for a UVA mortgage?
A lot, and borrowing right up to the bank's limit leaves no room for Argentina to surprise you.
ICBC and Banco Ciudad cap the first payment at 25% of income, a common threshold across banks.
On the ARS 152 million loan, the ARS 983,000 first payment at 6.7% needs about ARS 3.93 million of monthly income (USD 2,540) to pass a 25% test.
At 9.5% you need about ARS 5.12 million. At 11.5%, about ARS 6.03 million.
For scale, the average wage of stable registered workers (RIPTE) was about ARS 1.98 million in August 2026, so even the cheapest loan needs two solid salaries.
Passing the bank's test does not mean the loan is comfortable. Start at 25%, and a short spell of UVA outpacing your salary pushes you toward 30%.
We would feel much better starting near 20%, especially with one main income.
| Rate on ARS 152m, 30 years | First payment | Income needed at 25% | Income needed at 20% |
|---|---|---|---|
| 6.5% | ARS 963k | ARS 3.85m | ARS 4.81m |
| 6.7% | ARS 983k | ARS 3.93m | ARS 4.91m |
| 7.5% | ARS 1.06m | ARS 4.26m | ARS 5.32m |
| 9.5% | ARS 1.28m | ARS 5.12m | ARS 6.40m |
| 11.5% | ARS 1.51m | ARS 6.03m | ARS 7.54m |
 70+pages
This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
Can your UVA mortgage debt rise even while you keep paying?
Yes. The peso balance can rise for years while you pay every installment on time.
It is built into the product.
Say you borrow 100,000 UVA. Each payment lowers the number of UVA you owe. But if each UVA costs 30% more in pesos over the year, that adjustment easily outweighs the small slice of principal repaid in the early years of a 30-year loan.
The effect is strongest at the start, when principal falls very slowly.
As shown above, a 30-year borrower at 6.7% still owes about 94% of the loan in UVA after five years. At 11.5%, even more.
It feels absurd: five years of punctual payments, and a peso balance much bigger than the peso amount you borrowed.
Comparing those two peso amounts without adjusting for inflation is misleading, but the shock when you read the statement is real.
Can a UVA mortgage also become more expensive in dollars?
Yes, and it happened in 2026: when inflation runs faster than the dollar, UVA debt grows in dollar terms.
This gets overlooked because Argentine property is priced in dollars, while UVA debt follows Argentine prices.
From January to September 2026, prices rose about 23.6% while the wholesale dollar rose only about 4.9%, from about ARS 1,455 to ARS 1,526. A UVA balance therefore grew roughly 18% in dollar terms in nine months, before any repayment.
It can go the other way. A sharp devaluation quickly shrinks the dollar value of a UVA balance. Forecasters in the BCRA survey expect about ARS 1,614 per dollar by end-2026, a small move next to inflation.
So the debt and the home do not match: the apartment is valued in dollars, the mortgage follows inflation and most borrowers earn pesos.
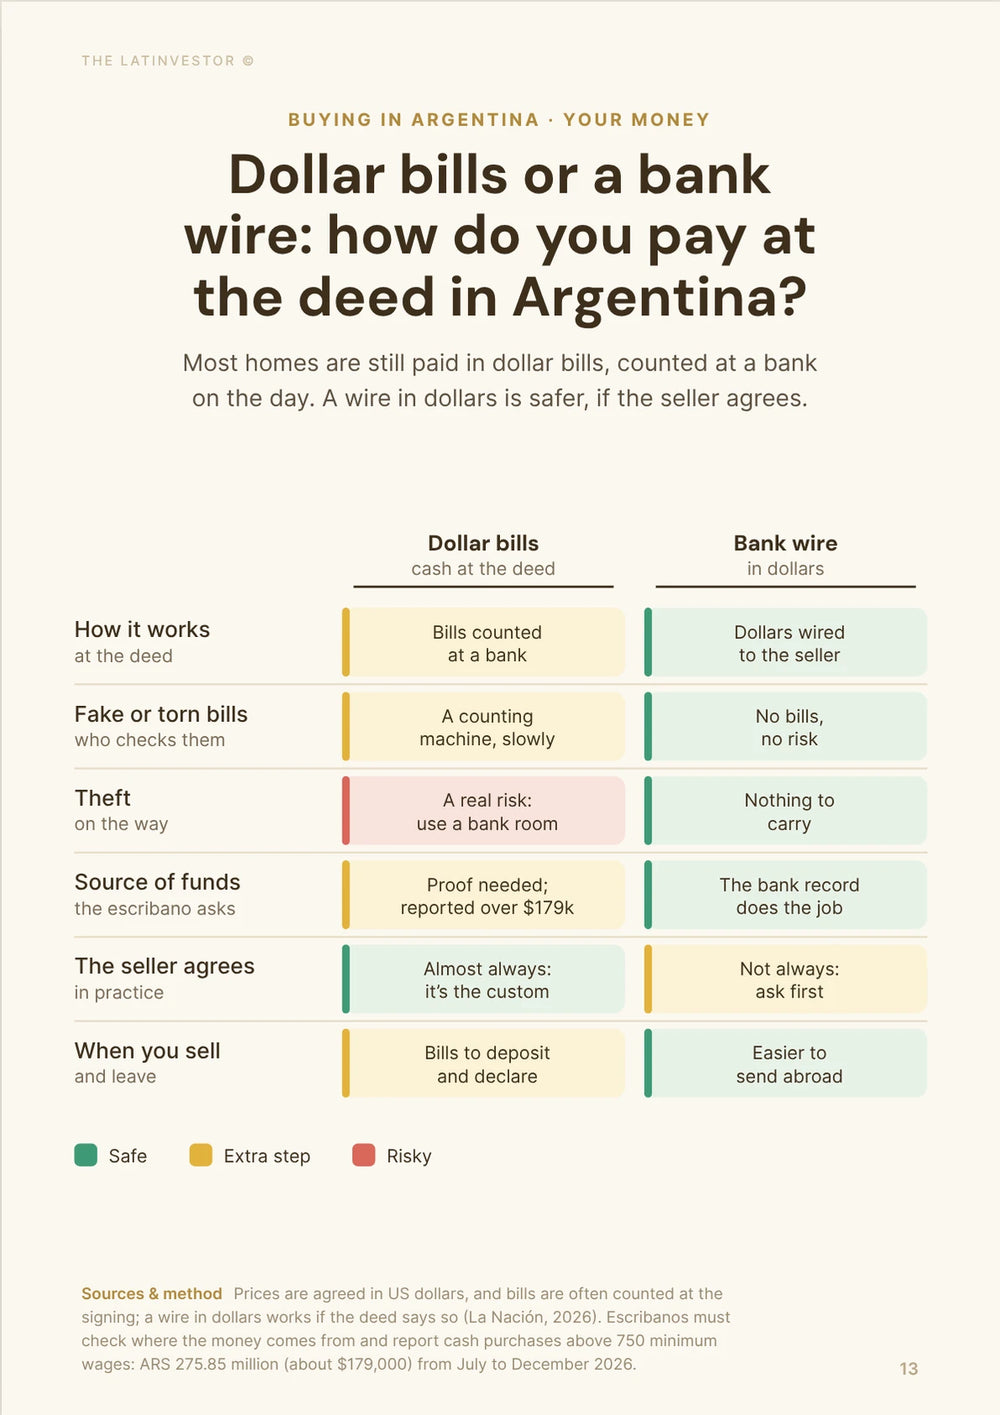
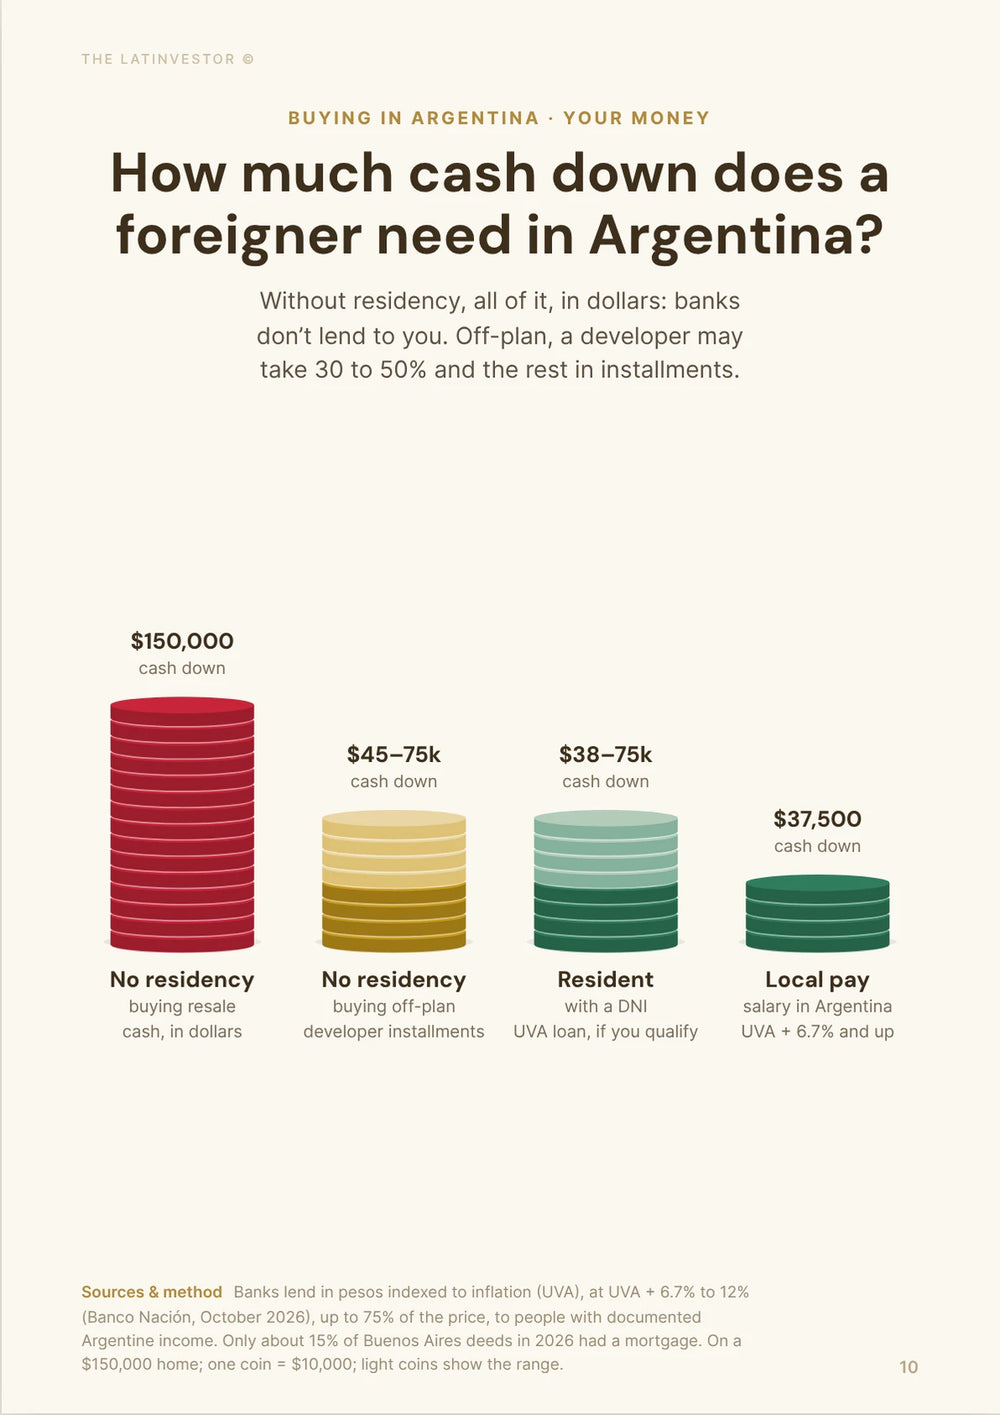
Anyone planning to sell within a few years, or earning in dollars or euros, should take this mismatch seriously. A non-resident with only foreign income has no confirmed access to UVA loans anyway.
Did the original UVA mortgage crisis prove these loans are a trap?
No. The first UVA cycle showed the loans can become very uncomfortable in a crisis, but mass default did not happen.
The product got a brutal test soon after it took off in 2017: recession, devaluations, faster inflation and then the pandemic.
Balances soared in pesos.
Yet BCRA data showed UVA mortgage delinquency of only about 0.3% in early 2019. In 2022, only about 1.6% of the roughly 95,000 families with UVA mortgages had any payment trouble.
That is far better than most people remember.
There is a catch. Borrowers did not go through the shock under their original contracts. The government froze installments during the pandemic (Decree 319/2020), then added convergence schemes and help for vulnerable households.
The record says two things: Argentine owners fought hard to keep paying, and the state stepped in when the gap between indexed debt and income became politically unbearable.
The low default rate is reassuring. Planning around another government rescue would be a mistake.
What happens to a UVA mortgage if inflation jumps again?
It gets dangerous when your salary trails UVA for several years in a row.
Take a household whose payment starts at 20% of income.
If UVA and salary both rise 50%, the ratio stays at 20%. The peso amounts look bigger, but the burden does not change.
If UVA rises 50% and income only 30%, the ratio jumps to about 23.1%.
Another year like that takes it to about 26.6%.
That is how UVA stress usually builds. No hyperinflation, default or job loss needed: a steady gap between CER and your pay does the damage.
So stress-test your income, not one inflation forecast. Someone whose pay has always caught up quickly can live with much more UVA volatility than someone whose salary catches up six or twelve months late.
 70+pages
Do UVA mortgage protections really help if salaries fall behind?
Some do soften a salary shock, but the cost usually comes back later.
Banco Nación sells an optional cover, for an extra fee, that limits payment rises to the wage index (CVS) when UVA runs well ahead of salaries, under certain conditions.
ICBC's published conditions take another route: the loan term can be extended when the UVA payment gets far enough above what it would be if it had followed wages.
The upside is simple: you get time.
That matters in a temporary shock. A family that can afford ARS 1 million a month but suddenly faces ARS 1.4 million needs relief now, even if the debt stays.
The trade-off is simple too. A longer loan means more years in debt, and paid cover makes the mortgage dearer from day one.
These options are worth having, especially if you borrow a lot. Treat them as shock absorbers, not as a reason to borrow more.
Should you take a 30-year UVA mortgage or a shorter one?
Thirty years keeps today's payment low; a shorter loan actually gets rid of the debt.
The trade-off is sharp with UVA because you already pay a positive real rate.
On the ARS 152 million loan at 6.7%, the first payment is about ARS 983,000 over 30 years and about ARS 1.15 million over 20 years. That difference can decide whether you qualify. Banco Nación and BBVA lend over up to 30 years, Banco Ciudad up to 25.
The price is slow repayment.
In the first five years of a 30-year loan you pay off only about 6% of the principal in UVA. A buyer who moves after three or four years pays a lot of interest and builds little equity through the loan.
Someone planning to stay 15 or 20 years has a much better case for the long term.
If your income rises later, prepaying shortens the loan. Banco Nación, for example, allows partial or full early repayment, with no prepayment fee once the contract's minimum period has passed.
Use 30 years to get monthly breathing room, not to buy the most expensive home the bank allows.
Is it smarter to wait for UVA mortgage rates to fall?
If the only loan you can get is around UVA + 10% or more, waiting makes sense. If you are offered 6.5% to 7.5%, there is little reason to gamble on a cut.
Waiting for a better rate can pay off a lot.
On the ARS 152 million example, moving from 9.5% to 7.5% cuts the first payment by about ARS 216,000 a month. Over the whole loan, total real payments fall from about three times the loan to about 2.5 times.
Prices are not running away either: Buenos Aires asking prices are up only 1.4% since January.
But waiting has a cost. City rents are up 28.7% over 12 months, and nobody can promise today's best offers will last: Banco Ciudad's 6.5% rate is only valid until 31 December 2026.
Rates do not only go down. Banco Nación's best rate was 4.5% at the 2024 relaunch; it is 6.7% now. A La Nación review found the average advertised rate climbed to about 11.1% in the second half of 2025 before falling back.
With a mediocre offer, patience pays. Turning down a good 6.5% to 7.5% offer in the hope of something cheaper is a weak bet.
Does a UVA mortgage make more sense with a bigger down payment?
Yes. UVA is far easier to live with when it fills a small gap than when it covers the maximum the bank allows.
Take two households buying the same USD 131,000 apartment at UVA + 6.7% over 30 years.
One borrows 80%, about ARS 162 million, and starts with a payment of about ARS 1.05 million. The other borrows 40%, about ARS 81 million, and pays about ARS 524,000.
Both follow the same inflation index.
Only the first is exposed from day one to a few bad pay rises, a job change or a big unexpected bill.
A smaller loan also makes slow early repayment matter less: even if the balance barely falls for years, it is a small share of the home's value.
BBVA and ICBC lend up to 80% on a permanent home, Banco Nación and Banco Ciudad 75%.
That maximum tells you what the bank accepts, not what you should take.
If you already have 40% to 60% of the price saved, UVA is much more attractive: it closes a specific gap without putting your whole household budget behind an inflation-linked loan.
 70+pages
Who should get a UVA mortgage now?
A stable household buying a home to live in for a long time, with a real rate at or below about 7.5% and a payment that is comfortable from day one.
The strongest case: you buy your main home and plan to stay many years. You can pay the deposit and buying costs without emptying every savings account. Your income has followed inflation well. The first payment takes closer to 15% or 20% of income than 25%. And you have enough cash to get through a job loss or a bad year for pay rises.
The rate matters most.
At 6.5% to 6.9%, there is a serious case for UVA today. At 7.5% it can still work, especially if the alternative is paying a high Buenos Aires rent for years.
The case gets stronger when the loan covers only 40% to 60% of the price.
Then UVA does a useful job: it lets you buy earlier without borrowing the maximum.
Who should stay away from a UVA mortgage?
Anyone who needs wages, inflation and their job to behave perfectly for the payment to stay affordable.
Borrowing at the bank's maximum 25% payment-to-income ratio with almost no savings left after the deposit is the clearest warning sign.
So is accepting UVA + 11.5% or 12% just because the bank says yes. At those rates you pay far more real interest and barely reduce the debt in the early years.
UVA also looks bad if you are likely to move within three or four years. Buying costs of 6% to 9%, slow repayment and flat dollar prices can wipe out the benefit of owning.
It is even harder to justify as an investment bought on credit. Buenos Aires closing prices fell 0.4% in dollars over the last 12 months, while some loans charge double-digit real interest, and the City's gross rental yield is about 5.7% (Zonaprop, September 2026).
A borrower stretching to buy a home is taking a housing risk.
An investor borrowing at UVA + 10% or more and hoping a Buenos Aires apartment will rise enough to cover it is making a much tougher bet.
Will the FGS auctions make UVA mortgages cheaper?
For anyone quoted 9.5% or more, maybe. In September 2026 the government started lending up to ARS 2 trillion from the pension reserve fund (FGS) to banks for home loans. The first auction placed ARS 200 billion with 13 banks on 7 September; the second, on 6 October, placed another ARS 200 billion with 12 banks.
Loans funded this way must cost at most UVA + 7.5%, run at least 15 years and stay under 150,000 UVA, about ARS 325 million or USD 210,000 at the October 2026 UVA value. Banks have about 90 days to lend the money. The second round also widened eligibility to any single permanent home, not just first homes.
The money is limited: ARS 400 billion is about USD 258 million, or roughly 2,500 loans at the 2026 average of about USD 100,600. Compare that with 25,160 mortgages in January–July 2025.
What to do: if your bank quotes 9.5% to 12%, ask whether it won FGS money and whether you qualify for that line. If you are already offered 6.5% to 6.7%, the FGS cap changes nothing for you.
What should you check before signing a UVA mortgage in late 2026?
Get at least three written quotes. Banco Nación's 6.7% and BBVA's 7.5% depend on moving your salary (and, at BBVA, buying its insurance); compare the full annual cost (CFT) with insurance included, not just the rate.
Watch the calendar. Banco Ciudad's 6.5% on first homes up to 80 m² is only valid until 31 December 2026, and approval, appraisal and the deed can take weeks.
Size the loan yourself. Aim for a first payment near 20% of household income, not the bank's 25%, and keep about six months of payments in cash after the deposit and the 6% to 9% buying costs. Ask about the CVS cover, the term-extension clause and the prepayment fee before you sign.
If you earn in dollars or euros, test your budget with the payment 20% higher in dollar terms: that is roughly what 2026 did to UVA balances. A non-resident with only foreign income should plan to pay cash.
 70+pages
So, is a UVA mortgage worth it now in Argentina?
Yes, selectively. The best UVA mortgages are worth it now; the expensive ones are still easy to turn down.
Conditions are better than in years. Monthly inflation was 1.9% in September 2026, forecasters expect about 30% for the year, and several banks lend at UVA + 6.5% to 7.5%, with the FGS money capped at 7.5%.
At those rates, the numbers can work.
A 50 m² Buenos Aires one-bedroom costs about USD 131,000 and rents for about ARS 898,000 a month. Financing 75% at 6.7% over 30 years starts at about ARS 983,000. For a household that has the deposit and plans to stay, the gap between renting and owning is small enough to take seriously.
We would draw the line once rates reach 9.5% or more. The higher payment is only the start: lifetime real interest jumps, the debt falls very slowly, and you stay exposed to every year in which wages trail inflation, as registered wages did in the year to June 2026.
The housing data fit that caution. Buenos Aires City purchases barely fell (-2.3% to August), while mortgage deeds fell 34%. Buyers did not disappear. Credit is the weak point.
So the answer depends less on whether "UVA mortgages" are good or bad than on the loan in front of you.
At UVA + 6.5% to 7.5%, with income that follows inflation, 25% or more down, spare savings and a long stay, we would seriously consider buying.
At UVA + 10% or more, we would usually keep renting, build a bigger deposit or wait for a better offer.
And if you need maximum financing and the first payment already reaches 25% of your income, a cheap headline rate would not convince us either.
Our methodology
This article estimates whether a UVA mortgage is worth taking in Argentina in late 2026: how the loan works, current inflation and wages, bank rates, payments and income needed, renting versus buying in Buenos Aires City, prices, deposit size, term, the strong peso, past stress and the new FGS-funded loans.
Loan volumes come from the BCRA (new borrowers in 2025) and Fundación Tejido Urbano's compilation of BCRA data (January–July 2026); Buenos Aires City deeds and deed values from the Colegio de Escribanos (January–August 2026). Rates, terms and financing limits come from the banks' own pages (Banco Nación, Banco Ciudad, BBVA, October 2026; ICBC, September 2026) and the 2025 average rate from La Nación. Prices and rents come from Zonaprop's September 2026 index and the M² Real closing-price survey; wages from INDEC's wage index (June 2026) and the RIPTE series (August 2026). Payments are our own French-amortization calculation on a 75% loan on Zonaprop's USD 131,000 model one-bedroom, first month, before insurance and fees.
Inflation comes from INDEC (September 2026) and forecasts from the BCRA's September 2026 REM survey; the UVA value from the BCRA; the FGS programme from the Ministry of Economy and auction results reported in September and October 2026; past delinquency from BCRA banking and financial stability reports; the pandemic freeze from Decree 319/2020. Buying costs (6% to 9% in Buenos Aires City) and foreign-borrower rules are those used across our Argentina articles.
We checked these figures in October 2026. Peso amounts are converted at about ARS 1,550 per US dollar (official and MEP rates were within 1% of each other on 22 October 2026, the blue rate about ARS 1,570), and euro amounts at about ARS 1,740 per euro.
Where we had no direct figure, we say so: ICBC's 6.9% rate and 20-year term date from September 2026 and should be confirmed with the bank; the dollar growth of a UVA balance is our estimate from inflation and the wholesale dollar, not a bank figure; the number of loans the FGS money can fund is our estimate from the average loan size; and the income-gap scenarios are illustrations, not forecasts.
Key sources used for this analysis include Banco Nación's UVA mortgage conditions, Banco Ciudad's Primera Vivienda programme, ICBC Argentina's mortgage terms, BBVA Argentina's mortgage conditions, the Ministry of Economy on the FGS mortgage programme, Infobae on the second FGS auction, CPAU on Tejido Urbano's 2026 mortgage data, the BCRA on new mortgage borrowers in 2025, the BCRA's main variables (UVA and CER), BCRA Communication A6069, the BCRA's September 2026 REM survey, Infobae on INDEC's September 2026 inflation, INDEC's consumer price index, INDEC's wage index for June 2026, the RIPTE wage series, Infobae on the dollar in October 2026, the Colegio de Escribanos' August 2026 deed data, its July 2026 data, its June 2026 data, its May 2026 data, Revista Mercado on Zonaprop's September 2026 index, Infobae on Zonaprop's September 2026 rents, Reporte Inmobiliario's M² Real closing prices, La Nación's September 2025 mortgage-rate review, the BCRA's May 2019 banking report, the BCRA's second-half 2022 Financial Stability Report and Decree 319/2020 on pandemic-era mortgage protections.