

Summary
Yes, for a cash buyer who can hold five years or more: Buenos Aires apartments ask USD 2,484 per m² (Zonaprop, September 2026), still 11.3% below their old peak, but the easy crisis bargains are gone.
The market has recovered in sales more than in price. Buenos Aires signed 41,583 sale deeds from January to August 2026, only 2.3% fewer than in a very strong 2025, while asking prices are up just 1.4% since January.
Real deals are flat. Used apartments closed at USD 2,097 per m² in September 2026, 0.4% less than a year earlier, so nobody is forcing you to rush.
The 2023 bottom is behind us. Buenos Aires is roughly 11% above it and Córdoba 31.5% above its May 2023 low, yet Córdoba (USD 1,474 per m²) is still about 41% cheaper than the capital.
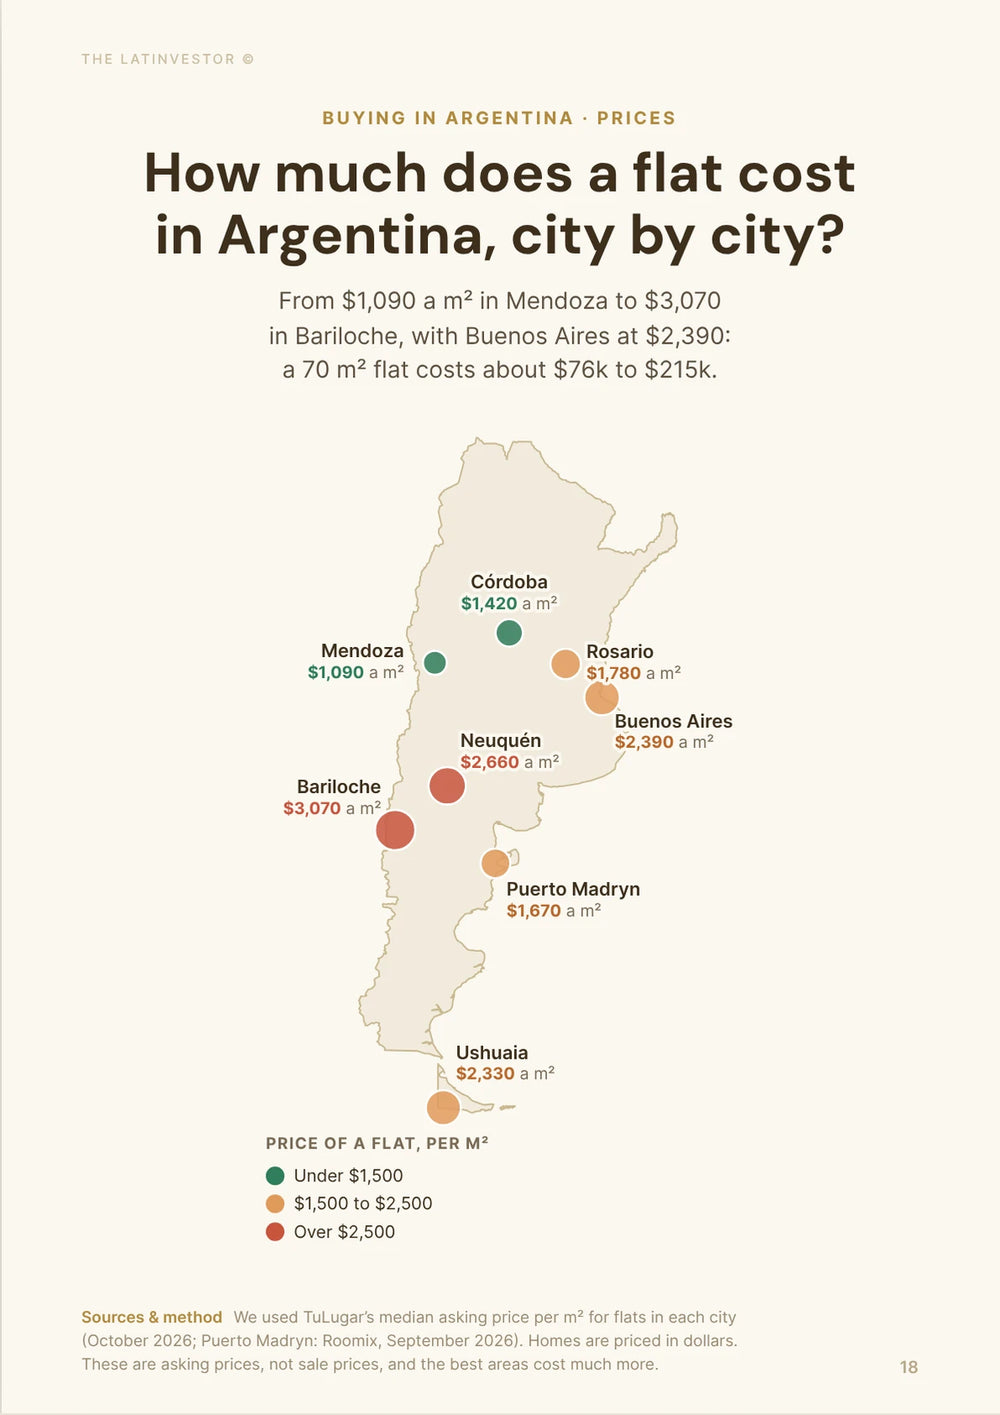
Buenos Aires stays the safest bet because it is liquid: about 110,000 properties were listed for sale in August 2026, and a 50 m² one-bedroom lists around USD 131,000.
Inflation is far lower than in the crisis (1.9% in September 2026) but still 33.4% over twelve months, and the IMF cut its 2026 growth forecast from 3.5% to 2.1% in October.
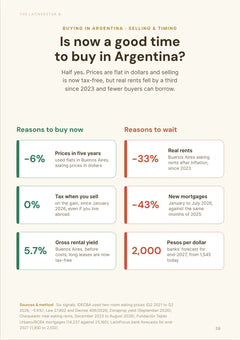
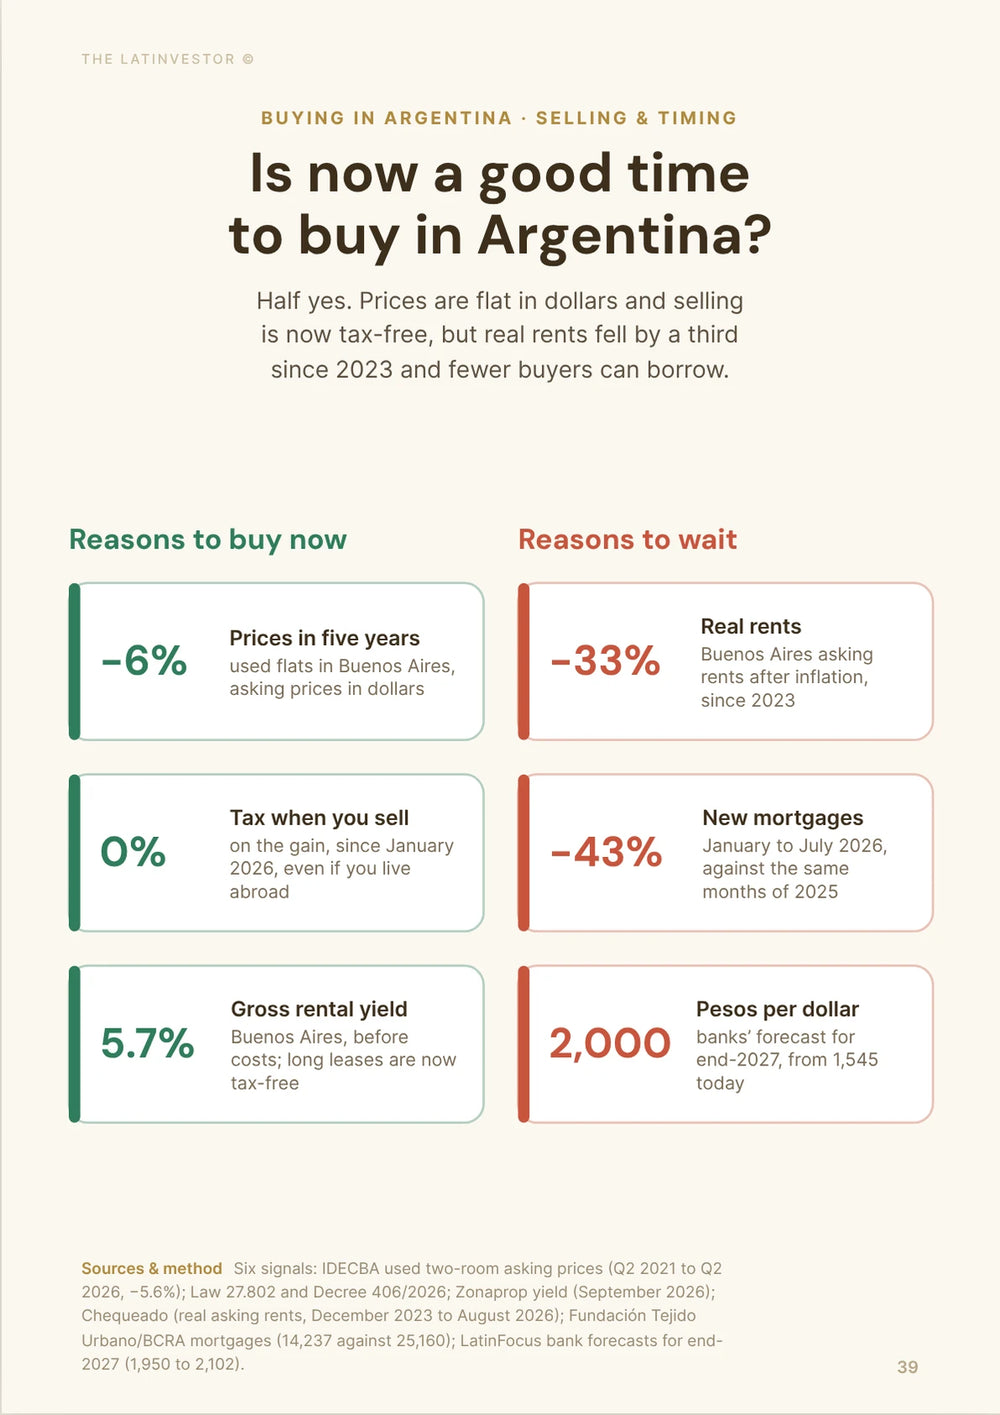
Mortgages are not pushing prices up. New loans fell 43% from January to July 2026, and only 14.8% of Buenos Aires deeds used one; Banco Nación charges UVA + 6.7% at best.
That makes this a cash buyer's market. A 5.70% gross yield does not pay for a loan at 6.7% to 12% over inflation, and foreigners with only foreign income have no confirmed access to UVA mortgages anyway.
Rental deregulation brought supply back, not pricing power: rental listings are 3.6 times their 2023 low, and a two-room flat asks ARS 898,154 a month, up 28.7% in a year against 33.4% inflation.
Older apartments are often better value: new two-room units ask USD 3,215 per m² against USD 2,343 for used ones, and building costs in dollars rose 21% in a year.
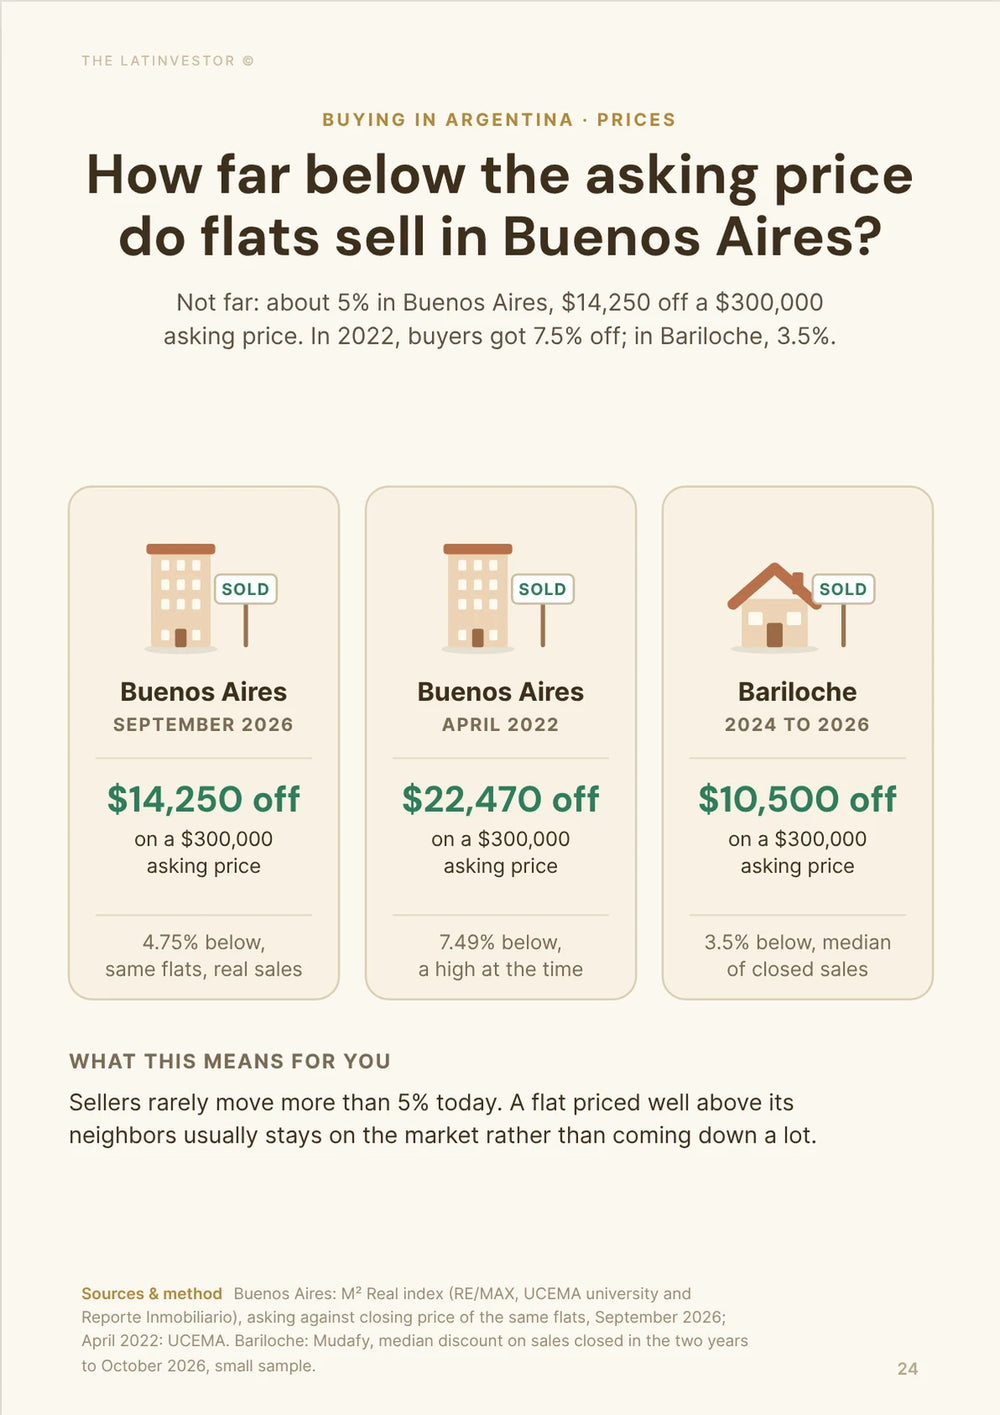
You can negotiate: buyers closed about 4.75% below the last asking price in September 2026, and the stock for sale was 3.4% bigger than a year earlier.
Upside needs cheaper credit: the state pension fund lent banks ARS 400 billion for mortgages in September and October 2026. The main downside is a new peso shock that cuts local buying power, so buy only what still makes sense if Argentina improves more slowly.
The peso is the twist of 2026: the dollar rose only about 4.9% this year while prices rose 23.6%, so do not wait for a devaluation to make Argentina cheap; forecasters see only about ARS 1,614 per dollar at the end of 2026.
The 2026 tax changes help sellers: individuals, foreigners included, pay no income tax on resale gains since 1 January 2026, but buying still costs about 6–9% on top of the price in Buenos Aires.
Bottom line: buy a good, well-located apartment at a negotiated dollar price, without heavy debt, and hold it. Quick flips, rent-covers-the-loan plans and waiting for another 2023-style crash are the weak setups.


How far has Argentina's property market bounced back?
A fair way from its lows, but buyers in Buenos Aires still pay well below the old peak.
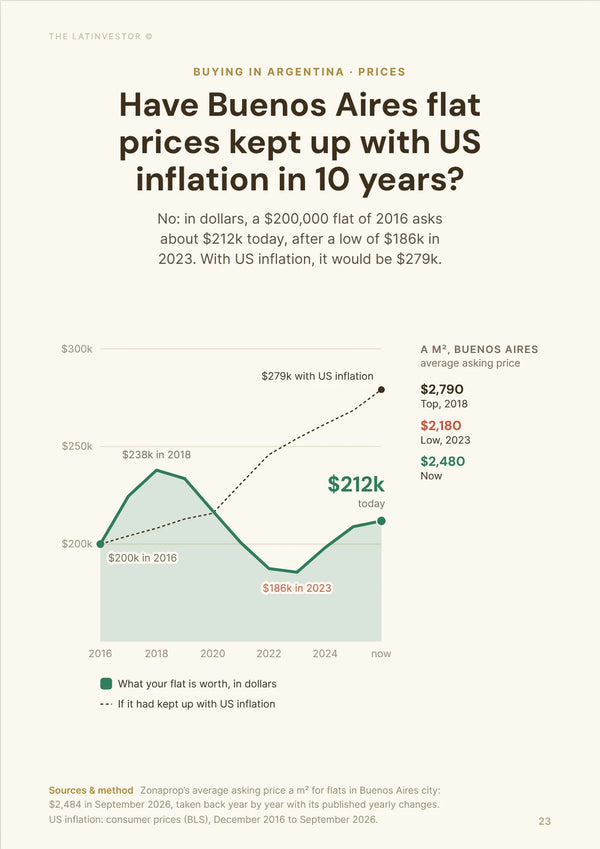
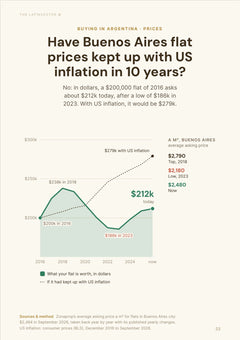
Zonaprop's September 2026 index puts the average Buenos Aires apartment at USD 2,484 per m² asking. Global Property Guide measured gains of 6.6% in 2024 and 3.2% in 2025, and Zonaprop shows another 1.4% since January 2026: roughly 11% above the 2023 low in total.
The recovery started when political uncertainty eased, mortgages came back and capital controls were lifted. It has only won back part of the earlier fall.
Buenos Aires is still 11.3% below the historical high of Zonaprop's series, which puts that peak at about USD 2,800 per m². Prices would need to rise about 13% to get back there.
So buyers sit in between. The crisis discount has partly gone, but the market has not returned to its old dollar prices either.
| Buenos Aires apartment market | Price | Change | What we see |
|---|---|---|---|
| Previous peak (Zonaprop) | ~USD 2,800/m² | — | High point of the last cycle |
| Since the 2023 low | — | About +11% | Clear but modest recovery |
| Asking price, Sept 2026 | USD 2,484/m² | +1.4% since January | Barely moving |
| Closing price, Sept 2026 (M² Real) | USD 2,097/m² | -0.4% YoY | Real deals are flat |
| Gap versus historical peak | — | -11.3% | Part of the discount remains |
Are Argentina property prices still rising fast?
No. Buenos Aires asking prices still creep up, but "flat in dollars" describes them better.
Zonaprop's September 2026 reading shows +0.3% in the month and +1.4% since January. September's rise was the biggest of the year, which says how quiet 2026 has been. In 2025, Zonaprop measured 5.4%.
What people actually pay is flatter still. The M² Real index (RE/MAX, Universidad del CEMA and Reporte Inmobiliario) puts closed sales of used Buenos Aires apartments at USD 2,097 per m² in September 2026, against USD 2,105 a year earlier: down 0.4%.
For someone deciding now, that removes the urgency. You are entering a working market without chasing a rising index.
Demand recovered much faster than prices. For a buyer, that is a better setup than a market where both are accelerating.
Are people actually buying property in Buenos Aires right now?
Yes. Sales are running at levels that would have looked exceptional a few years ago, even though they no longer grow.
The Colegio de Escribanos de la Ciudad de Buenos Aires recorded 6,055 sale deeds in August 2026, 4.9% fewer than in August 2025 but still among the five best Augusts of the past 28 years. July had 6,051, down 9%.
The bigger picture matters more: 41,583 deeds from January to August 2026, only 2.3% fewer than in the same months of 2025, which was one of the busiest years in a long time.
The explosive growth of the rebound is over, but buyers have clearly come back. Monthly sales spent most of 2026 between 5,000 and 6,000 deeds, far from the weak years of the last decade.
The average deed in August 2026 was worth about USD 119,270 (Colegio de Escribanos, at the official rate). Sales held up without a jump in prices.
| Buenos Aires sale deeds | 2026 | Change | What it suggests |
|---|---|---|---|
| July 2026 | 6,051 | -9.0% YoY | Sales have cooled |
| August 2026 | 6,055 | -4.9% YoY | Still among the five best Augusts in 28 years |
| January–August 2026 | 41,583 | -2.3% YoY | High level, no more growth |
| Average deed, August 2026 | ~USD 119,270 | — | Values are holding |
 Argentina Property Market
This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
Is property in Argentina still cheap today?
Cheap compared with its own past, yes. Cheap compared with 2023, no: the bargain phase has passed in several markets.
Buenos Aires is the clearest case. At USD 2,484 per m², the city is 11.3% below its old high. Anyone who bought near the 2023 bottom paid roughly 10% less than today.
Córdoba moved faster. Zonaprop put it at USD 1,474 per m² in March 2026, 31.5% above its May 2023 low. Rosario was at USD 1,841 in May 2026, up 9% in a year.
Greater Buenos Aires gives another comparison. GBA South asked about USD 1,673 per m² in September 2026, while GBA North, at USD 2,426, is close to the capital.
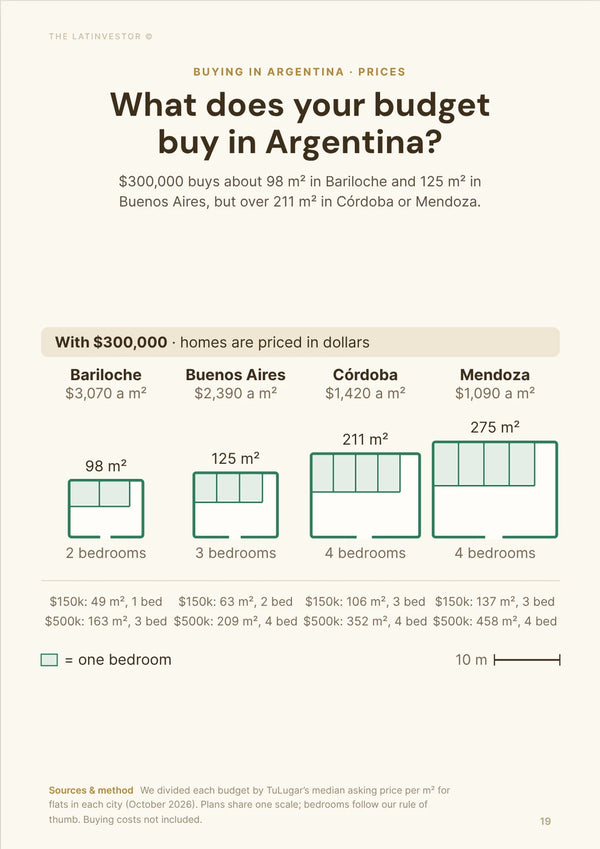
So there is no single "Argentina price". A USD 150,000 budget buys very different amounts of space in Palermo, Córdoba or the southern suburbs.
The "cheap" argument still works against old dollar highs. It does not work if "cheap" means buying near the bottom.
Is Buenos Aires still the safest property bet in Argentina?
Yes, if you care about resale, rental demand and having real data to price a deal.
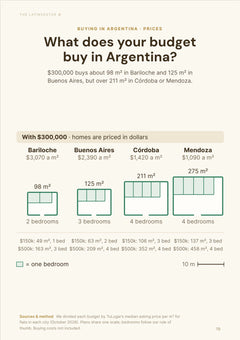
At Zonaprop's September 2026 reference prices, a 40 m² studio lists around USD 110,000, a 50 m² one-bedroom around USD 131,000 and a 70 m² two-bedroom around USD 180,000.
Córdoba is about 41% cheaper per m², so you get much more space for the money outside the capital. Southern Greater Buenos Aires is about a third cheaper.
The trade-off is liquidity. Buenos Aires has far more apartments, tenants, agents and comparable sales: about 110,000 properties were listed for sale in the city in August 2026 (Monitor Inmobiliario).
That depth matters the day you sell. A cheaper home in a thin market can end up costing more if finding the next buyer takes months.
| Market (Zonaprop) | Apartment asking price | Versus Buenos Aires City | Main attraction |
|---|---|---|---|
| Buenos Aires City | USD 2,484/m² (Sept 2026) | Highest of these markets | Liquidity and rental depth |
| GBA North | USD 2,426/m² (Sept 2026) | About 2% below | Affluent suburban demand |
| GBA South | USD 1,673/m² (Sept 2026) | About 33% below | Lower entry price |
| Córdoba | USD 1,474/m² (Mar 2026) | About 41% below | Much more space per dollar |
Has Argentina's inflation problem improved enough to make buying property safer?
Yes. Planning a long-term purchase is much easier than during the inflation shock, but inflation is still high enough to sit in every calculation.
INDEC measured 1.9% for September 2026 and 33.4% over twelve months. In late 2023, annual inflation was above 200%.
The outlook got a bit worse recently. In October 2026 the IMF cut its 2026 growth forecast for Argentina from 3.5% to 2.1% and raised its average 2026 inflation forecast to 32.5%. It expects 3.5% growth and about 21% inflation in 2027.
Lower inflation helps property in several ways: rents are easier to price, incomes erode more slowly, banks can lend longer and buyers can estimate their costs.
Still, Argentina is not a 2% inflation country. Around 2% a month is very high by any international standard, and the slowdown in inflation has become gradual.
Compared with the conditions that froze the market a few years ago, though, the change is huge.
 70+pages
Is the peso still a big risk when buying property in Argentina?
Yes. Currency risk is still the main reason Argentine property deserves a discount, even though buying dollars and closing a deal has become much easier.
Homes are priced in US dollars, while salaries, many rents and most running costs are paid in pesos. That mismatch puts the exchange rate at the center of the market.
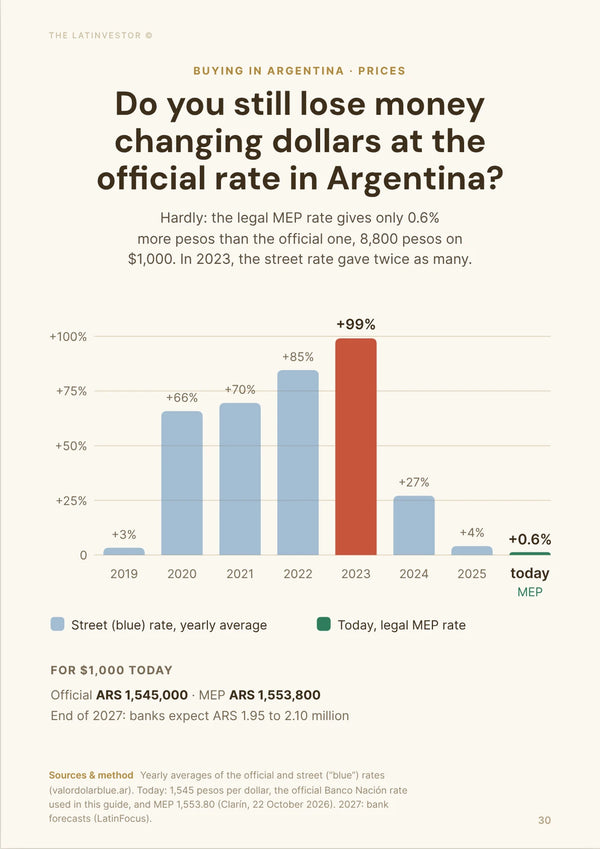
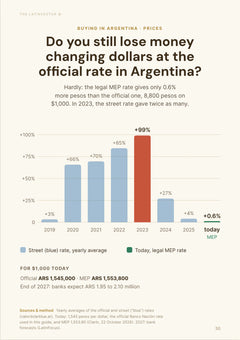
The old friction is mostly gone. Since April 2025, individuals no longer face the USD 200 monthly limit on buying dollars from a bank account, and in late October 2026 the official, MEP and blue rates were less than 2% apart, around ARS 1,550.
The deeper risk remains. A sharp devaluation cuts local salaries in dollars, shrinks the pool of buyers for dollar-priced homes and lowers your rental return once pesos are converted back.
If you arrive with dollars, that risk is easier to absorb. A household earning only in pesos can see affordability change very fast.
Are mortgages about to send Argentina property prices much higher?
No. Mortgages came back, but the credit boom lost steam in 2026.
The return of UVA mortgages was one of the big changes after 2024: the central bank counts about 43,700 new mortgage borrowers in 2025, after years with almost none.
2026 went the other way. Fundación Tejido Urbano counts 14,237 new mortgages nationwide from January to July 2026, against 25,160 a year earlier: 43% fewer.
In Buenos Aires City, 6,170 deeds used a mortgage from January to August 2026, about 34% fewer than a year earlier, or 14.8% of all deeds. August was a bit better, with 1,059 mortgage deeds (17.5% of sales), still 20.8% below August 2025.
Loans are not cheap. Banco Nación, the biggest lender, charges UVA + 6.7% to eligible salary clients buying a single home and UVA + 12% otherwise. Banco Ciudad offers UVA + 6.5% for a first home up to 80 m² and 7.5% in general; BBVA asks 7.5% to 11.5% over UVA.
Credit can still become a big price driver later. Today, buyers are not being pushed into the market by cheap loans.
| Mortgage indicator | Latest reading | Change | What we see |
|---|---|---|---|
| New mortgages, Argentina, Jan–Jul 2026 | 14,237 | -43% YoY | Credit has slowed sharply |
| CABA mortgage deeds, Jan–Aug 2026 | 6,170 | About -34% YoY | Only 14.8% of sales |
| CABA mortgage deeds, August 2026 | 1,059 | -20.8% YoY | Small pickup in share |
| Banco Nación rate | UVA + 6.7% to 12% | — | Best rate only for eligible salary clients |
| Banco Ciudad and BBVA rates | UVA + 6.5% to 11.5% | Wide spread | Cheap credit is far from universal |
Does buying Argentina property with cash make much more sense today?
Yes. Argentina works much better for a dollar cash buyer than for someone who needs a big UVA mortgage.
Cash avoids the main weakness of local loans: UVA debt rises with inflation. The rate on top may look reasonable, but the balance itself is indexed. With the peso strong in 2026, a UVA balance rose about 18% in dollars from January to September.
That can work for a household whose salary keeps up with inflation. It gets hard when wages lag, jobs weaken or inflation picks up again.
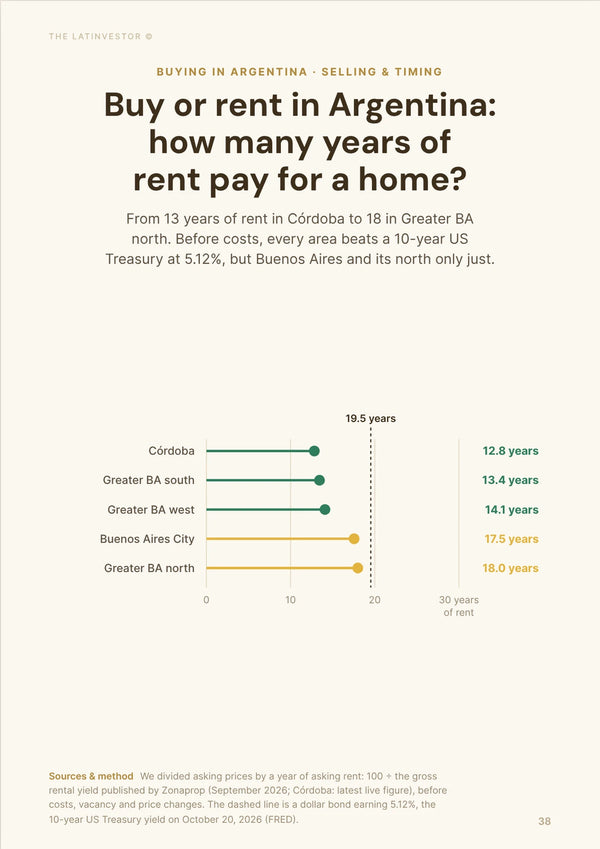
For an investment property it makes even less sense. Gross rental yields in Buenos Aires are 5.70% (Zonaprop, September 2026). A loan at 6.7% to 12% over inflation does not pay for itself from rent.
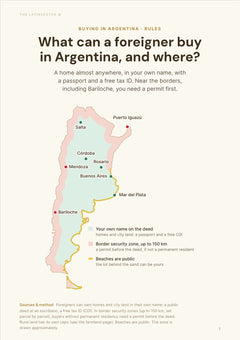
Foreigners can buy ordinary urban property once they have a tax ID (CDI, free, up to 30 business days for non-residents). Rural land is different: on 9 October 2026 the Supreme Court provisionally brought back the limits on foreign ownership. Non-residents with only foreign income have no confirmed access to UVA mortgages, so cash is the realistic route anyway.
With cash, a few years of average rent are bearable while you wait for value to rise. With heavy debt, that wait gets expensive.
 70+pages
Are Buenos Aires rental yields actually good now?
Decent, but 5.70% gross does not make an average apartment a great investment.
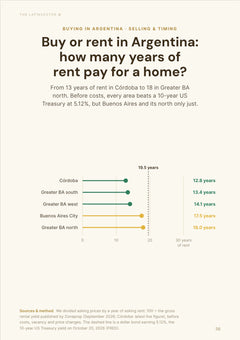
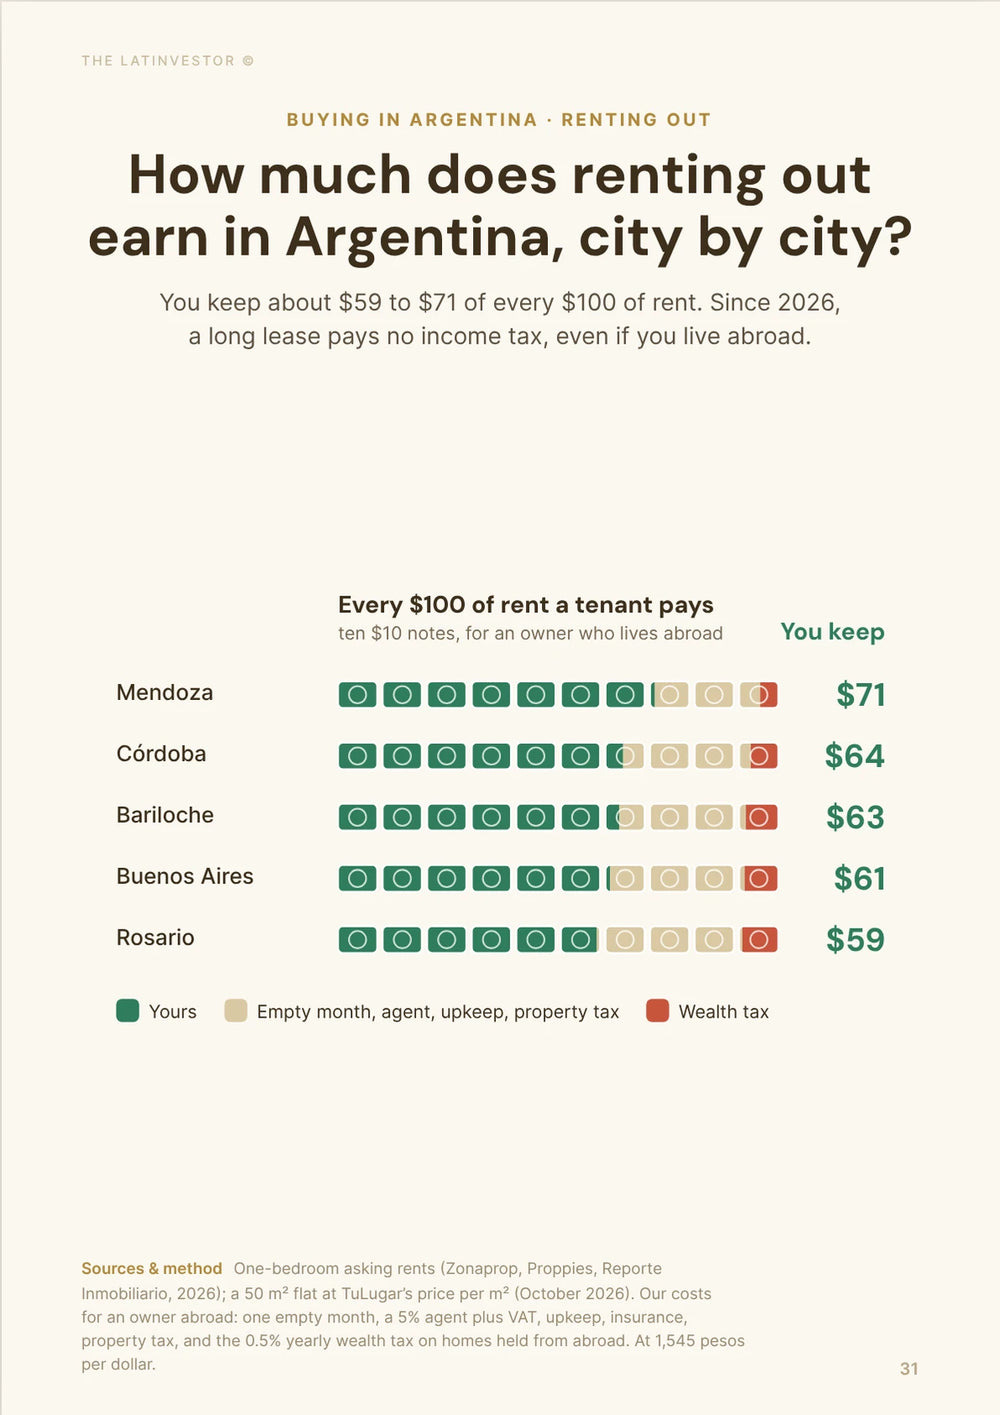
Zonaprop puts the average gross yield on a Buenos Aires apartment at 5.70% in September 2026. At that rate, gross rent repays the price in about 17.5 years. In 2020 the same index was at 2.3%.
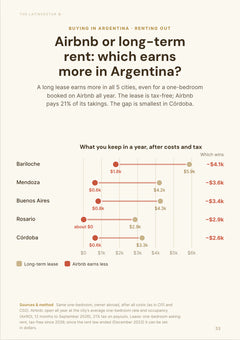
Net is lower. Empty months, building fees paid by the owner, repairs, management and taxes all come out of that 5.70%. A landlord living abroad should also plan on 21% of gross rent withheld for income tax until an Argentine tax adviser confirms the 2026 exemption applies: that alone takes 5.70% to about 4.5%.
The barrio matters a lot. Cheaper areas such as Lugano and La Boca give higher percentage yields because prices are low compared with rents. Expensive ones like Puerto Madero give less.
So we would not buy a Buenos Aires apartment for a 5% to 6% headline yield alone. It gets interesting when that rent comes with a good purchase price and room for the price to rise.
Has Argentina's rental deregulation made landlords richer?
It made renting out much easier, but the flood of apartments back on the market also made landlords compete.
Since DNU 70/2023 ended the 2020 rental law, owners can agree the length, index and currency of a lease freely. Many came back: La Nación reported on 19 October 2026 that rental listings in Buenos Aires were 3.6 times their February 2023 low. A bid in Congress to overturn the decree failed for lack of quorum on 15 October 2026.
That supply shows in prices. Zonaprop puts the average asking rent for a 50 m² two-room flat in Buenos Aires at ARS 898,154 a month in September 2026 (USD 580). That is up 28.7% in twelve months and 20.8% since January.
Inflation ran faster: 33.4% over twelve months and about 23.6% from January to September. In real terms, asking rents fell about 2% this year.
Landlords have a much better market than under the old rules. They do not have unlimited pricing power.
| Buenos Aires rental market | Latest reading | Comparison | What it means |
|---|---|---|---|
| Gross rental yield (Sept 2026) | 5.70% | About 17.5 years payback | Fair income, before costs and tax |
| Two-room asking rent (Sept 2026) | ARS 898,154/month | +28.7% YoY | Rents still rise in pesos |
| Inflation over the same 12 months | 33.4% | Faster than rents | Rents fell in real terms |
| Rental listings (Oct 2026) | 3.6× the Feb 2023 low | Supply is back | Tenants have more choice |
Is an older apartment better value than a new one in Argentina right now?
Often, yes. Building costs have risen far faster than resale prices.
You miss this if you only watch price indices.
Zonaprop's January 2026 report already had Buenos Aires building costs in dollars about 104% above late 2023 and 29% above their 2012–2025 average. By September 2026 they had added another 18.5% since January (21% over twelve months), while apartment asking prices rose 1.4%.
The gap shows in listings: new two-room apartments ask USD 3,215 per m², used ones USD 2,343 (IDECBA, Q2 2026), about 37% more for new.
Developers therefore face a much higher replacement cost, and cheap new apartments are hard to deliver. A good existing apartment benefits from that. The sweet spot is an older unit in a strong location that needs little work.
A very dated unit loses that edge fast, because labor, materials, kitchens, bathrooms and wiring all cost more. Paying USD 20,000 less than a renovated comparable means little if the apartment needs USD 30,000 of work.
 70+pages
Can buyers still negotiate hard in Buenos Aires?
Yes. There is enough choice to walk away from an overpriced apartment.
About 110,000 properties were listed for sale in Buenos Aires City in August 2026 (Monitor Inmobiliario), most of them apartments.
The stock keeps growing: Zonaprop counted 3.4% more properties for sale in June 2026 than a year earlier (La Nación).
That balances the strong sales figures. Thousands of homes change hands every month, but the stock has not been cleared out.
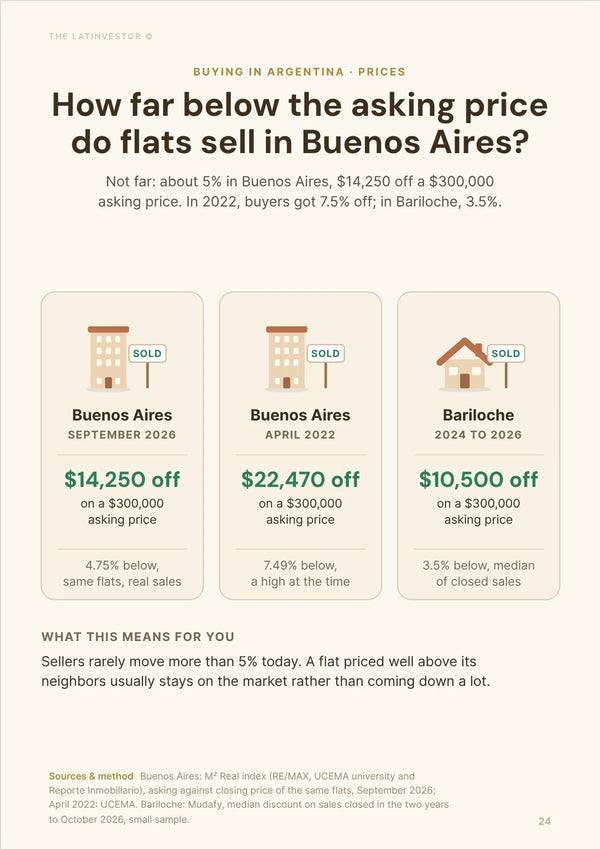
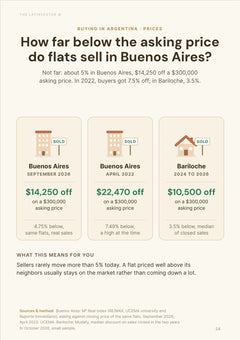
How much to ask for: in September 2026, buyers closed about 4.75% below the last asking price on the same homes (M² Real). Aim for about 5% off a fairly priced listing, more on one that has been online for months.
Time on market, condition, building fees, inheritance issues and renovation needs matter far more than a 1% move in the city index. Negotiation counts more than guessing whether the market moves 2% up or down next year.
What could push Argentina property prices much higher from here?
Cheaper mortgages, stronger real incomes and a few more years of stability.
Credit is the biggest lever, because far more households want to own than can pay cash.
The 2026 drop in mortgage deeds shows how sensitive demand is to loan terms. The government is trying to restart it: the state pension fund (FGS) lent banks ARS 200 billion for mortgages on 7 September 2026 and another ARS 200 billion on 6 October 2026, for loans capped at UVA + 7.5%.
Growth would help too. The IMF expects 2.1% in 2026 and 3.5% in 2027, along with slowly falling inflation.
Construction adds pressure. New homes are no longer cheap to build in dollars. If demand picks up while building costs stay high, well-located existing apartments become harder to replace at today's prices.
Those three forces have not lined up yet. If they do, Buenos Aires could close much of the 11.3% gap to its old peak.
What could make buying Argentina property now turn out badly?
A new currency and inflation shock would hurt buyers far more than a small dip in demand.
Argentines have seen this before. When the peso falls sharply, salaries lose value in dollars, fewer households can buy dollar-priced homes, banks pull back and sales dry up even if sellers do not cut asking prices right away.
Forecasters do expect the peso to weaken, just not dramatically: the central bank's survey (REM, September 2026) sees about ARS 1,614 per dollar at the end of 2026, and banks in the October LatinFocus panel see about ARS 1,950 to 2,100 by the end of 2027.
Politics is part of the same story. A government that keeps fiscal discipline and open currency access gives buyers a very different outcome from one that returns to big deficits, money printing or capital controls.
There is also less of an obvious bargain than in 2023. Buyers then got distressed prices with the recovery still ahead. Today you pay after part of that recovery has happened.
So the property itself has to make sense even if Argentina improves more slowly from here.
Should buyers wait another year before buying property in Argentina?
Probably not, unless what is on offer today is mediocre or you need expensive financing.
Nothing in the Buenos Aires data points to a coming collapse that would reward waiting. Sales are close to their highest levels in years, inflation is far below crisis levels, currency access has opened up and asking prices still edge up.
At the same time, waiting a few months costs very little. Asking prices are up 1.4% since January and closing prices are flat, so there is no reason to rush into the wrong apartment.
That makes the choice simple.
Waiting for a better apartment, a motivated seller or cleaner financing makes sense. Waiting for Buenos Aires prices to go back to the 2023 lows means betting on another big Argentine crisis.
We do not see enough evidence today to make that the likely outcome.
 70+pages
Just a preview. If a price here looks old, no worries: your guide comes with this month’s numbers.
Should you wait for the peso to fall before buying?
We would not. The strong peso makes owning more expensive in dollars, but the purchase price is set in dollars and has barely moved.
The wholesale dollar rose only about 4.9% from January to late October 2026, while consumer prices rose about 23.6% from January to September. Everything paid in pesos got dearer in dollars: average building fees (expensas) in Buenos Aires reached ARS 379,774 a month in September 2026 (USD 245), up 28.6% in a year.
A devaluation would make those running costs cheaper in dollars, but it would not cut dollar asking prices one for one, and forecasters expect only a mild move this year (about ARS 1,614 per dollar at the end of 2026, roughly 4% weaker than today).
What to do: budget yearly costs in dollars at today's rate plus a margin, ask for the last twelve months of expensas before you make an offer, and favor buildings with modest fees. A unit with low expensas keeps more of a 5.70% gross yield.
Do the 2026 tax changes and new mortgages make buying now better?
For resale, yes. For buying and renting out, not much.
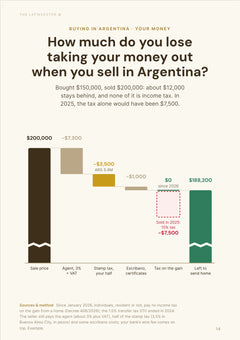
Since 1 January 2026, individuals, residents and non-residents alike, pay no income tax on the gain when they sell a property (Law 27.802 and Decree 406/2026, published 1 June 2026). The old 1.5% transfer tax (ITI) was abolished in July 2024. Companies are not covered, one more reason to buy in your own name.
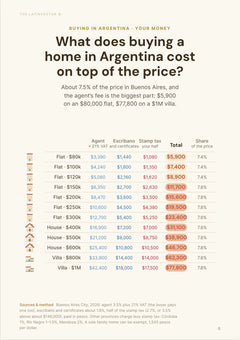
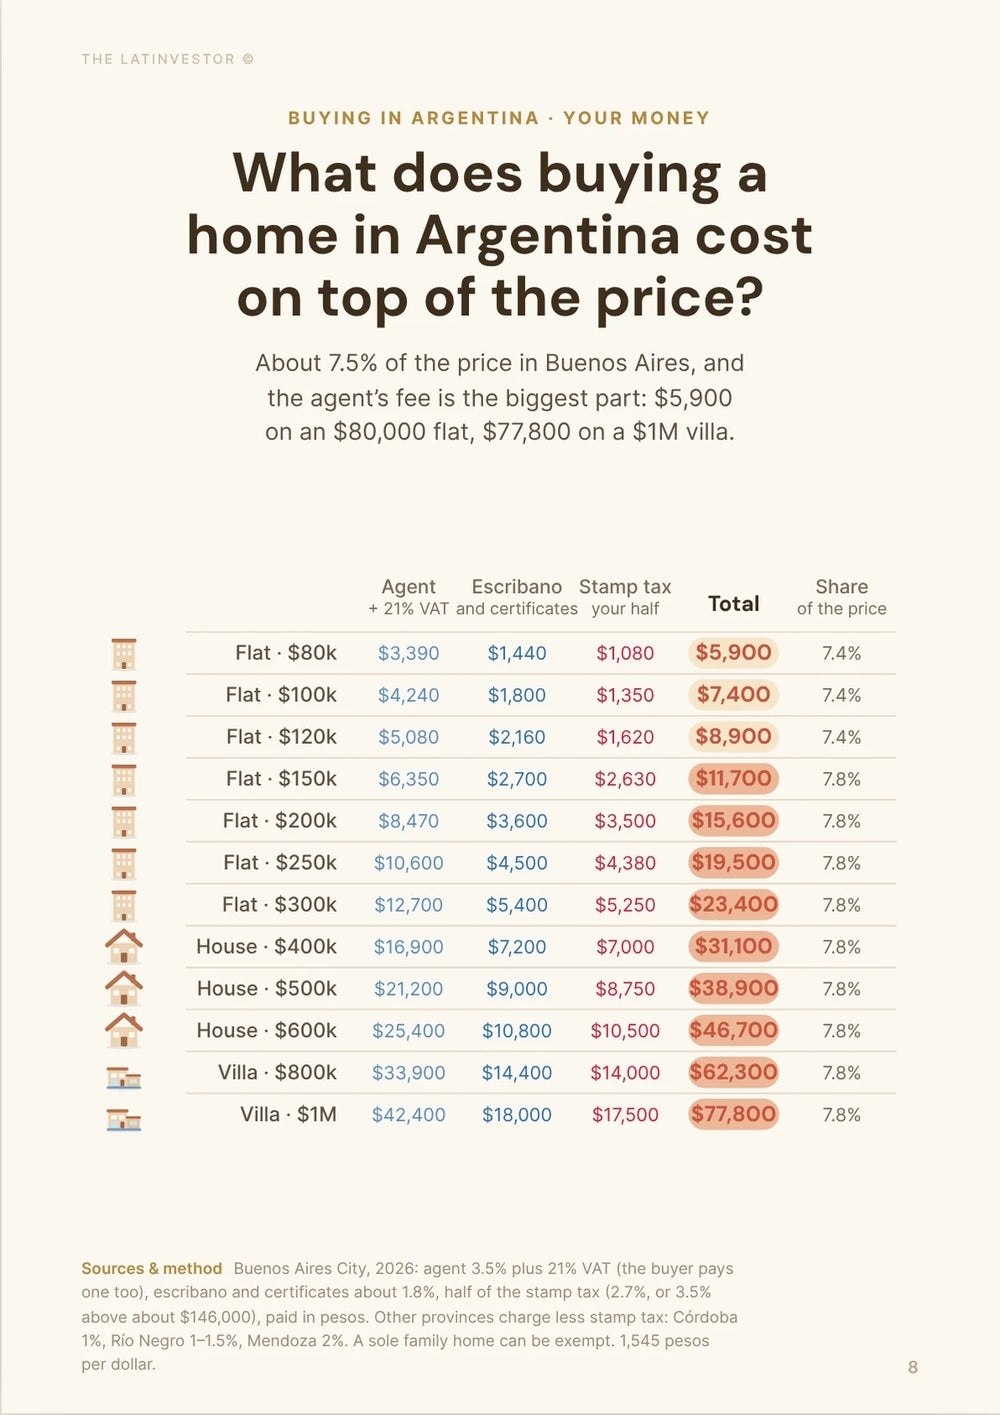
Buying still costs about 6–9% on top of the price in Buenos Aires: half of a 2.7% stamp tax, notary fees, registry and the agent. Add selling costs and a full round trip takes about 12–15%, which is why short flips rarely work.
The FGS money (ARS 400 billion so far, about USD 258 million) is a few thousand loans at Buenos Aires prices, not a return to 2025 volumes, and it is meant for locals buying their only home.
What to do: if you buy cash, a slow return of credit is good news for your resale. Favor the 50 to 80 m² apartments that local first-time buyers with a loan can afford, and check with an Argentine tax adviser how your rent will be taxed before you count on a yield.
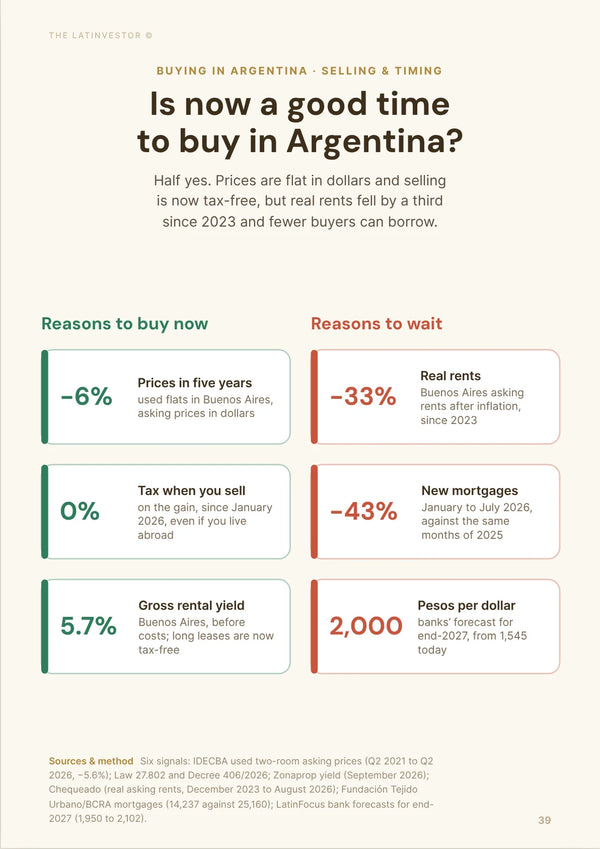
Is it a good time to buy property in Argentina now?
Yes, for a cash buyer who can hold five years or more, especially in Buenos Aires, although the easy crisis bargain is gone.
The market has recovered enough to remove some of the risks near the bottom. Sales remain high (41,583 deeds from January to August 2026), inflation has dropped from crisis levels, currency access is open and gross yields are 5.70%.
Prices have been slower to follow. Buenos Aires is still 11.3% below its peak, asking prices are up 1.4% since January and real deals are flat.
That gap is the main reason we would still buy, selectively.
Mortgages have not come back in force, which leaves another source of demand for later if credit gets cheaper. High building costs also make existing apartments hard to replace cheaply.
The limits are clear. A 5.70% gross yield shrinks after costs and, for a foreign landlord, possibly 21% of gross rent in tax. UVA loans make buying with debt uncomfortable. And you are buying after part of the recovery is already in prices.
If you hold dollars, buy a good apartment at a negotiated price and plan to keep it for years, the balance looks favorable.
If you need a big loan, expect rent to cover everything or want to sell within a year or two, we would stay out for now.
The opportunity in Argentina today comes from buying one property well, not from betting that every property in the country is about to rise.
| Buyer profile | Buy now? | Why | Biggest concern |
|---|---|---|---|
| Cash buyer with 5+ year horizon | Yes | 11.3% below the old peak, busy market | Macro reversal |
| Primary-home buyer | Generally yes | Market is working and prices are flat | Overpaying for the wrong home |
| Long-term rental investor | Selectively | 5.70% gross yield plus possible appreciation | Net yield after costs and tax |
| Investor relying on a big loan | Usually no | UVA + 6.7% to 12% beats the rent | Inflation and financing cost |
| Short-term flipper | No | Prices flat, round trip costs about 12–15% | Transaction and renovation costs |
| Buyer waiting for another 2023-style bottom | Probably no | Conditions are much healthier | Another crisis would be needed |
Our methodology
This article estimates whether October 2026 is a good time to buy property in Argentina, mainly in Buenos Aires, by looking separately at prices against the old peak and the 2023 low, price momentum, sales, mortgages, rents and yields, building costs, the stock for sale, the peso, inflation and the 2026 tax changes, then applying them to different buyer profiles.
Asking prices, model apartment prices, the gap to the peak, building costs in dollars and gross yields come from Zonaprop's indices (Buenos Aires City and Greater Buenos Aires for September 2026, Rosario for May 2026, Córdoba for March 2026); closing prices and the negotiation margin from the RE/MAX, Universidad del CEMA and Reporte Inmobiliario M² Real index (September 2026); yearly changes before 2026 from Global Property Guide and Zonaprop; new-versus-used prices from IDECBA (Q2 2026); sales and mortgage deeds from the Colegio de Escribanos de la Ciudad de Buenos Aires (August 2026); national mortgage counts from Fundación Tejido Urbano and the central bank; the stock for sale from Monitor Inmobiliario and La Nación; rental supply from La Nación; building fees from ConsorcioAbierto.
Tax rules come from Law 27.802, Decree 406/2026 and Law 27.743, with the non-resident rental question based on a June 2026 note by Estudio Piccinini; mortgage terms from Banco Nación, Banco Ciudad, BBVA and the FGS auctions; inflation from INDEC; growth and inflation forecasts from the IMF's October 2026 outlook; exchange-rate forecasts from the central bank's REM survey and the LatinFocus panel; rental rules from DNU 70/2023; rural land from the Supreme Court's 9 October 2026 ruling.
We checked these figures in October 2026. Peso amounts are converted at about ARS 1,550 per US dollar (official and MEP rates were within 1% of each other on 22 October 2026, the blue rate about ARS 1,570), and euro amounts at about ARS 1,740 per euro.
Where we had no direct figure, we said so or did simple math: the rise since the 2023 low combines Global Property Guide's 2024 and 2025 changes with Zonaprop's 2026 change, and the peak value is derived from Zonaprop's 11.3% gap. Zonaprop did not publish a 12-month change for Buenos Aires asking prices in September 2026, so we use the change since January. Rosario and Córdoba reports are a few months older than the Buenos Aires one, and asking prices are listings, not closed deals.
Key sources used for this analysis include Zonaprop's Buenos Aires report for September 2026, Zonaprop's Buenos Aires sale-price index, Revista Mercado on Buenos Aires prices, the September 2026 M² Real report, the Colegio de Escribanos on August 2026 deeds, its July 2026 report, Zonaprop's Córdoba sale-price index, Zonaprop's GBA South index, Zonaprop's January 2026 report on building costs, IDECBA new-build prices, Monitor Inmobiliario on listings, La Nación on the stock for sale, Zonaprop's Buenos Aires rental-yield index, Zonaprop's Buenos Aires rental index, La Nación on rental supply, DNU 70/2023, CPAU on Tejido Urbano's mortgage count, the central bank's September 2026 monetary report, the central bank's banking report on 2025 mortgages, the central bank on the end of currency limits for individuals, Banco Nación's mortgage terms, Banco Ciudad's mortgage terms, BBVA Argentina's mortgage terms, INDEC's consumer-price data, Infobae on September 2026 inflation, Infobae on the dollar, the REM survey for September 2026, Decree 406/2026, Estudio Piccinini on non-resident landlords, Chequeado on the rural land ruling and Argentina's official CDI procedure.