
Summary
Individuals and undivided estates are the ones who qualify: since 1 January 2026 they pay 0% income tax on rent from a home the tenant lives in permanently, and on gains when they sell Argentine property outside a trading business.
The break only removes national income tax. City and provincial property tax, provincial gross-income tax and Personal Assets Tax (Bienes Personales, 0.5% a year for a non-resident owner) all stay.
There is no cap on the number of flats. An individual with six long-term rentals can exempt all six, unlike the separate Monotributo benefit, which stops at two properties.
The tenant decides a lot. Decree 406/2026, published on 1 June 2026, requires the flat to be the tenant’s only, family and permanent home, which the landlord often can’t check.
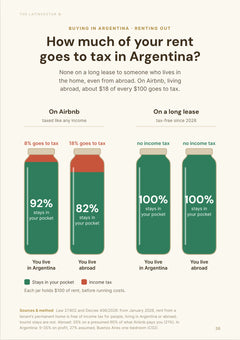
Airbnb and other tourist rentals don’t qualify: a guest staying five nights is not making the flat their permanent home. Furnished long-term lets still do.
Companies are out under the decree, even though the law didn’t say so. BDO Argentina calls the restriction unconstitutional, but no court has ruled on it.
A lease signed by an employer for an employee is shaky, because a company can’t have a family home. A lease in the employee’s own name is much safer.
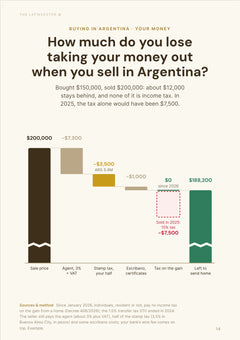
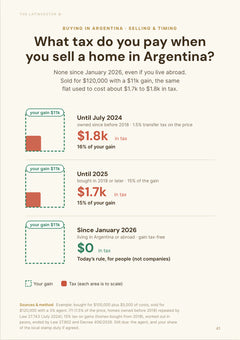
Foreign individuals who sell are explicitly covered. The old 15% tax on gains (property bought from 2018) is gone for sales from 2026, and the 1.5% ITI transfer tax already disappeared in 2024.
Flipping as a business is not covered: frequent, organised buying and selling can still be taxed as business income, even for an individual.
Old leases count too. The exemption applies to qualifying rent earned from 1 January 2026, whenever the contract was signed.
What it saves depends on your bracket: at the top 35% rate, every ARS 1 million of taxable rental profit used to cost up to ARS 350,000 in tax. Landlords also lose the 10% rent deduction under Law 27.737.
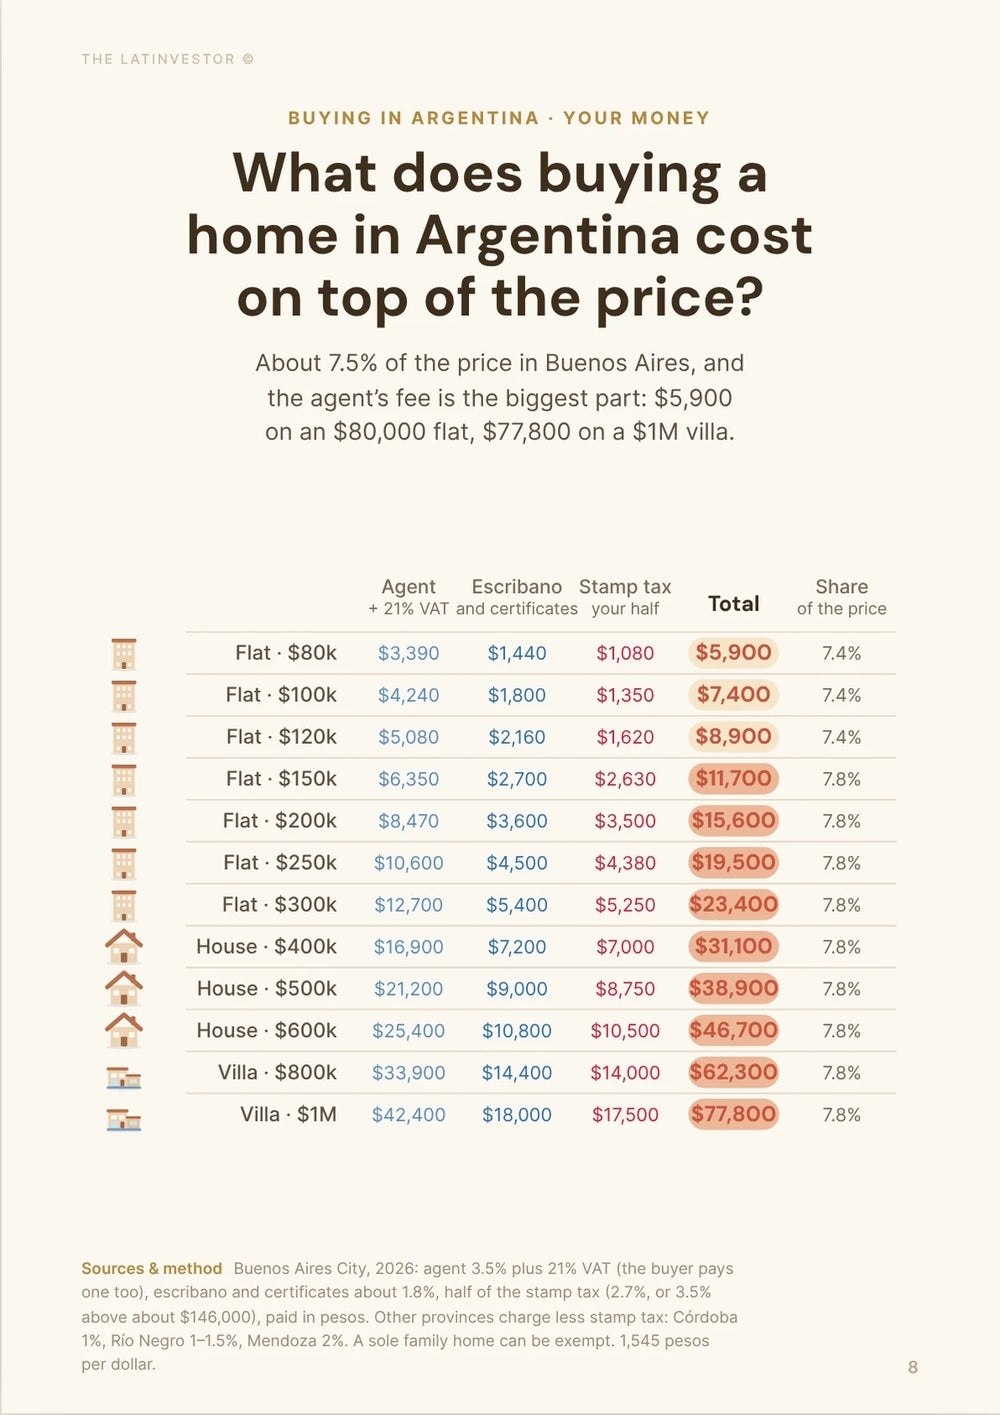
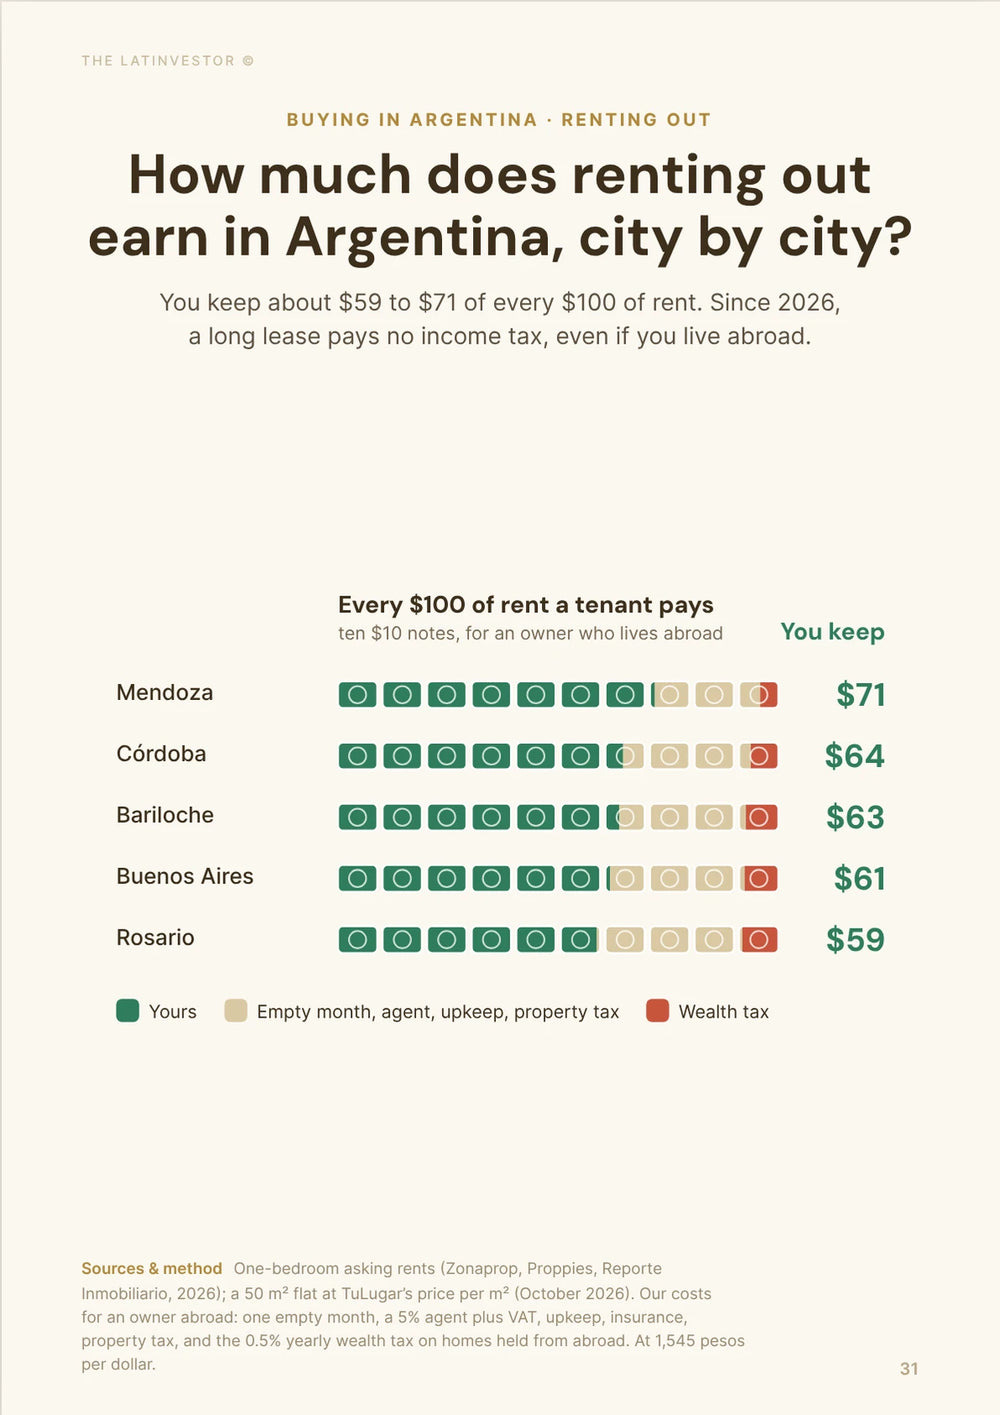
Non-resident landlords are the open question: the decree is silent on them, so until an adviser confirms otherwise, budget the usual 21% of gross rent. On a USD 150,000 flat in Buenos Aires at a 5.7% gross yield, that is about USD 1,800 a year.
Bottom line: the break is real and wide for individual landlords with long-term tenants and for individual sellers. Companies, Airbnb hosts, traders and, for rents, non-residents should not count on it.


What is Argentina’s new property tax break actually giving owners?
It removes national income tax (Ganancias) from two things: rent from homes used as a tenant’s permanent residence, and gains on certain property sales. It does not touch the taxes you pay just for owning property.
The legal base is Article 192 of Law 27.802, which changed the Income Tax Law, and Decree 406/2026, published on 1 June 2026, which sets out how it works. Both exemptions apply from 1 January 2026 and only to individuals and undivided estates.
Everything else carries on. An owner in Buenos Aires City still pays Inmobiliario and ABL, provinces still charge their own property tax, Personal Assets Tax follows its own rules, and renting can still trigger provincial gross-income tax.
So the useful question is narrower than the headlines: who can stop paying national income tax on rent or on a sale?
| Tax or charge | Government level | What happens now? | Who sets the rules? |
|---|---|---|---|
| Income Tax on qualifying residential rent | National | Exempt for qualifying cases since 1 Jan 2026 | National government / ARCA |
| Income Tax on qualifying property-sale gains | National | Exempt for qualifying cases since 1 Jan 2026 | National government / ARCA |
| Inmobiliario / ABL in Buenos Aires City | City | Still applies | AGIP |
| Provincial property tax | Provincial | Still applies | Provincial tax authority |
| Personal Assets Tax (Bienes Personales) | National | Still applies (0.5% a year for non-residents) | ARCA |
| Gross Income Tax on rentals | Provincial | Can still apply | Provincial tax authority |
Who qualifies for Argentina’s new residential rental tax exemption?
Individuals (personas humanas) and undivided estates (sucesiones indivisas) acting as landlords or sublandlords, as long as the tenant really lives in the property as their permanent home.
The decree defines a qualifying casa-habitación as the occupant’s only, family and permanent home. So what counts is how the tenant lives there, not where the landlord lives.
An individual renting a flat to a family that lives there all year fits cleanly. So does an estate collecting rent on such a home while an inheritance is being settled.
The landlord doesn’t have to own just one property. That makes the break much wider than a typical small-landlord incentive.
| Owner and use | Current position | Main reason |
|---|---|---|
| Individual renting a permanent home | Qualifies | Core case covered by Decree 406 |
| Individual renting several permanent homes | Qualifies | No portfolio-size ceiling |
| Undivided estate renting a permanent home | Qualifies | Expressly included |
| Non-resident individual renting a permanent home | Not confirmed | Decree silent on rents for people living abroad |
| Individual renting a tourist apartment | Usually does not qualify | Permanent-home test fails |
| Company renting apartments | Disputed, but decree excludes it | Regulation refers to individuals and estates |
| Individual renting commercial premises | Does not qualify | Property is not used as a home |
 Argentina Property Fees & Taxes
Can one landlord get the tax exemption on several apartments?
Yes. An individual can exempt the rent from every unit, as long as each one passes the permanent-home test. The decree says the exemption covers all the units the owner puts to qualifying residential use.
There is no one-flat or two-flat limit. The “only home” condition is checked tenant by tenant, not against the landlord’s portfolio.
Don’t mix this up with the Monotributo benefit under Law 27.737: someone whose only income is renting up to two properties can be exempt from the monthly Monotributo tax if other conditions are met. ARCA still describes that two-property rule separately.
The new income-tax exemption works differently. Six long-term flats can all be exempt; a single Airbnb flat can fail the test entirely. What matters is the type of rental, not how many you own.
Does the apartment have to be the tenant’s main home?
Yes, and more than that: it has to be the tenant’s only, family and permanent home. That is stricter than just “residential”.
A long-term tenant living there all year is the easy case. A second home, a weekday city flat or a holiday place is much harder to fit.
The word “only” is the awkward part. Commentators reading the decree (iProfesional, June 2026) give two examples that fail: a parent renting a flat to a child studying in another city, because the child’s family home is still the parents’ house, and a tenant who owns another property, even if they live in the rented one.
The law itself only said casa-habitación; the decree added “only, family and permanent”. BDO Argentina argues the decree cut back what Congress approved. Until a court says so, the safe reading is the decree’s narrower one.
Can an Airbnb or short-term rental get Argentina’s new tax break?
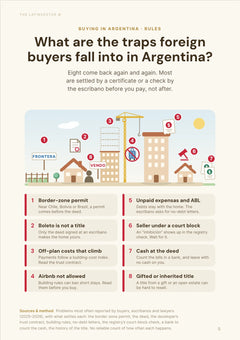
Almost never. A guest staying a few nights doesn’t make the flat their only and permanent home, so tourist rentals stay taxable, and provincial gross-income tax and possibly VAT apply on top.
Furniture is not the problem. Decree 406 expressly includes payments for furniture, fittings and services in the exempt rent when the home itself qualifies. A family renting a furnished flat for two years as its home has a strong case.
The middle ground is messy. An executive posted to Argentina for ten months, a student renting for the academic year or a worker sent to another province may really live in the flat while keeping another home. Those cases hit the “only” and “permanent” wording head on.
The decree sets no minimum length. Duration helps, but the real test is whether the occupant made the flat their home.
| Type of rental | Current qualification outlook | Main issue | Confidence |
|---|---|---|---|
| Ordinary long-term family home | Strong | Fits permanent-home definition | High |
| Furnished long-term home | Strong | Furniture does not block exemption | High |
| Student accommodation | Weak to unclear | Family home usually elsewhere | Medium |
| Temporary expatriate housing | Depends on facts | Other residence may remain | Medium |
| Holiday rental | Weak | Temporary occupation | High |
| Airbnb-style tourist stay | Weak | Not a permanent home | High |
 70+pages
Can a company that owns apartments claim the exemption?
Not under the decree. Companies and trusts that rent out homes keep paying income tax, even though tax specialists question whether the government had the power to exclude them.
Law 27.802 exempted rent from homes used as casa-habitación without saying the landlord had to be an individual. Decree 406 then limited it to individuals and undivided estates.
BDO Argentina calls that an unconstitutional restriction, and El Cronista reported the same dispute in June 2026, including the exclusion of companies and trusts. No court had settled it by October 2026.
In practice, a company filing as if its rent were exempt takes a much bolder position than an individual owner. Same flat, same tenant, same rent: the ownership structure changes the answer.
What if a company rents the apartment for one of its employees?
That lease is much less secure than one signed by the employee, even when the flat is clearly a home.
The decree applies the casa-habitación test to the tenant or subtenant named in the lease. If a multinational signs a two-year lease and puts an executive and their family in the flat, the tenant is the company, and a company can’t have a family home.
If the employee signs the lease personally and the employer pays or guarantees the rent, the tenant is a person who can actually live there permanently. That is a much stronger case.
There is a second cost: tax advisers quoted by El Cronista in June 2026 said a company tenant can no longer deduct the rent it pays to an exempt landlord. The decree has no detailed corporate-housing regime, so check the contract structure before signing.
Can foreign property owners qualify for Argentina’s new tax break?
When they sell, yes. Decree 406 expressly covers individuals and undivided estates living in Argentina or abroad who sell Argentine property, or transfer rights over it, in the cases covered by Article 99 of the Income Tax Law.
Nationality isn’t the test. A French tax resident selling a flat in Buenos Aires can be exempt, and so can an Argentine living abroad.
When they rent, it is not confirmed. The decree mentions people living abroad for sales but says nothing similar for rents, and specialists disagree on whether non-resident landlords are covered (Estudio Piccinini, 29 June 2026).
Article 28 of the Income Tax Law adds a catch: Argentina won’t grant an exemption that simply shifts the tax to another country’s treasury. And you may still owe tax where you live, even when Argentina charges nothing.
Are ordinary property sales in Argentina basically Income Tax-free now?
For most individuals, yes. Two reforms combined to get there.
The 1.5% transfer tax (ITI), which hit sales of property bought before 2018, was abolished by Law 27.743 in July 2024.
Property bought from 2018 fell under Article 99 instead, with a 15% tax on the gain. Law 27.802 and Decree 406 exempt those sales by individuals from 1 January 2026.
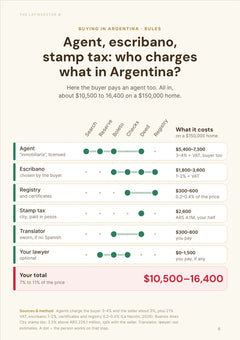
“Ordinary” still matters. A company selling property stays in corporate tax, someone who trades property as a business can be taxed on business income, and stamp tax and agent fees haven’t gone anywhere.
For an individual who bought a flat as an investment and sells it outside a trading business, the federal tax bill on the sale is now zero in most cases.
| Seller / property situation | Earlier federal treatment | Current broad position |
|---|---|---|
| Individual with property under old ITI regime | 1.5% ITI in qualifying cases | ITI abolished (July 2024) |
| Individual with Article 99 property gain | Gain could face 15% tax | Qualifying gain exempt from 1 Jan 2026 |
| Non-resident individual seller | Gain could face 15% tax | Expressly exempt from 1 Jan 2026 |
| Individual selling qualifying principal home | Favorable treatment already existed | Remains favorable |
| Company selling property | Corporate tax rules | Still taxed under corporate regime |
| Professional property trader | Business-income rules can apply | New exemption does not automatically shelter business profit |
 70+pages
Can someone keep flipping properties and pay no Income Tax?
No. The sale exemption doesn’t turn a property business into a tax-free one.
Buying a flat, renting it for a few years and selling it is the ordinary investment case. A developer buying lots, building units and selling them is running a business.
There is no simple rule like “three sales and you’re a trader”. How often you sell, how organised you are and what you intended all count.
Expect disputes at the edges, but the direction is clear: the reform was not written to exempt the profits of a real-estate business, whether it is run through a company or by an individual.
Do old rental contracts qualify, or only new ones?
Old contracts qualify too. The exemption applies to qualifying rent earned from 1 January 2026, whenever the lease was signed. Decree 406 says so directly.
A landlord didn’t need to wait for a lease to end or sign a new one to get the benefit.
Two identical flats, both lived in by their tenants as their permanent home, one lease from 2024 and one from 2026: same tax result for rent earned in 2026.
The purchase date still matters for working out which sale regime applied in the past, but it plays no role in the rental exemption.
How valuable is Argentina’s rental tax exemption for an owner?
Very valuable for a landlord in a high bracket; close to nothing for one who paid little income tax anyway.
Before 2026, rental profit was added to the owner’s other income and taxed on Argentina’s progressive scale, which tops out at 35%. At that rate, every ARS 1 million of taxable rental profit cost up to ARS 350,000 in tax. Now it costs nothing.
Rents make the stakes bigger. A 2-room flat in Buenos Aires City was listed at ARS 898,154 a month in September 2026 (about USD 580), up 28.7% in a year (Zonaprop), so about ARS 10.8 million a year of rent per flat.
One trade-off: Law 27.737 gave landlords a 10% deduction on residential rent. Decree 406 says it no longer applies to individuals and estates covered by the exemption; tenants keep their own deduction (ARCA, quoted by El Cronista in June 2026). Older ARCA pages still describe the landlord deduction, so don’t stack the two.
Does the new exemption mean a rental property is tax-free?
No. A landlord can pay zero national income tax on qualifying rent and still owe other taxes and paperwork.
ARCA still requires landlords to register and invoice the rent: Monotributo landlords issue electronic C invoices, others follow the rules for their status.
Provinces add their own layer. ARBA says renting property is subject to Buenos Aires Province gross-income tax, with its own exemption thresholds, regardless of the national exemption.
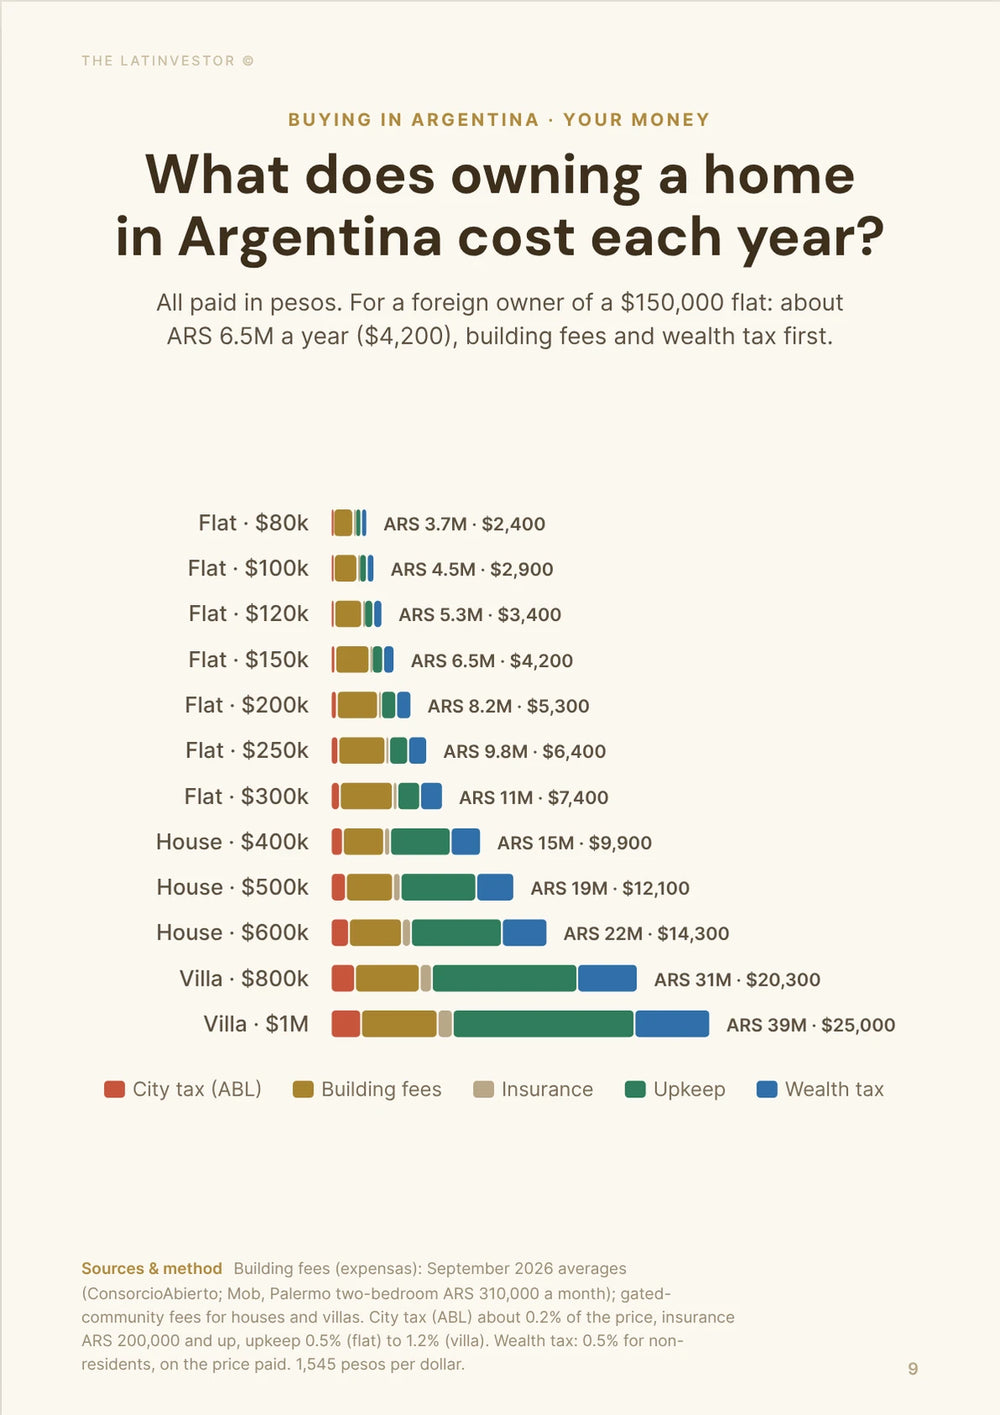
Then come the provincial property tax or Buenos Aires City’s Inmobiliario/ABL, and Personal Assets Tax. A non-resident owner pays that at 0.5% a year with no allowance, through a local representative (responsable sustituto). The bill falls; it doesn’t disappear.
| Tax or obligation | Removed by the new Income Tax exemption? | Current position |
|---|---|---|
| Income Tax on qualifying residential rent | Yes | Main new benefit (not confirmed for non-residents) |
| ARCA registration | No | Landlord obligations continue |
| Rental invoicing | No | Electronic documentation still required |
| Provincial Gross Income Tax | No | Depends on provincial rules and exemptions |
| Provincial / city property tax | No | Continues separately |
| Personal Assets Tax | No | 0.5% a year for non-residents, no allowance |
 70+pages
Is this the same tax break as Buenos Aires property-tax exemptions?
No. Buenos Aires property-tax relief and the national rent and sale exemptions follow separate rules. Qualifying for one says little about the other.
They can even point in opposite directions. The national rent exemption works across several flats, while local benefits often target a single home with value and ownership conditions. Buenos Aires City’s stamp-tax exemption, for example, is only for a buyer’s sole permanent home, up to ARS 226.1 million.
Buenos Aires Province has its own exemptions and credits, and its gross-income tax on rents is another question again.
So one owner can get the national exemption on rent and still pay local property tax, and another can get local relief on their home with no rent to exempt. Calling a property “tax-free” mixes up regimes that have nothing to do with each other.
Do non-resident landlords get the rent exemption?
Nobody can say yes for sure. Decree 406 extends the sale exemption to people living abroad in so many words, but its rental article only says “individuals and undivided estates”, with no word on people living abroad. Estudio Piccinini (29 June 2026) reads that as a possible exclusion, while noting the law itself doesn’t clearly support it.
Until ARCA or a court clarifies it, budget the usual withholding for foreign beneficiaries: 35% on a presumed 60% net, which is 21% of gross rent, deducted by the tenant or agent. Airbnb income is taxed that way whatever happens.
On a USD 150,000 flat in Buenos Aires City at the city’s 5.7% gross yield (Zonaprop, September 2026), that is about USD 8,550 of rent a year and USD 1,800 of tax. Add about USD 750 of Personal Assets Tax and you keep about USD 6,000, or 4.0%, before ABL, repairs and empty months.
If you want to claim the exemption anyway, Piccinini suggests getting proof of your tax residence abroad (certificate from your tax authority, legalised by the Argentine consulate) and a written opinion from a local adviser, given the Article 28 rule on shifting tax to foreign treasuries.
How much does the exemption change rental yields in Buenos Aires?
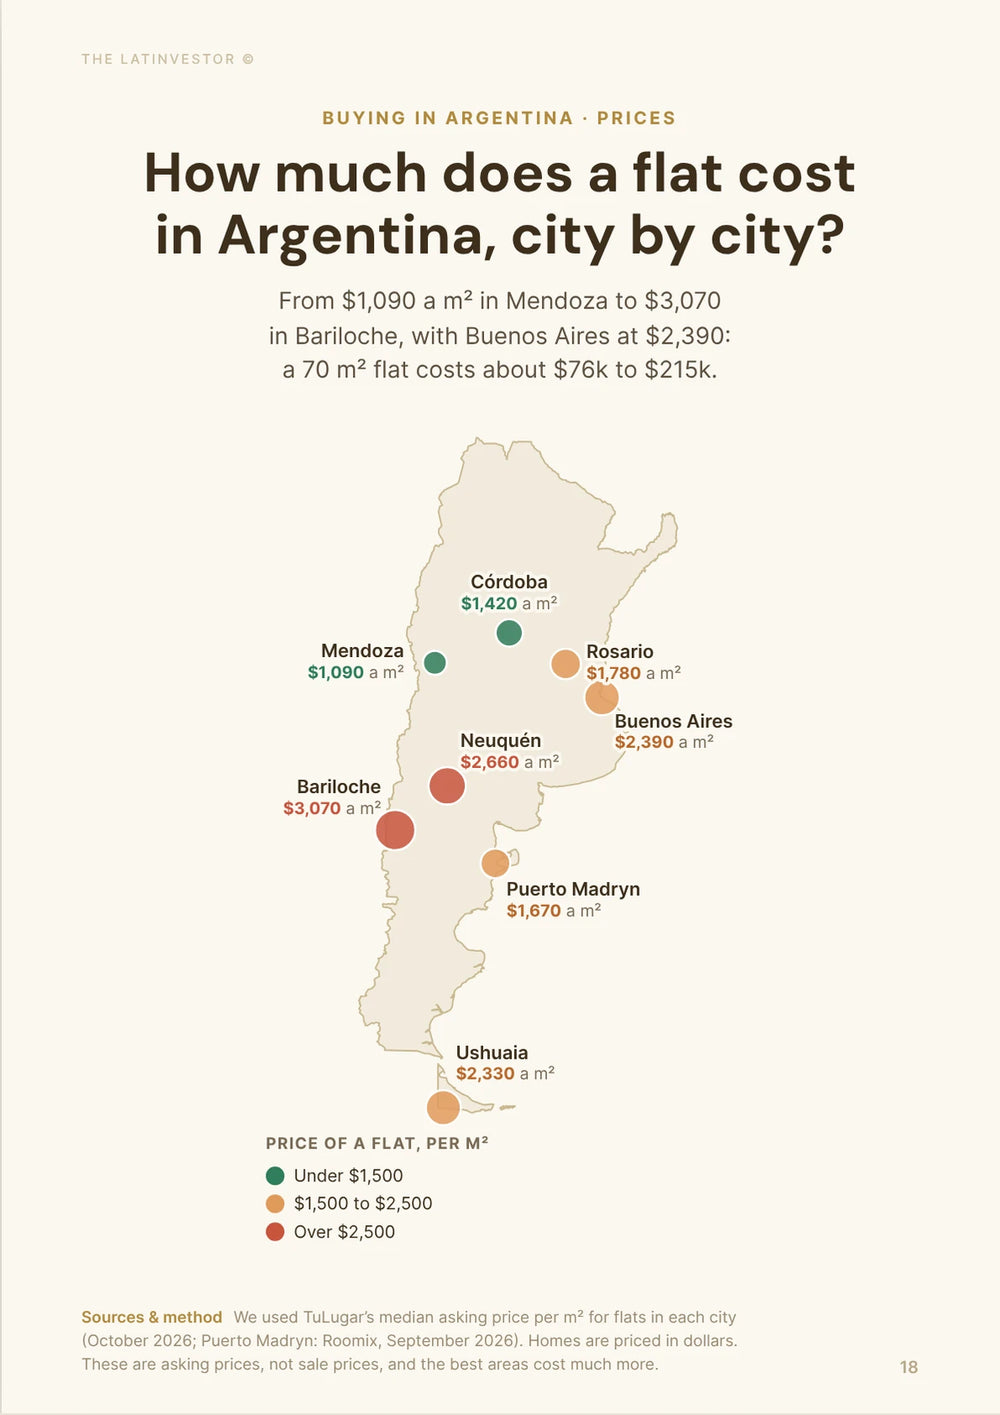
For a resident individual with a long-term tenant, the 5.7% gross yield in Buenos Aires City (Zonaprop, September 2026) is no longer cut by income tax. Only expenses, provincial and city charges, and Personal Assets Tax come off it.
For a non-resident with the same flat, the cautious net is about 4.0% after the 21% rent tax and 0.5% wealth tax, as shown above. That gap of roughly 1.7 points is the price of the uncertainty.
Rents are rising, but more slowly than inflation: the 2-room asking rent rose 28.7% in a year while inflation was 33.4% (INDEC, September 2026), and rental listings are about 3.6 times their February 2023 low (La Nación, October 2026). With more supply since the end of rent control (DNU 70/2023), tenants have room to negotiate.
Gross yields are higher in parts of Greater Buenos Aires: 7.44% in GBA Sur and 7.10% in GBA Oeste (Zonaprop, September 2026). The exemption applies the same way there; ARBA gross-income tax is the extra item to check.
 70+pages
What should a landlord check before counting on the exemption?
Write the real use into the lease. Commentators advise stating in the contract that the flat is the tenant’s only, family and permanent home (iProfesional, June 2026). It won’t prove everything, but it is your first piece of evidence.
Ask the tenant the right questions before signing: do they own another home, is this their family residence, is the rent paid by them or by an employer? A student or a tenant who owns another flat can make the exemption fail.
Put the lease in the employee’s name for corporate housing, and don’t mix tourist stays with long-term lets in the same tax year without separate accounts.
If you live abroad, get a written opinion before you stop the 21% withholding. Saving USD 1,800 a year on a USD 150,000 flat is worth one adviser’s fee; a claim that falls apart later costs more.
What is the biggest problem with the new rental exemption right now?
The landlord’s tax depends on facts about the tenant that the landlord can’t easily check.
A landlord can see the lease, who pays and that the flat is for residential use. Knowing whether the tenant owns another flat, keeps a home abroad or quietly uses yours as a second home is much harder.
And the test is tighter than what Congress passed. BDO Argentina and other specialists argue the government added restrictions rather than clarifying the law. The same applies to excluding companies, and the silence on non-resident landlords adds a third grey zone.
If courts eventually rule that Decree 406 went too far, the exemption could widen. For now, the decree’s narrow reading is the safe one. You can be much more confident on the clear points: no limit on the number of flats, and old leases count.
So who actually gets Argentina’s new property tax break?
Individuals who own property directly and either rent it to someone as their real permanent home, or sell it outside a trading business. Since 1 January 2026, both pay 0% national income tax.
That is wider than it sounds. There is no limit on the number of flats, old leases count, and furnished long-term lets are fine. On sales, the end of the 1.5% ITI in 2024 and of the 15% tax on gains in 2026 means most ordinary individual sales pay no federal tax at all, for foreigners too.
It gets uncomfortable away from that core. Tourist rentals have a weak case, corporate housing depends on whose name is on the lease, companies are excluded by the decree (and challenging it), traders can’t shelter business profits, and non-resident landlords should keep budgeting 21% of gross rent until told otherwise.
In short: if you are a foreign individual, the sale side is a clear win; the rent side is a maybe. Plan on the cautious numbers and treat any confirmed exemption as a bonus.
Our methodology
This article explains who qualifies for the income-tax exemptions on residential rent and property sales that Argentina introduced from 1 January 2026, and who doesn’t, looking separately at the owner, the use of the property, the type of transaction and the tax concerned.
The rules come from primary texts first: Article 192 of Law 27.802 and Decree 406/2026 (published 1 June 2026) for the exemptions, the consolidated Income Tax Law for Article 28 and Article 99, and Law 27.743 for the end of ITI. The yield example uses Zonaprop’s September 2026 Buenos Aires City gross yield of 5.7% and asking rents, the 21% non-resident withholding (35% on a presumed 60% net) and the 0.5% Personal Assets Tax for non-residents, the same figures as our article on Argentine property taxes and fees.
For the contested points (company exclusion, tenant-use test, non-resident landlords, the 10% deduction), we cross-checked commentary from El Cronista, La Nación, iProfesional, BDO Argentina as reported in the press and Estudio Piccinini. Local and provincial taxes come from AGIP and ARBA guidance, and the Monotributo rule from ARCA.
We checked these figures in October 2026. Peso amounts are converted at about ARS 1,550 per US dollar (official and MEP rates were within 1% of each other on 22 October 2026, the blue rate about ARS 1,570), and euro amounts at about ARS 1,740 per euro.
Where we had no direct answer, we said so: the treatment of non-resident landlords, corporate housing and students is not settled by any ruling, so we used the cautious reading of the decree and the standard 21% withholding as a default. The tax saved by a resident landlord depends on their bracket and expenses, so we gave the top-rate arithmetic, not an average. This is not tax advice.
Key sources used for this analysis include Law 27.802, Decree 406/2026, ARCA’s legal library on Decree 406/2026, the current consolidated Income Tax Law, Law 27.743 on the abolition of ITI, ARCA’s Monotributo guidance, ARCA’s rental invoicing guidance, ARCA on Bienes Personales, AGIP’s Inmobiliario/ABL guidance, ARBA on gross-income tax for rentals, Estudio Piccinini on non-resident landlords, El Cronista on the dispute over Decree 406, El Cronista on the deductions that remain, iProfesional on the only-home test, La Nación’s June analysis of the rental exemption, La Nación’s August follow-up on the tenant-use test, and Infobae on INDEC inflation.