
Summary
Yes, but at a lower level than in 2025: banks granted 14,237 mortgages from January to July 2026, 43% fewer than a year earlier, after about 43,700 people took a new mortgage in 2025.
The comeback is real. The central bank counted about 10,000 new mortgage borrowers in 2024 and about 43,700 in 2025, after years when new mortgages ran at a few thousand a year.
2026 cooled fast, but July brought 2,527 new loans against 1,968 in June, and the central bank's September report shows mortgage lending growing again.
People did not stop buying. Buenos Aires City deeds fell only 2.3% from January to August 2026, while deeds with a mortgage fell 34%.
Mortgages still finance about one purchase in seven: 14.8% of Buenos Aires City deeds in January–August 2026 and 12.6% of Buenos Aires Province deals in the first half.
Finding a product is easy. Banks lend 70% to 80% of the price over up to 30 years; getting approved is the hard part.
Rates are lower than at the worst of 2025 but not back to the 2024 launch deals: from UVA + 6.5% to 6.7% at Banco Ciudad and Banco Nación for the best profiles, up to UVA + 12% for everyone else.
One average salary is not enough. A 30-year loan on a USD 131,000 Buenos Aires one-bedroom starts at about ARS 980,000 a month, which needs about ARS 3.9 million of income, roughly two average formal salaries.
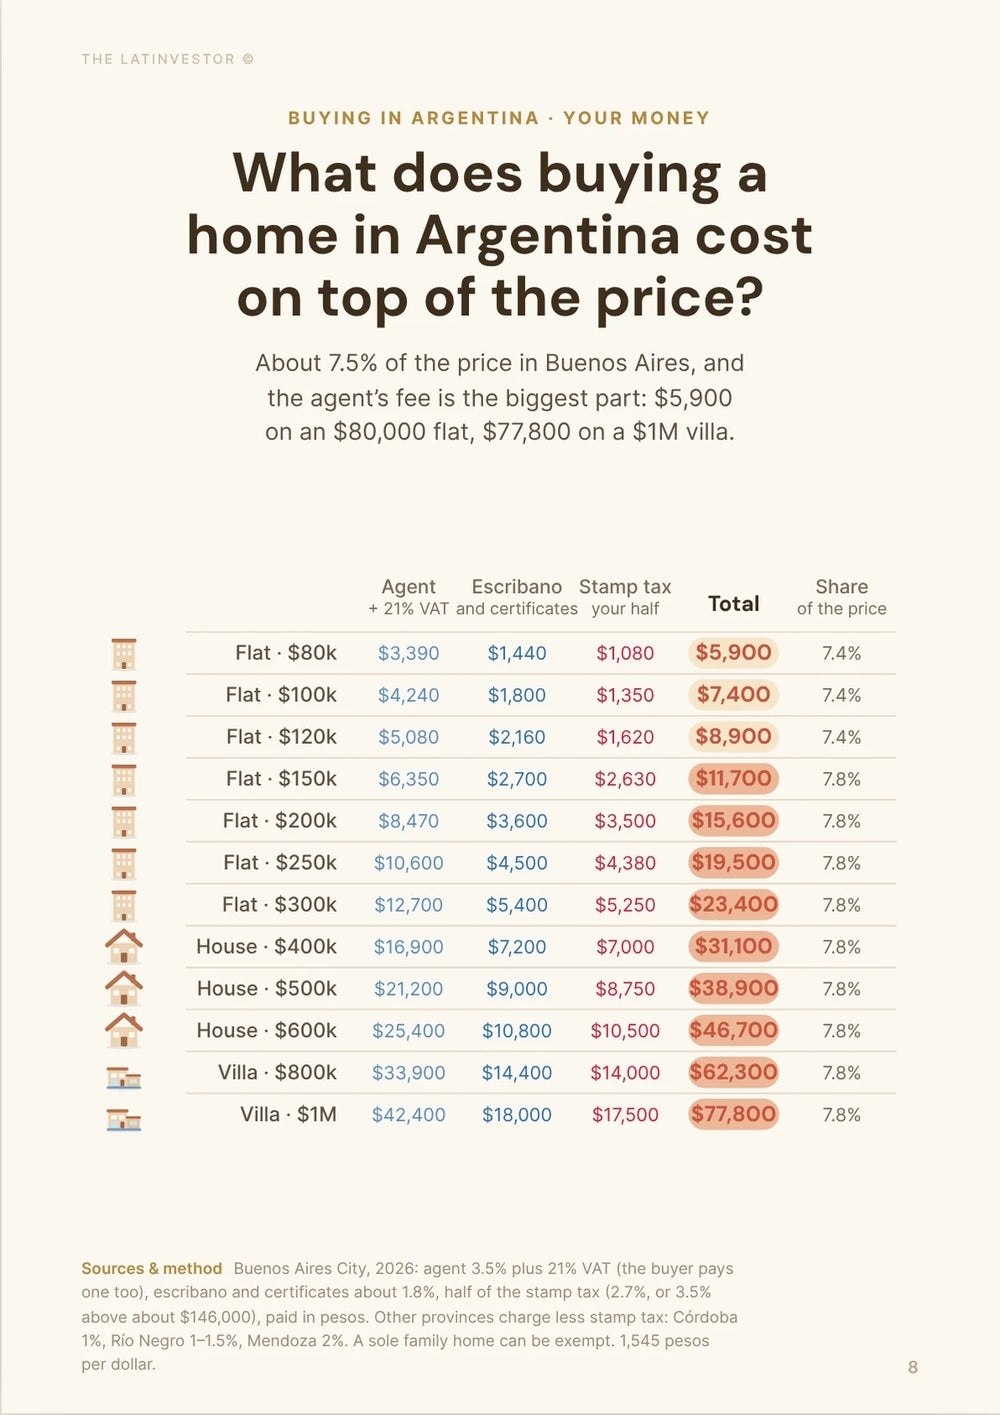
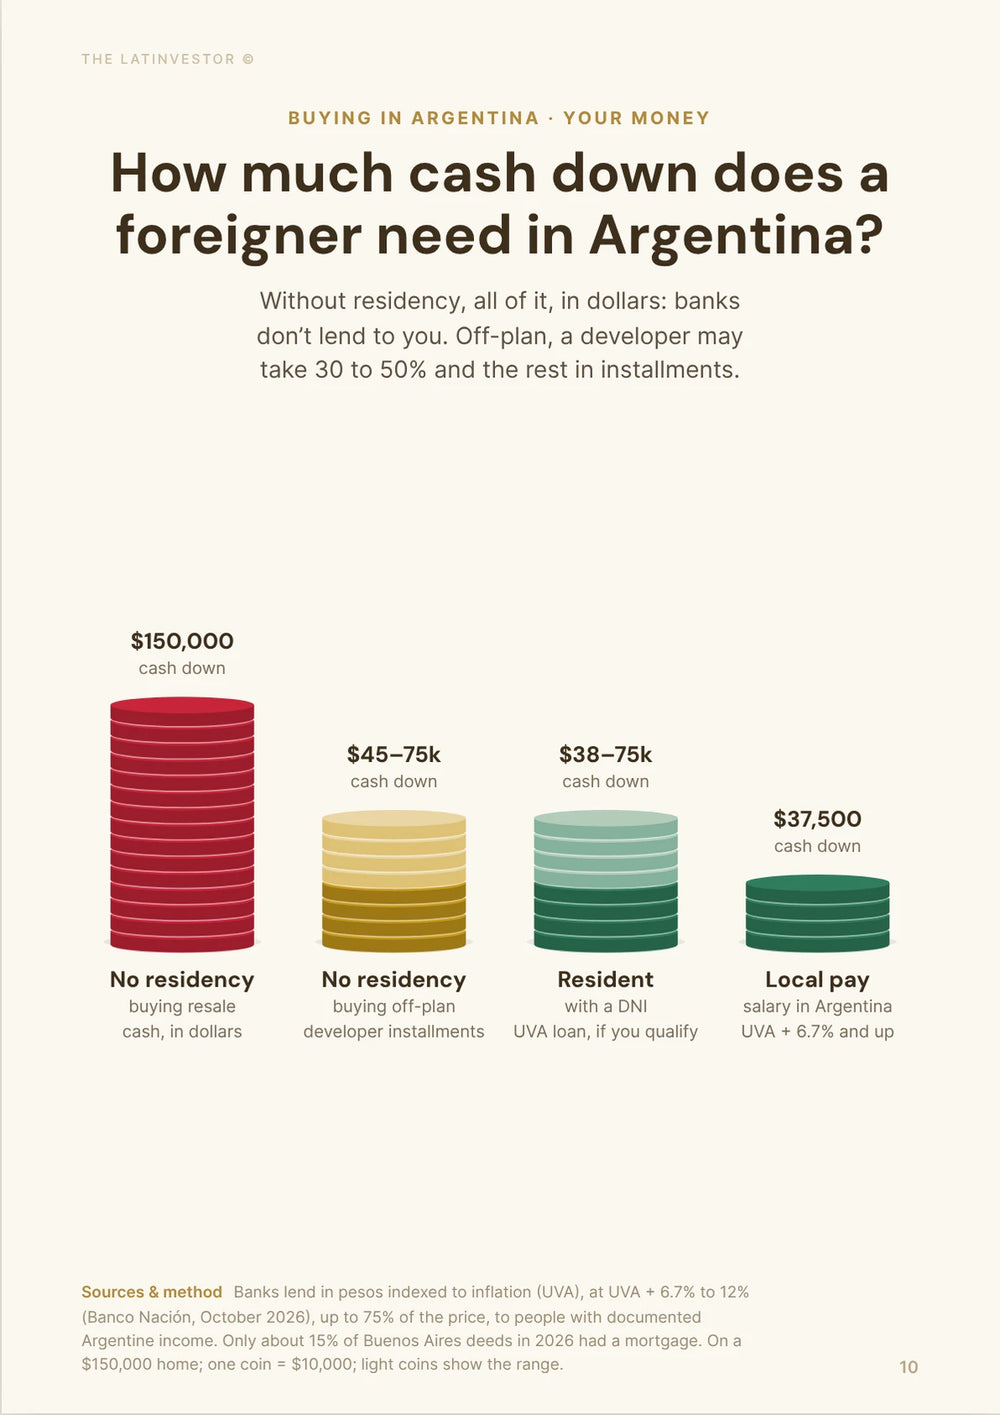
The down payment hurts as much: about USD 32,750 on that one-bedroom at 75% financing, plus 6% to 9% in buying costs.
Borrowers are a narrow group: 85% of new borrowers in 2024 were salaried employees, and 63% of 2025 borrowers were aged 35 to 49.
The recovery leans on one public bank: Banco Nación wrote 65.9% of all new mortgages from January to July 2026.
UVA loans still carry inflation risk. The balance follows prices, which rose 33.4% over the 12 months to September 2026, even if only about 1.6% of old UVA borrowers were behind on payments in 2022.
The government is pushing money in: two auctions of pension-fund money (FGS) placed about ARS 400 billion with banks in September and October 2026 for loans at UVA + 7.5% at most.
For dollar earners, the strong peso made UVA debt dearer: a UVA balance grew roughly 18% in dollar terms from January to September 2026.
Bottom line: a household with solid, documented peso income and USD 30,000 to USD 45,000 saved can borrow again; mass mortgage lending is not back, and a non-resident with only foreign income has no confirmed access.


How big was Argentina's mortgage rebound in 2024 and 2025?
Big. After several years when getting a home loan was almost unheard of, mortgages came back in force.
The change started in 2024, when banks reopened UVA mortgage lines as inflation fell and wages recovered. The central bank (BCRA) counted around 10,000 new mortgage borrowers that year, almost three times the 2023 figure.
Then the market took off. The BCRA recorded about 43,700 new mortgage borrowers in 2025, taking the number of people with mortgage debt to almost 180,000. Fundación Tejido Urbano, which counts loans rather than people, gets 11,775 loans in 2024 and 44,612 in 2025.
Between 2019 and 2023, new mortgages had shrunk to a few thousand a year. By mid-2025 banks were granting about that many in a single month (5,125 in July 2025).
So mortgage lending did restart. The open question is whether it can last beyond one good credit cycle.
| Period | New mortgage borrowers | What was happening |
|---|---|---|
| 2017 | ~58,600 | Previous UVA boom |
| 2019-2023 | A few thousand a year | Mortgage lending barely moving |
| 2024 | ~10,000 | Banks reopen UVA lending |
| 2025 | ~43,700 | Recovery accelerates |
| January–July 2026 | 14,237 loans (-43%) | Slowdown, then a better July |
Are mortgages in Argentina really back if lending is already slowing?
Yes, but the first boom has cooled a lot.
Banks granted 14,237 mortgages from January to July 2026, against 25,160 in the same months of 2025: down 43% (BCRA data compiled by Fundación Tejido Urbano, September 2026).
The slowdown started before 2026. BCRA data show around 4,200 new borrowers in August 2025, then about 2,500 in November and about 2,400 in January 2026. Activity kept falling until May 2026.
Annualising January–July gives roughly 24,400 loans for 2026. That is still several times the 2019–2023 pace, so Argentina is not back to frozen credit.
A market running at a bit more than half of last year's speed is not a boom any more. It is a working mortgage market looking for its normal level.
Did Argentine mortgages slow because people stopped buying homes?
No. Argentines are still buying homes; it's the mortgage-backed purchases that dropped.
Buenos Aires City gives the cleanest comparison. The Colegio de Escribanos recorded 41,583 sale deeds from January to August 2026, only 2.3% fewer than a year earlier.
Deeds with a mortgage tell another story: 6,170 over the same eight months, against 9,341 in 2025, down 34%.
Buenos Aires Province shows the same gap. In the first half of 2026, all property deals fell 7.8% while deals with a mortgage fell 32.6% (Tejido Urbano).
So this is not a housing slump. Buyers are still closing deals; financing is the part that weakened.
| Market | Change in total purchases | Change in mortgage purchases | Gap |
|---|---|---|---|
| Buenos Aires City, January–August 2026 | -2.3% | -34% | ~32 points |
| Buenos Aires Province, first half 2026 | -7.8% | -32.6% | ~25 points |
 Buying in Argentina as a Foreigner
How many Argentine homebuyers actually use a mortgage today?
About one in seven in the two biggest markets.
In Buenos Aires City, 6,170 of the 41,583 purchases from January to August 2026 used a mortgage: 14.8%. August alone was a bit better, with 1,059 mortgage deeds out of 6,055 (17.5%).
A year earlier the share was higher: about 22% of Buenos Aires City purchases in January–August 2025 used a mortgage.
Buenos Aires Province looks similar. Tejido Urbano counted 6,913 mortgage deeds among 55,035 deals in the first half of 2026, a 12.6% share.
That is far better than the years when credit barely touched the housing market. Still, most Argentine homes change hands without a bank loan, while in countries with deep mortgage markets a loan is the normal way to buy.
Are Argentine banks offering enough mortgages now?
Finding a bank that offers a mortgage is easy again; qualifying for a useful one is where it gets hard.
Lenders include Banco Nación, Banco Ciudad, Banco Provincia, Santander, BBVA, Galicia, ICBC, Macro, Credicoop, Banco Hipotecario, Supervielle and several provincial banks.
Terms look like a real mortgage market. Banco Nación and BBVA lend over up to 30 years, Banco Ciudad up to 25, others over 15 to 20.
Banks finance 70% to 80% of the value (BBVA 80%, Banco Nación 75%), so a buyer needs 20% to 30% of the price before taxes and fees.
Where your salary is paid matters a lot. Banco Nación, BBVA and Santander keep their best rates for customers whose wages land in their accounts.
So availability is no longer the bottleneck. Income, rates and the down payment knock out far more buyers than a lack of products.
Are Argentine mortgage rates finally cheap again?
Cheaper than at the worst of 2025, but not as cheap as when the revival started.
Some of the first UVA lines in 2024 came with rates around 4% to 6% over inflation. Banco Nación offered 4.5% to eligible customers, ICBC was around 5% and Santander around 5.5%.
That did not last. As financial conditions tightened in 2025, a La Nación review found the average advertised rate had climbed from about 5.1% at the relaunch to about 11.1% in the second half of 2025.
Rates have come down since. In October 2026, Banco Nación charges UVA + 6.7% to customers paid through it who buy a single home, and UVA + 12% otherwise. Banco Ciudad offers UVA + 6.5% on first homes up to 80 m² (until 31 December 2026) and 7.5% on its general line. BBVA goes from UVA + 7.5% with salary and insurance to 11.5% without salary.
That helps borrowers pushed out in 2025. Anyone waiting for the 4.5% deals of 2024 is still waiting.
| Bank / offer | Rate over UVA | Maximum term | Main catch |
|---|---|---|---|
| Banco Ciudad first home (to 31 Dec 2026) | 6.5% | 25 years | Homes up to 80 m²; general line 7.5% |
| Banco Nación single home (Oct 2026) | 6.7% | 30 years | Salary paid at Banco Nación; 12% otherwise |
| BBVA permanent home (Oct 2026) | 7.5% to 11.5% | 30 years | 7.5% needs salary at BBVA plus insurance |
| Macro (April 2026 offer) | 8.5% | Varies | Older offer: ask for a current quote |
| Santander (April 2026 offer) | 9.5% | 20 years | Salary paid through Santander, 70% financing |
 70+pages
Why can a 7% UVA mortgage still become expensive?
Because you pay 7% on a balance that also grows with inflation.
UVA loans fix a problem that killed long-term lending in Argentina: a bank can lend pesos for 20 or 30 years without inflation wiping out what it gets back.
For the borrower, the capital is adjusted with the CER inflation index, and the monthly payment moves with it.
When wages keep up with inflation, that is manageable. Trouble starts when prices rise much faster than income.
That is what happened after the last UVA boom. People who borrowed in 2016–2018 saw payments and balances jump when inflation took off, and governments ended up adding payment caps and relief measures.
Defaults stayed lower than the political noise suggested: BCRA data have long shown low mortgage delinquency compared with other household credit.
The real risk for today's borrower is what inflation and wages do over the next 10, 20 or 30 years.
Can an average Argentine salary actually qualify for a mortgage today?
No. One average formal salary is nowhere near enough for a typical Buenos Aires loan.
The official RIPTE index puts the average wage of stable registered workers at about ARS 1.98 million a month in August 2026 (USD 1,280).
Take a USD 131,000 one-bedroom with 75% financing: a loan of about ARS 152 million. Over 30 years at UVA + 6.7%, the first payment is about ARS 980,000 (USD 635); over 20 years at UVA + 7.5%, about ARS 1.23 million (USD 790).
Banks usually cap the first payment at about 25% of income. That means about ARS 3.9 million to ARS 4.9 million a month of documented income, two to two and a half average salaries.
A couple with two solid registered salaries can get there. A single worker near the average usually can't.
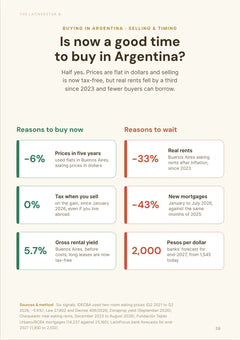
Inflation is much lower than at the peak of the crisis, which helps: INDEC measured 1.9% in September 2026 and 33.4% over 12 months. Wage indexing has a much better chance of keeping up than when inflation ran in triple digits.
Still, this recovery favours households with strong formal incomes. The average worker has not gained easy access to a home.
Is the down payment an even bigger problem than the monthly mortgage?
For many buyers, yes: finding USD 27,500 to USD 45,000 upfront is as hard as passing the income test.
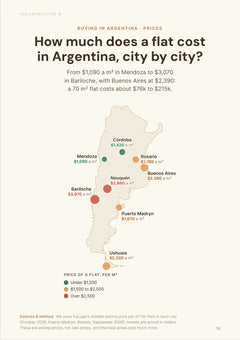
Zonaprop put the average Buenos Aires City asking price at USD 2,484/m² in September 2026.
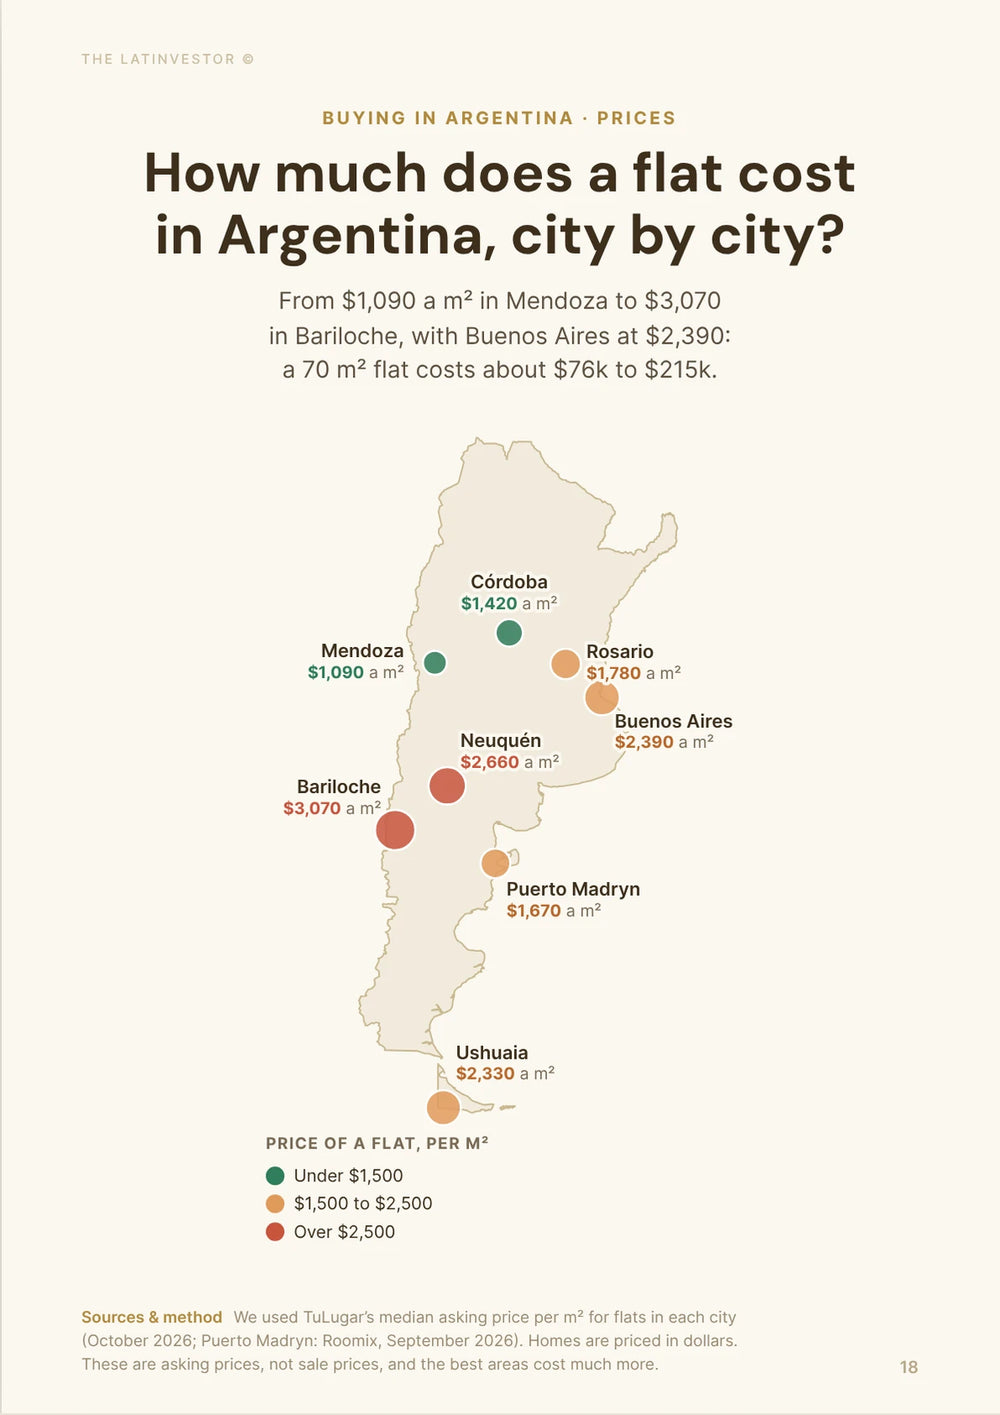
Its model apartments: about USD 110,000 for a 40 m² studio, USD 131,000 for a 50 m² one-bedroom and USD 180,000 for a 70 m² two-bedroom.
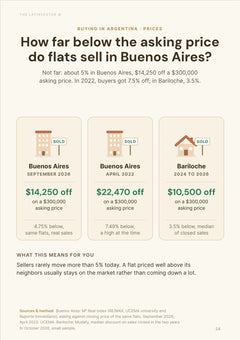
Prices are flat: asking prices are up only 1.4% since January and still 11.3% below Zonaprop's record, and closing prices are down 0.4% over 12 months (M² Real survey). So prices are not what got worse.
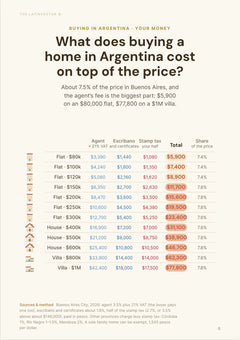
The cash need is. At 75% financing, the one-bedroom needs USD 32,750 from the buyer and the two-bedroom USD 45,000, before buying costs of about 6% to 9% of the price in Buenos Aires City (another USD 7,900 to USD 11,800 on the one-bedroom).
The debate focuses on the monthly payment. For households without dollar savings or family help, the upfront cash kills the deal first.
| Typical Buenos Aires City apartment (Zonaprop, Sept 2026) | Asking price | 25% buyer contribution | 75% mortgage |
|---|---|---|---|
| 40 m² studio | ~USD 110,000 | ~USD 27,500 | ~USD 82,500 |
| 50 m² one-bedroom | ~USD 131,000 | ~USD 32,750 | ~USD 98,250 |
| 70 m² two-bedroom | ~USD 180,000 | ~USD 45,000 | ~USD 135,000 |
 70+pages
This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
Who is actually getting mortgages in Argentina now?
Mostly formal employees in big cities, old enough to have built up savings.
In 2024, 85% of new mortgage borrowers were salaried employees, rising to 86% in December (BCRA).
Age is concentrated too: about 63% of 2025 borrowers were 35 to 49 years old.
So is geography. In 2025, Buenos Aires Province had 34% of new borrowers and Buenos Aires City 28%, Córdoba 9% and Santa Fe 8%. In January–July 2026, Buenos Aires Province (4,874 loans) and the City (4,228) took 63.9% of all loans, ahead of Santa Fe (1,280), Córdoba (915) and Mendoza (791).
Three quarters of new borrowers lived in urban areas with more than 100,000 adults.
That makes sense: banks want documented salaries, stable jobs and homes that are easy to resell. It also shows how selective the comeback is. Young households, informal workers and people outside the big cities are mostly left out.
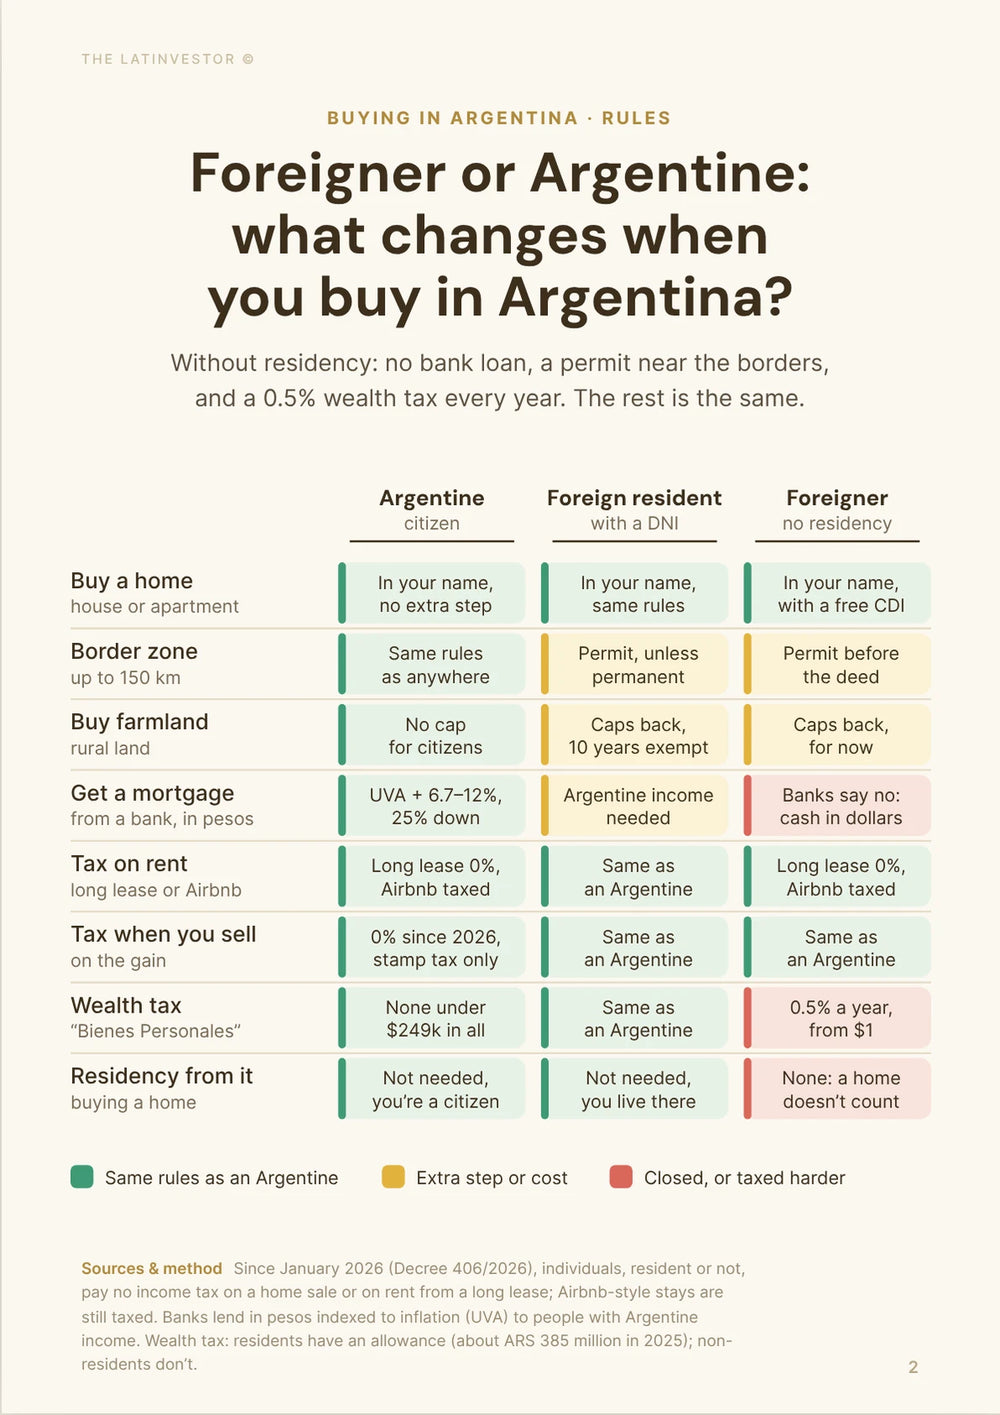
For foreign buyers, the same filter is tighter: banks such as BBVA accept foreigners with a permanent-residence DNI and Argentine income, while a non-resident with only foreign income has no confirmed access to UVA loans.
Is Argentina's mortgage comeback too dependent on public banks?
Yes, and more so in 2026: Banco Nación alone wrote 9,375 of the 14,237 loans from January to July, 65.9% of the total.
BBVA came second with 1,999 loans (14%), and the top three banks made 82.7% of all loans (Tejido Urbano).
In 2025, 44% of new borrowers went to a national public bank and 56% to public banks once provincial ones are added (BCRA).
Public banks restarting a market private lenders had left is not a problem in itself. The risk is what happens if that support fades.
The market is also tiny. Argentina ended 2025 with about 180,000 mortgage borrowers, in a country of more than 46 million. At the end of 2024 the BCRA counted about 150,000, just 0.4% of adults.
Argentina has rebuilt the door to a mortgage market. The room behind it is still small.
Is the current mortgage slowdown getting worse or starting to stabilize?
It has stopped getting worse, and July 2026 looked like the start of a recovery.
Tejido Urbano counts 1,968 new loans in June 2026 and 2,527 in July, up about 28% in a month. That is still far below June 2025 (3,978) and July 2025 (5,125).
The BCRA's September 2026 monetary report also shows mortgage lending growing again month on month.
Loans are bigger. The average loan reached about USD 100,600 in January–July 2026, up 23% in real terms (Tejido Urbano, at the blue dollar in constant 2024 dollars). It swings a lot by month: about USD 90,200 in January, USD 125,600 in June, USD 92,900 in July.
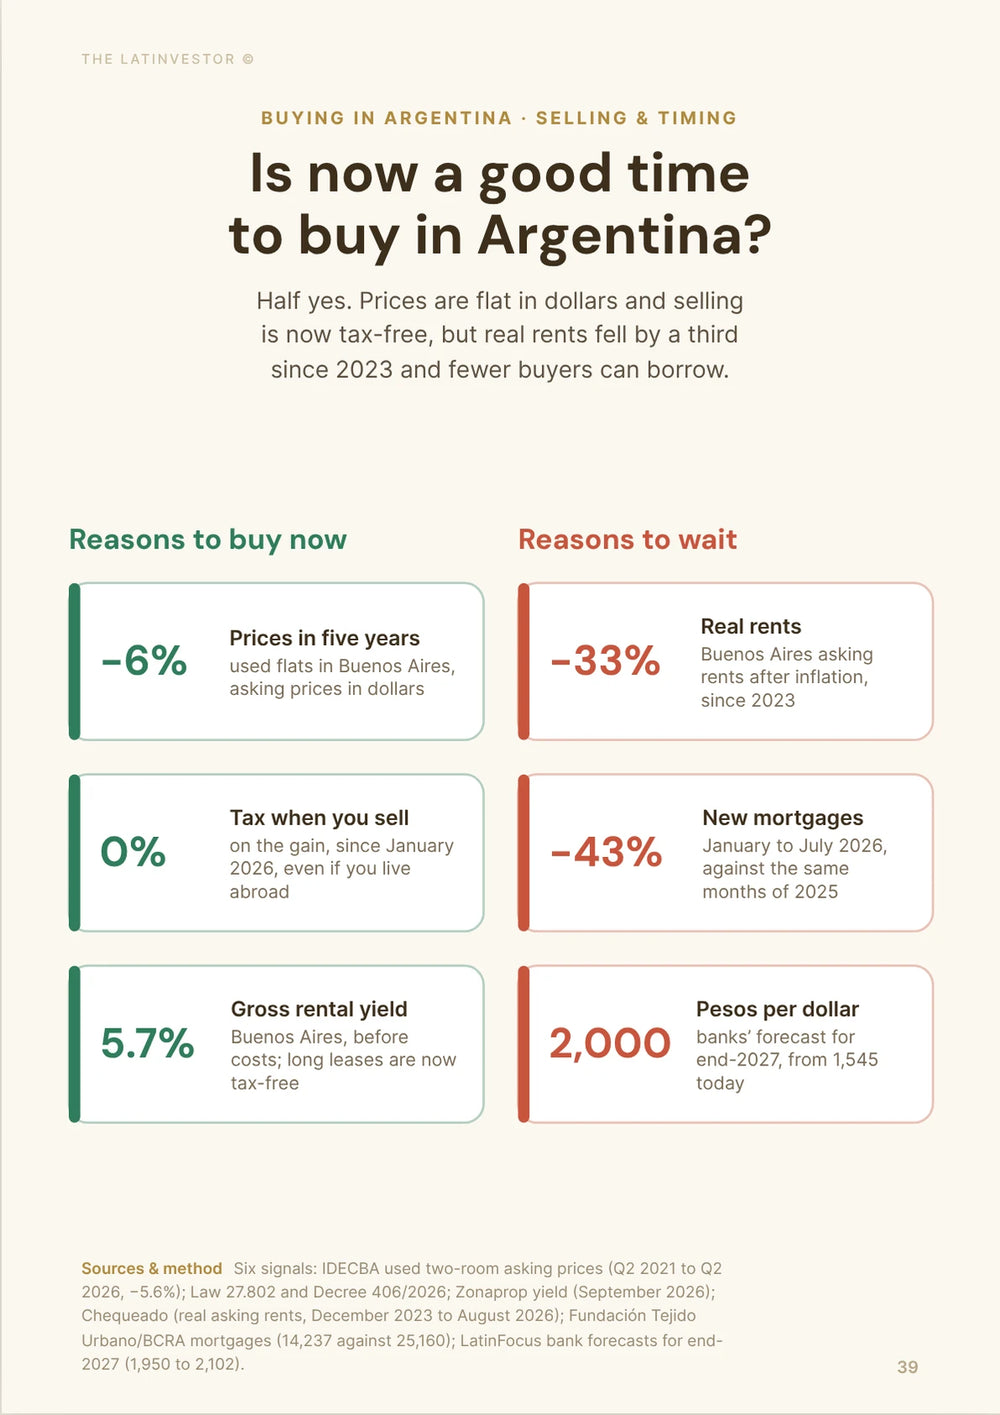
So fewer people borrow, but each borrows more. Rates also came down from the 2025 highs, and fresh state-backed money arrived in September and October.
For now, the market looks like it found a floor around 2,000 to 2,500 loans a month, not like a new collapse.
 70+pages
Is today's Argentine mortgage market safer than the 2017 UVA boom?
Better controlled, yes. The core UVA risk has not gone away.
The last cycle grew very fast. The BCRA counted almost 58,600 new mortgage borrowers in 2017 and 25,500 more in the first quarter of 2018 alone.
Then came another currency and inflation crisis. Payments rose with the index, balances jumped in pesos and governments stepped in again and again with caps and relief.
Both banks and borrowers remember. Income checks are strict, first payments usually stay near 25% of income, and banks lend mostly to formal workers with good credit.
That shrinks the pool of buyers but makes it stronger.
And the old loans did better than their reputation. A BCRA assessment in 2022 found only about 1.6% of UVA mortgage borrowers with some degree of arrears.
The lesson of 2018 is not that UVA loans failed. Borrowers kept paying, but inflation made the debt stressful and politically toxic. Whether Argentina can avoid the next inflation shock is the bigger question.
Can lower inflation finally make Argentine mortgages sustainable?
It gives them their best base in years, but nobody has seen today's loans go through a full economic cycle yet.
INDEC measured 1.9% in September 2026 and 33.4% over 12 months. That is high by world standards, but far from the crisis years.
For a UVA loan, what matters is whether wages keep up. The RIPTE wage index rose to about ARS 1.98 million in August 2026, from about ARS 1.95 million in July.
Steadier inflation lets households predict how fast their payment will move, and lets banks price long loans.
The hard part is time. A loan signed today may still be running in the 2050s, and Argentina has swung between stability and crisis over much shorter periods.
Today's conditions reopened mortgage lending. Whether they will protect a 30-year borrower will take years to prove.
Could dollar mortgages make home loans much easier in Argentina?
For some buyers, maybe. For anyone paid in pesos, they would be a dangerous mismatch.
The appeal is obvious. Homes are priced in dollars, and many households keep their savings in dollars.
Dollar deposits have grown strongly in Argentine banks, so banks have more dollar funding than a few years ago. Lending those dollars against dollar-priced homes sounds simpler than inflation-indexed pesos.
The salary is the problem. Most Argentines earn pesos, so a big devaluation would make a dollar mortgage much harder to pay overnight.
That is why banking rules have long limited dollar lending, mostly to borrowers with dollar-linked income.
Dollar loans could suit exporters and people paid from abroad. They do little for a normal household paid in pesos, which needs stable income and predictable inflation far more.
 70+pages
What would prove that Argentine mortgages are really back for good?
Credit that stays available in bad years as well as good ones, and an ordinary middle-class household that can qualify.
Volume first. The current 2,000 to 2,500 loans a month beat the dead years after 2018 but fall well short of the 2025 peak. Holding 3,000 to 4,000 a month for several years would be more convincing.
Then penetration. Only about 13% to 15% of property deals in Buenos Aires City and Province use a mortgage. There is plenty of room to grow.
Affordability is the hardest test. Credit can't go mainstream while a one-bedroom needs more than USD 30,000 upfront and about ARS 3.9 million of monthly income.
Private banks need a bigger share too. Banco Nación alone wrote about two loans in three in January–July 2026.
And the system has to keep working when inflation, rates, the peso or politics turn rough. If banks are still writing 20- and 30-year loans after the next bad patch, the debate changes.
Will the government's FGS auctions bring cheaper mortgages back?
They add money, not new borrowers. In September 2026 the government started lending up to ARS 2 trillion from the pension reserve fund (FGS) to banks for home loans. The first auction placed ARS 200 billion with 13 banks on 7 September; the second, results published on 6 October, placed another ARS 200 billion with 12 banks.
Loans funded this way must cost at most UVA + 7.5% and run at least 15 years. Banks paid on average UVA + 4.79% for the five-year money in the second auction. The second round also widened eligibility: borrowers who own no home, or own one they don't live in, can now use it to buy, build, extend or renovate.
The two auctions add up to about ARS 400 billion, roughly USD 258 million. At an average loan of about USD 100,600, that funds around 2,500 loans, a small amount next to the 25,160 loans of January–July 2025.
What to do: if you are shopping for a loan, ask your bank whether it won FGS money and whether that line is cheaper than its standard offer. The same income, DNI and job-history checks apply.
What does the strong peso mean for anyone taking a UVA loan now?
If you earn in dollars, your debt got dearer in 2026. Prices rose about 23.6% from January to September (INDEC) while the wholesale dollar rose only about 4.9%, from about ARS 1,455 to ARS 1,526. A UVA balance follows prices, so in dollar terms it grew roughly 18% in nine months.
That is the strong peso at work: Argentina got more expensive in dollars, and so did UVA debt. If the peso weakens (the central bank's September survey of forecasters expects about ARS 1,614 per dollar by end-2026), part of that comes back, but nobody can promise when.
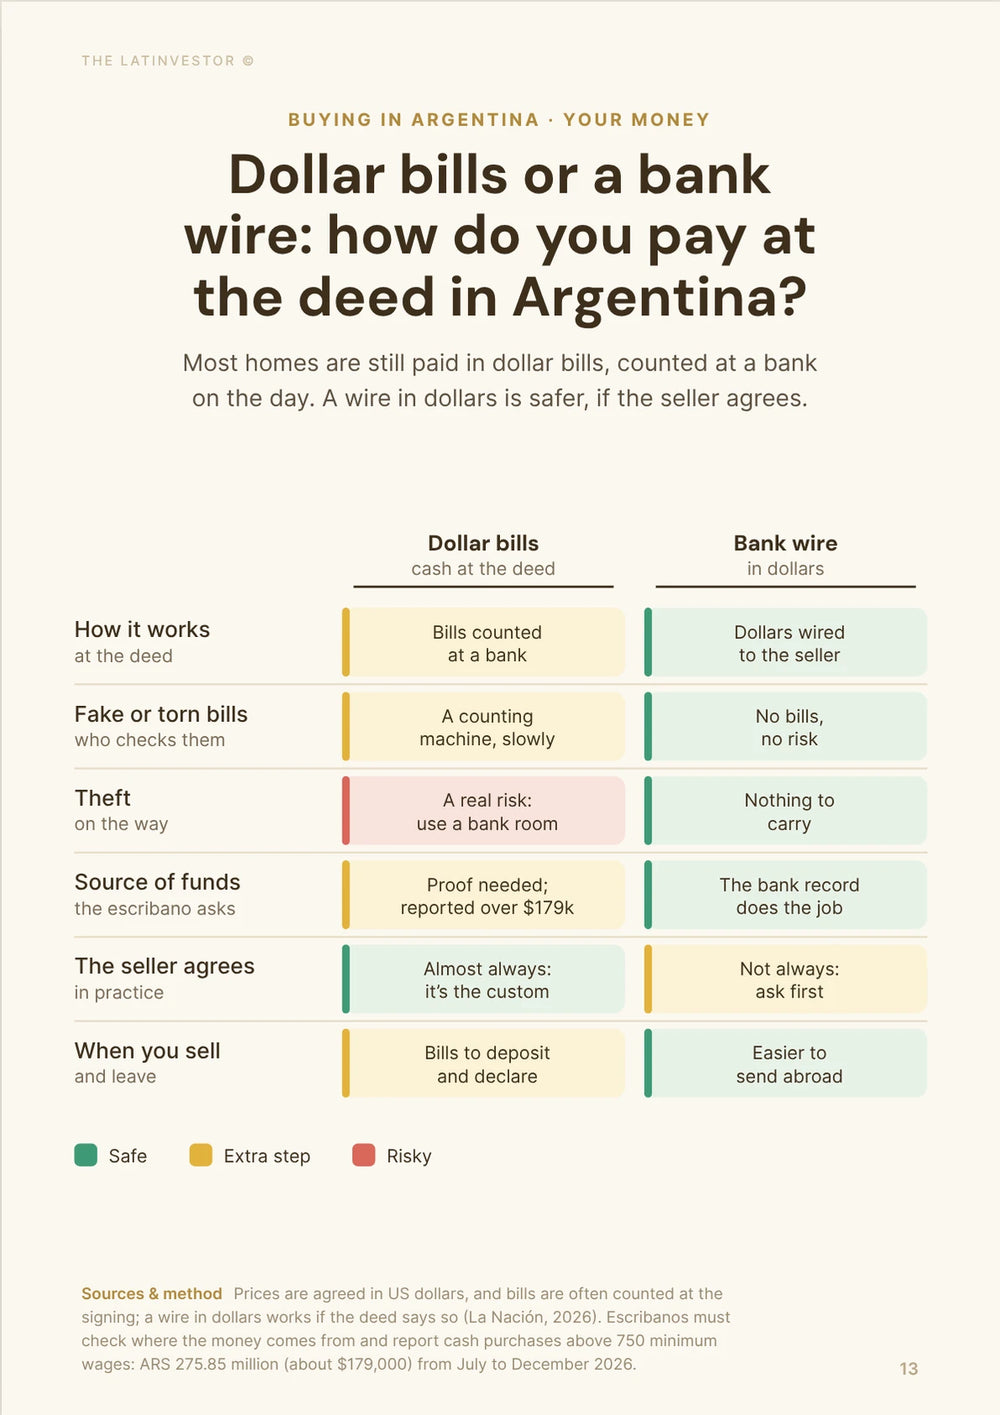
What to do: borrow in UVA only if most of your income is in pesos and rises with inflation. If you earn in dollars or euros, test your budget with the payment 20% higher in dollar terms, keep the loan short and prepay when the peso is weak. A non-resident with only foreign income should plan to pay cash.
 70+pages
Are mortgages finally coming back in Argentina?
Yes. Mortgages are back, but mass mortgage lending is still far off.
The evidence goes well beyond bank announcements. From a few thousand loans a year in 2019–2023, Argentina went to about 10,000 new borrowers in 2024 and 43,700 in 2025. Banks compete on 20- and 30-year UVA loans, and mortgages again finance a visible share of purchases.
2026 stops us from calling it normal. New loans fell 43% in January–July, while Buenos Aires City sales barely moved (-2.3% to August), so the problem is financing, not demand. Rates are above the 2024 launch deals, income tests are tough, down payments are large next to local wages, and Banco Nación writes about two loans in three.
Scale is the clearest reality check: about 180,000 mortgage borrowers at the end of 2025 in a country of more than 46 million.
Still, compared with three years ago, it's a big change. Someone with a strong formal income, savings for the down payment and a salary account at the right bank can again finance a home over 20 or 30 years. July's 2,527 loans and the FGS money suggest the floor is holding.
The next step is harder: making credit ordinary for the middle class and tough enough to survive the next shock. For now, mortgages are back; the mortgage culture Argentina lost decades ago is still being rebuilt.
Our methodology
This article checks whether mortgages are really back in Argentina in 2026: loan volumes and momentum, the share of purchases financed with credit, bank terms and rates, affordability for local households, who borrows, the weight of public banks, and how durable the comeback looks.
Loan volumes come from the BCRA (new borrowers in 2017, 2024 and 2025, borrower profile, public-bank share) and from Fundación Tejido Urbano's compilation of BCRA data (loans January–July 2026, monthly loans, average loan, bank and province shares, Buenos Aires Province deeds), as reported in September 2026. Buenos Aires City deeds come from the Colegio de Escribanos (January–August 2026). Rates, terms and financing come from the banks' own pages (Banco Nación, Banco Ciudad and BBVA, October 2026) and, for older offers, iProfesional's April 2026 comparison; 2025 rates from La Nación. Prices come from Zonaprop's September 2026 index and the M² Real closing-price survey; wages from the official RIPTE series (August 2026); payments are our own French-amortisation calculation at the first month, before insurance and fees.
Inflation comes from INDEC; the FGS auctions from official results reported in September and October 2026; the 2022 arrears figure from the BCRA Financial Stability Report; buying costs and foreign-borrower rules are those used across our Argentina articles.
We checked these figures in October 2026. Peso amounts are converted at about ARS 1,550 per US dollar (official and MEP rates were within 1% of each other on 22 October 2026, the blue rate about ARS 1,570), and euro amounts at about ARS 1,740 per euro.
Where we had no direct figure, we say so: we found no consistent 2019–2023 annual series, so we describe that period as a few thousand loans a year; BCRA borrower counts and Tejido Urbano loan counts differ slightly; the 2025 share of Buenos Aires City deeds with a mortgage is derived from the published changes; and the dollar growth of a UVA balance is an estimate from inflation and the wholesale dollar, not a bank figure.
Key sources used for this analysis include BCRA Financial Inclusion Report, second half 2024, BCRA Financial Inclusion Report, second half 2025, BCRA on new mortgage borrowers in 2025, BCRA monetary report, September 2026, Revista Mercado on Tejido Urbano's 2026 mortgage data, Tejido Urbano's August 2026 mortgage monitor, Colegio de Escribanos on Buenos Aires City deeds to August 2026, Banco Nación mortgages, Banco Ciudad first-home loans, BBVA Argentina mortgages, iProfesional's April 2026 mortgage-rate ranking, La Nación's September 2025 mortgage-rate review, Bloomberg Línea on the second FGS auction, iProfesional on the first FGS auction, RIPTE wage series, Infobae on INDEC's September 2026 inflation, Infobae on the dollar in October 2026, Revista Mercado on Zonaprop's September 2026 index, BCRA Financial Stability Report, first half 2018 and BCRA Financial Stability Report, second half 2022.