
Summary
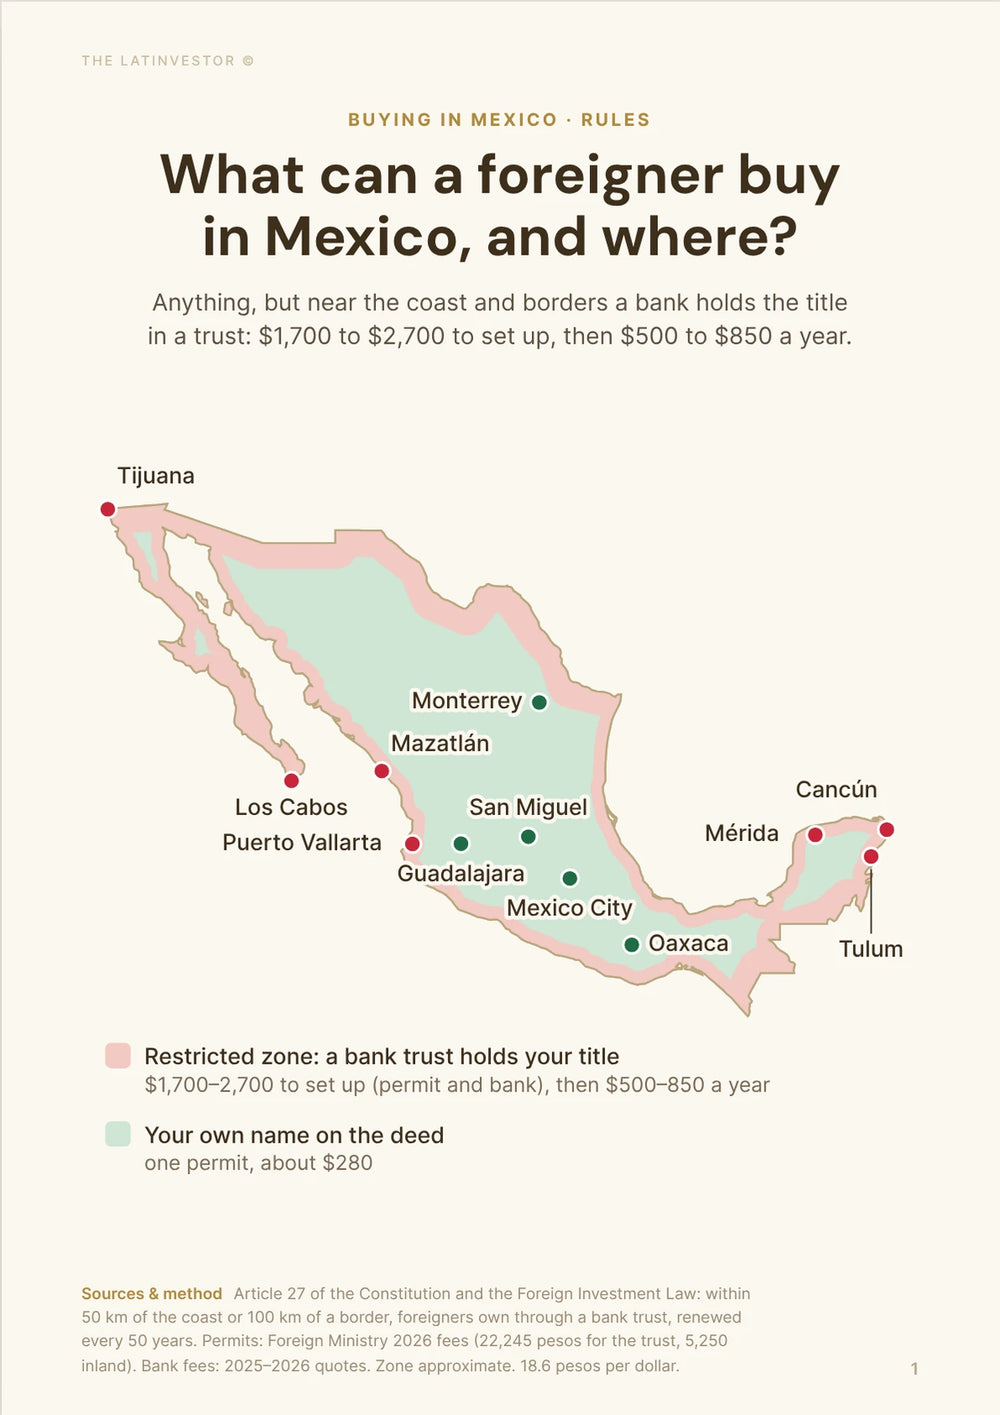
Yes, a foreigner can buy a condo, a house or a residential lot in Tijuana, but not in their own name: the whole city sits inside the 100 km strip along the US border, so you hold the property through a bank trust (fideicomiso) that runs for up to 50 years and can be renewed.
The trust has a price. The SRE permit alone is MXN 21,650 (about USD 1,160), banks charge roughly USD 550 to USD 800 to open the trust, and then about USD 550 to USD 700 every year.
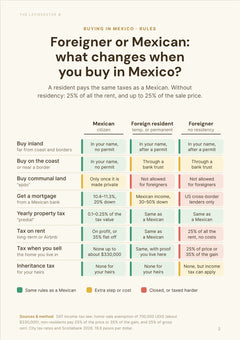
The trust also handles inheritance: you name beneficiaries in it, and Mexico has no federal tax on inheritances (0%).
The biggest mistake is paying on a private contract or a developer receipt before the trust, the deed and the registry filing are under control. Prices rose 9.7% in a year (SHF, first half of 2026), which pushes buyers to rush.
Title fraud is a live issue, not a theory: on August 4, 2026, two former deputy registrars and an analyst of the state property registry were arrested over fraudulent property transfers.
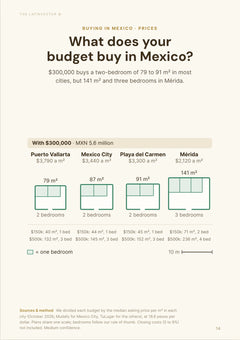
You don’t need a visa to buy. But buying won’t get you residency unless the property is worth about MXN 10.76 million (about USD 578,000), roughly twice the median asking price of a 3-bedroom house in Tijuana (USD 278,000).
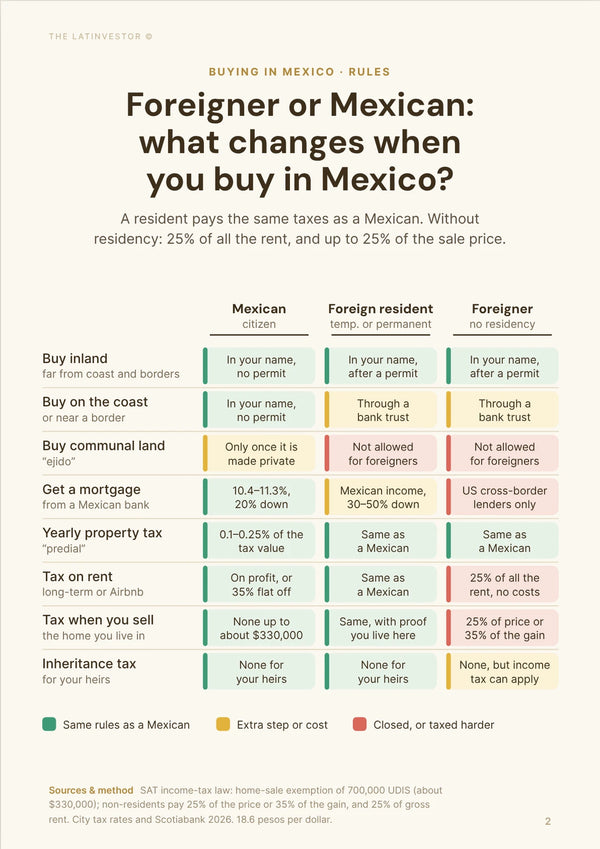
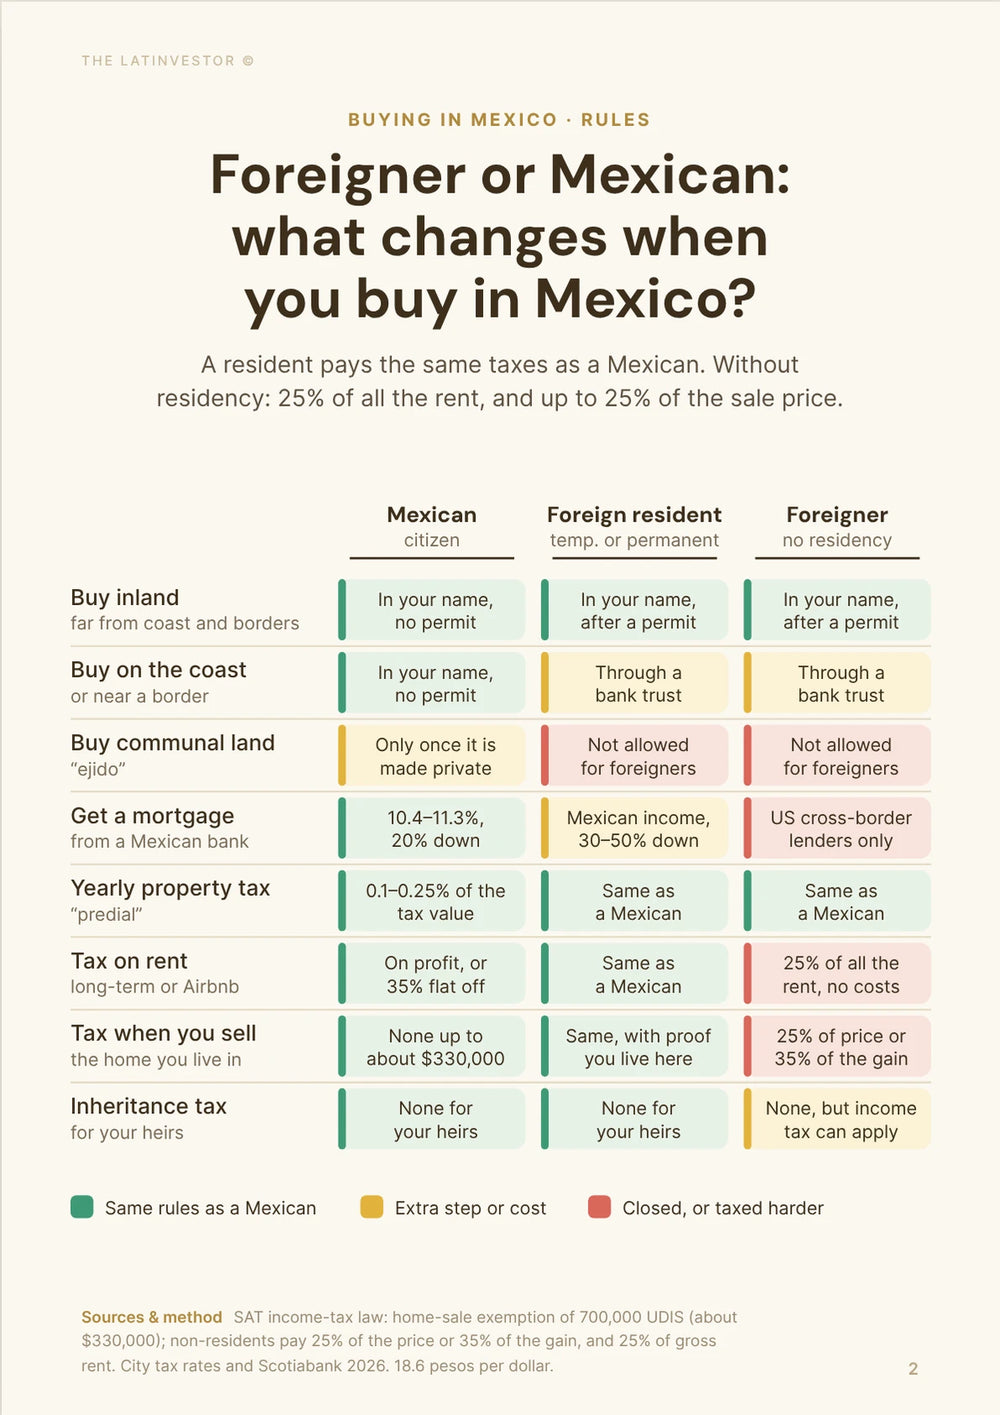
You can rent the place out from San Diego or anywhere else, but a non-resident landlord pays 25% of the gross rent in Mexican tax.
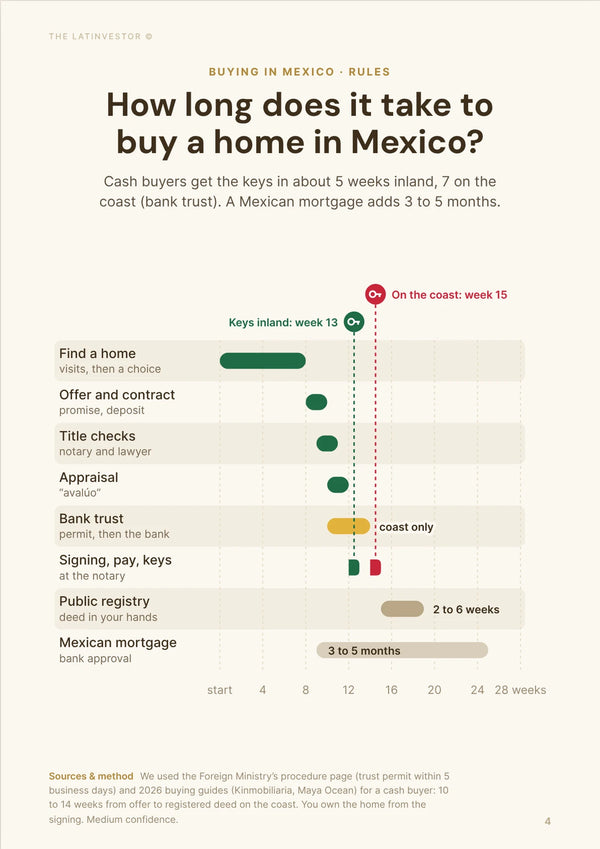
A clean purchase usually takes 6 to 12 weeks from accepted offer to registered deed, and the notary is the one step you can’t skip.
Before signing, check title history over 10 to 20 years for older houses, get the official certificate of no liens, and confirm land use with the city.
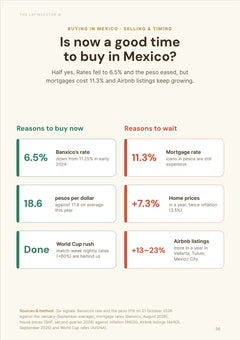
Mortgages exist but they’re hard to get: banks granted new loans at 9.99% on average in June 2026, and cross-border lenders usually finance only 50% to 65% of the price.
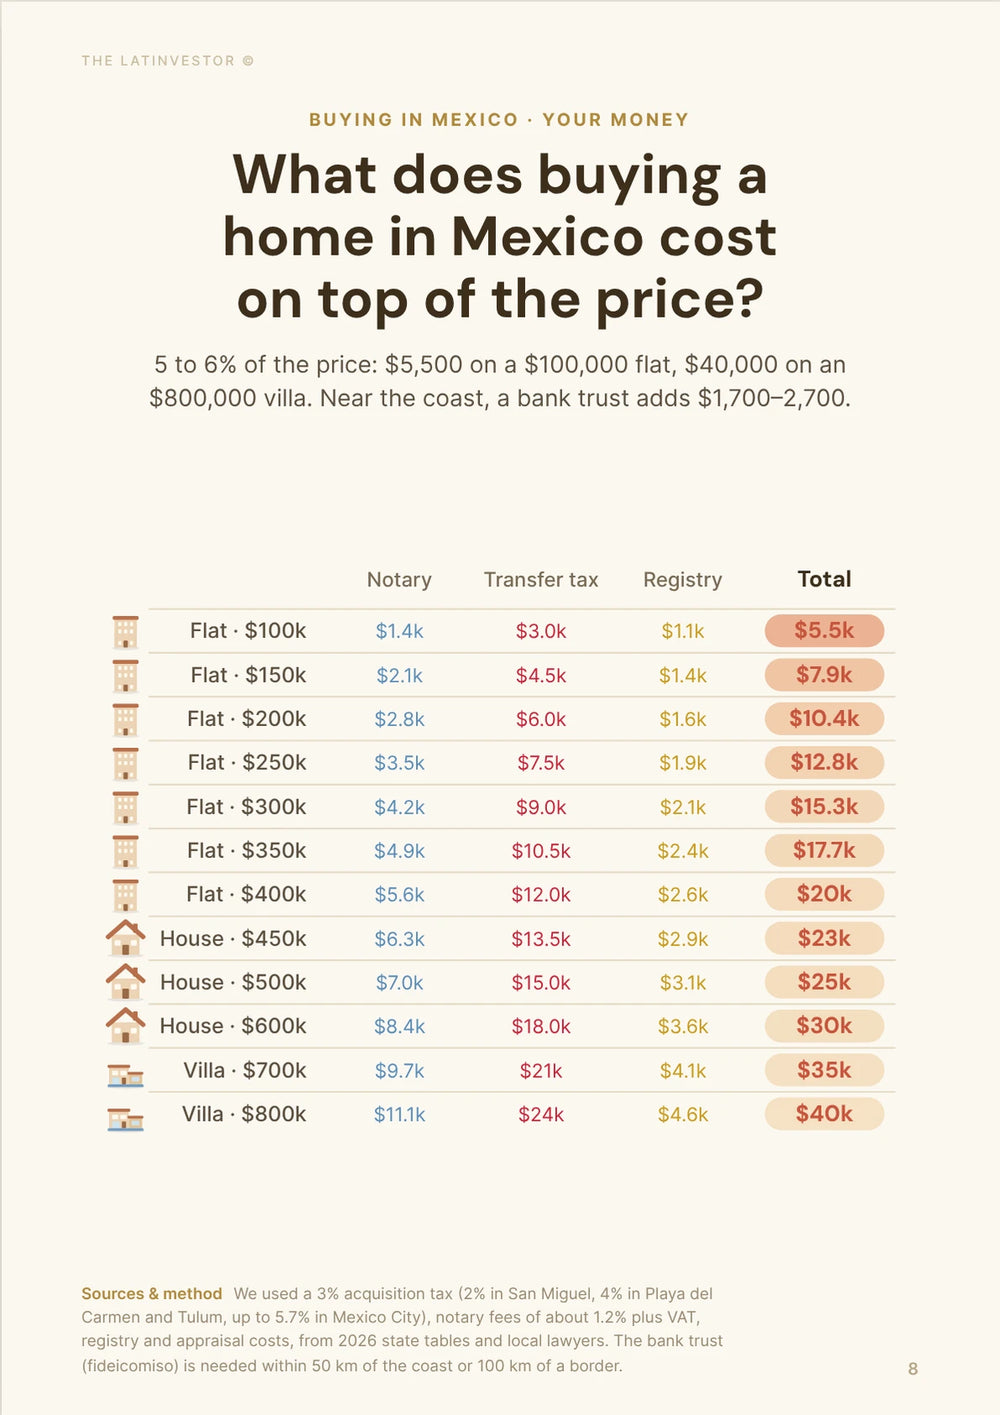
Budget 7% to 11% of the price for closing costs, or MXN 210,000 to MXN 330,000 on a MXN 3 million home.
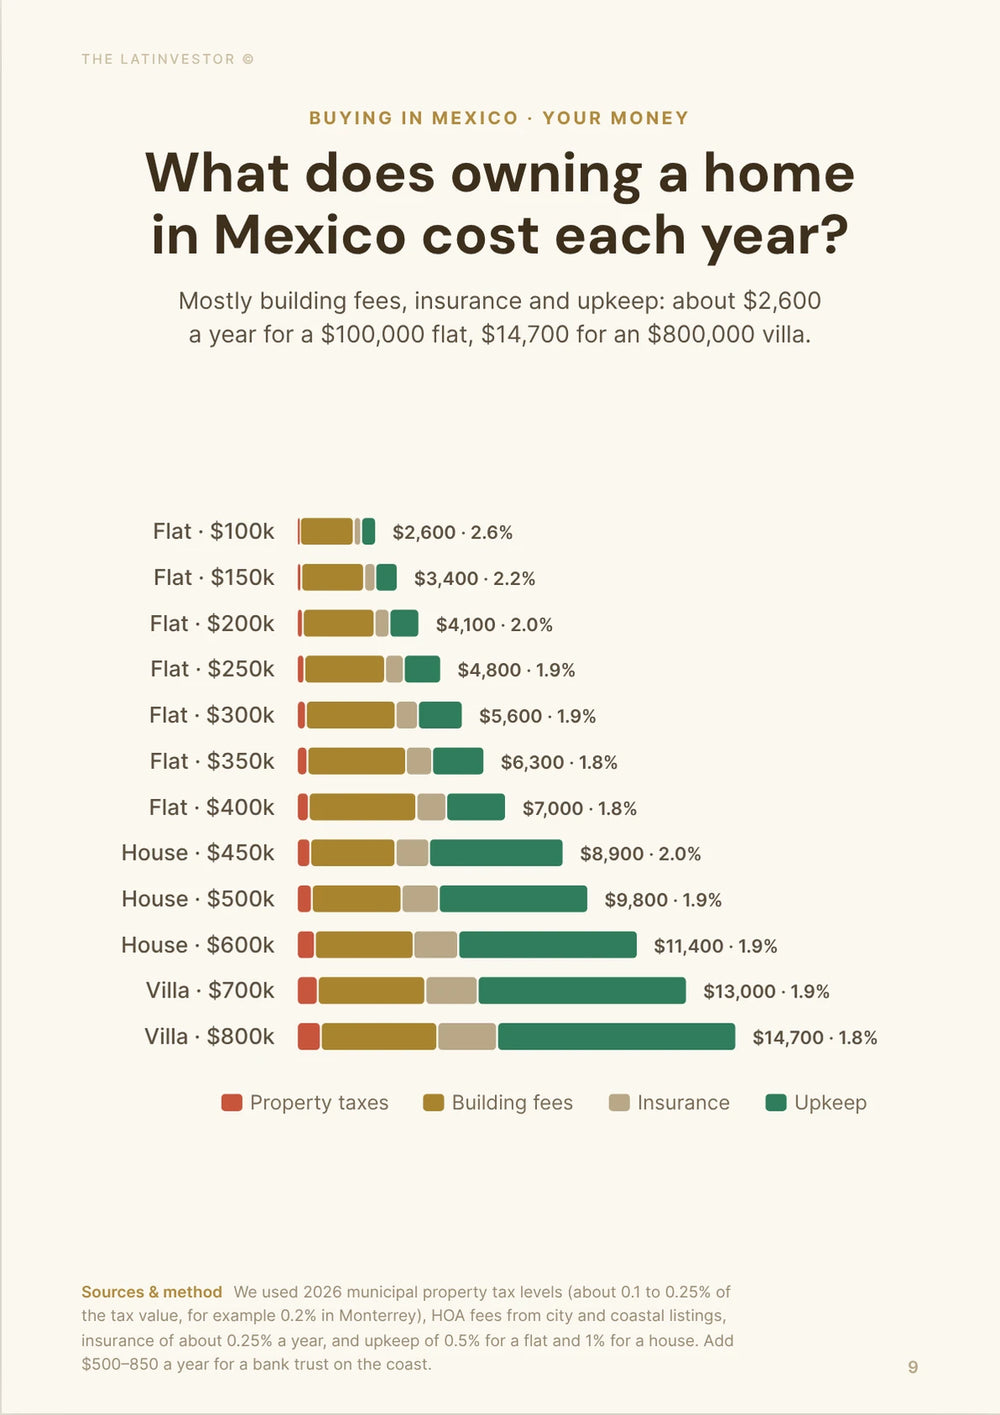
Yearly costs stay low: predial of about MXN 6,400 to MXN 15,000 on a MXN 3 to 5 million home, plus the trust fee and insurance.
If you’re a US taxpayer, the IRS doesn’t treat a standard fideicomiso as a foreign trust, so no Form 3520 just for holding the home.
Bottom line: buying in Tijuana as a foreigner is routine. Budget for the trust from day one, and put your energy into checking the title and the people you pay, not the paperwork.

What do you actually own when you buy in Tijuana?
What property types can foreigners buy?
Foreigners can buy condos, apartments, houses, townhouses, gated-community homes and regularized residential lots in Tijuana.
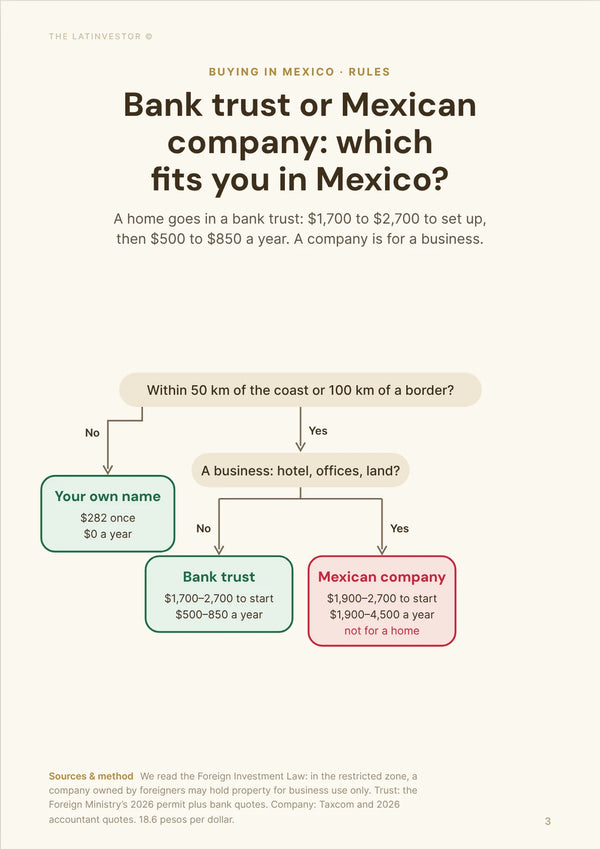
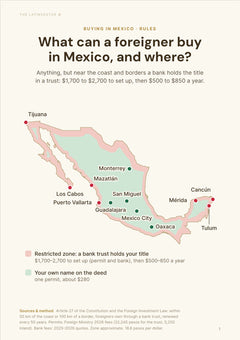
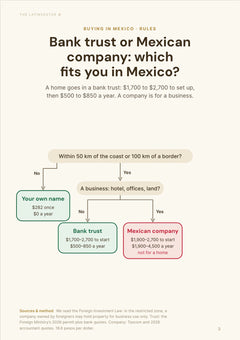
The catch: Tijuana is inside Mexico’s restricted zone, the 100 km strip along the US border. So a foreign individual buys a home through a Mexican bank trust (fideicomiso), not with direct title.
With the trust, you can live in the home, rent it out, renovate it, sell it, or leave it to the beneficiaries you named.
The type of property matters less than the paperwork: a condo in Zona Río, a house in Playas de Tijuana or a townhouse in Otay all need a clean deed, the bank trust, a notary and registration at the Baja California public registry (RPPC).
Can I own land in my own name?
No. A foreign individual can’t hold direct title to residential land in Tijuana, because the city is within 100 km of the US border.
With a fideicomiso, a Mexican bank holds the title and you are the beneficiary, with full practical control of the home.
That applies even to ordinary city property: a condo in Cacho, a house in Chapultepec or a lot in a gated community near Playas de Tijuana.
What other foreign-ownership rules should I know?
There’s no limit on the number of foreign owners in a condo building. What matters is that the SRE permit, the trust deed and the property description match exactly, including parking, storage and common areas.
The SRE permit costs MXN 21,650 (about USD 1,160), and the bank and notary usually handle it during closing. Banks then charge about USD 550 to USD 800 to open the trust and USD 550 to USD 700 a year to run it.
A Mexican company isn’t a shortcut for a personal home: companies can hold property for business use, not to get around the trust for a house you live in.
Paying isn’t enough to be safe: the deed and the trust must be recorded at the RPPC. No reform in 2025 or 2026 has removed the restricted zone, so plan around the 50-year renewable trust.
What’s the biggest ownership mistake foreigners make?
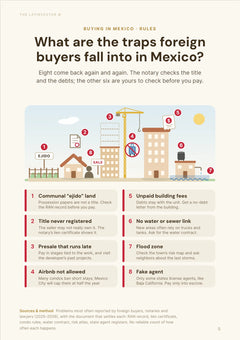
Handing over money on a private contract, a developer receipt or a seller’s promise before the trust, the deed and the RPPC registration are under control.
The pressure to move fast is real: home prices in Tijuana rose 9.7% in a year (SHF, first half of 2026). But if a lien, a seller problem or a paperwork gap shows up later, you may have paid for a home without clean, enforceable rights to it.
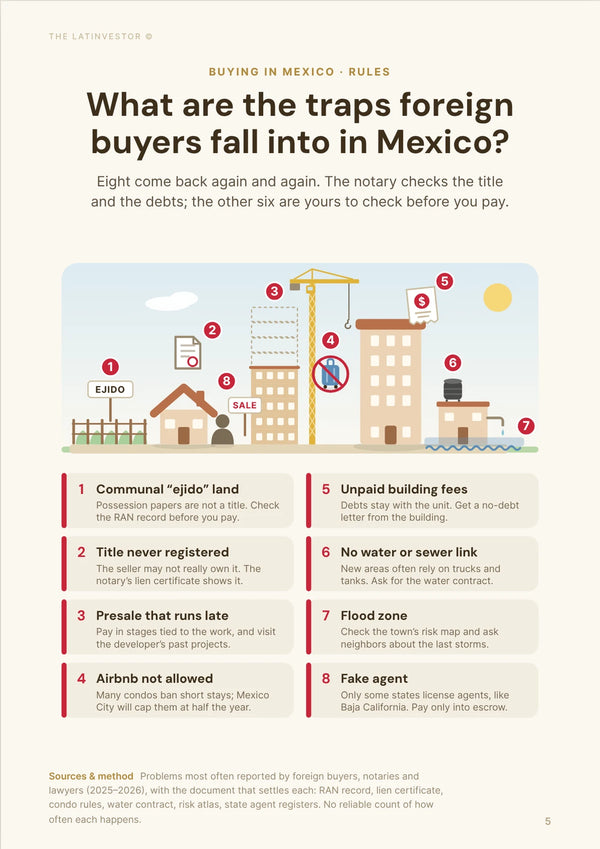
Other classic Tijuana traps: cheap hillside lots, “ready to regularize” land, missing condo documents, unpaid predial, old mortgages never cancelled at the registry, and homes whose real size doesn’t match the cadastre.
 Buying in Mexico as a Foreigner
Is property fraud a real risk in Tijuana right now?
Yes. In 2026 the problem reached the public registry itself: on August 4, 2026, Baja California prosecutors arrested two former deputy registrars and an analyst of the state property registry over property transfers investigators call fraudulent. One was held in pretrial detention; the other two were released and the prosecutor appealed.
The cases reported by ZETA in September 2026 show how it works: a simulated sale of a Tijuana home with contradictory dates, a non-existent CURP and an allegedly fake voter ID, and a mortgage cancellation signed by a “Notaría 22” in Campeche that doesn’t exist. Good addresses aren’t immune: one simulated sale was recorded on a home in Jardines de Agua Caliente, and dozens of owners across 12 towers at Campestre Murúa were dispossessed in January and February 2026. In June 2026, the state also opened an administrative investigation into four Tijuana civil judges accused of favoring fraudulent property claims.
At street level, Tijuana’s AMPI realtors’ association warned in May 2026 about sellers who won’t let you inside, quick tours that keep you away from neighbors, and pressure to close before the documents are checked.
What to do: pick the notary yourself and check they exist and practice in Baja California; ask for a fresh registry certificate a few days before signing, not one the seller hands you; talk to the neighbors or the gated community’s administrator; check the agent in the Secretaría de Economía’s register; and never wire a deposit to a personal account the notary hasn’t confirmed.
Does your visa matter when you buy or rent out in Tijuana?
Do I need a specific visa to buy property?
No. A tourist can buy a home in Tijuana, and many buyers start the process on a visit from San Diego.
The real friction for non-residents is practical: banks, trustees and notaries move faster when you have an RFC (Mexican tax ID) and a Mexican address history.
The RFC isn’t what makes the purchase legal, but get one early: it makes rental income, invoices, bank paperwork and resale much easier.
A typical buyer file: passport, immigration document or residency card, proof of address, marital status papers, tax details if you have them, and whatever the bank trustee and notary ask for.
Does buying property in Tijuana get me residency?
Not on its own. A purchase can support a temporary residence application, but it doesn’t give you residency or citizenship automatically.
The property route asks for a high value. Consulates quote a deed value of about MXN 10.76 million (91,710 times the daily UMA), or about USD 578,000, and each consulate reviews the file case by case.
That’s roughly twice the median asking price of a 3-bedroom house in Tijuana (USD 278,000), so most buyers qualify through income or savings instead: about MXN 79,800 a month in net income (about USD 4,290), or about MXN 1.34 million in average savings (about USD 72,300), for temporary residence in 2026.
Can I legally rent out my property in Tijuana on my visa?
Your visa doesn’t stop you from earning rent from a Tijuana home, and you don’t need to live in Mexico to do it. Many owners use a property manager while living in San Diego or elsewhere in the US.
What changes is the tax setup: long-term rent, platform rentals, RFC registration, invoices, withholding and VAT each come with their own steps.
Don’t buy for Airbnb on autopilot: active short-term listings in Tijuana fell 43.9% between September 2025 and September 2026, according to AirDNA.
 70+pages
How long does a purchase in Tijuana take, from offer to deed?
What are the steps to buy property in Tijuana?
The usual sequence: pick a home with regular private title, agree terms, hire a notary and a lawyer, check the RPPC and the cadastre, request the SRE trust permit, set up the trust, sign the deed, pay the closing costs, register the deed and update city records.
You don’t have to be in Tijuana to sign. A properly drafted and legalized power of attorney usually lets a representative sign for you.
Signing before the notary is what makes the deal legally serious, but registration at the RPPC is what gives you the strongest public protection.
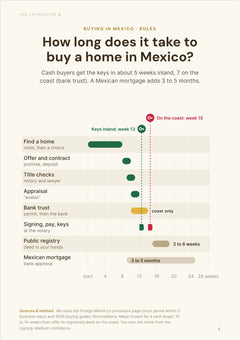
A clean purchase usually takes 6 to 12 weeks from accepted offer to registration. The bank trust, missing documents, liens, condo papers or a messy seller file make it longer.
Do I need a lawyer or a notary to buy a property?
The notary is required to formalize and register the purchase. A private lawyer isn’t legally required, but foreign buyers should hire one.
The notary prepares the deed, collects the taxes, sets up the trust and files the registration. Your lawyer works only for you and checks what the seller and the agent won’t.
Put it in writing that the lawyer checks the trust wording, substitute beneficiaries, title, liens, condo documents, the cadastral match, zoning and the seller’s authority to sell. Notary and closing fees usually run 1% to 2.5% of the price in Tijuana.
How do you avoid buying a problem property in Tijuana?
How do I verify title and ownership history?
Check title at the Baja California public registry (RPPC), and use Tijuana’s cadastre for the physical details of the property.
Ask for the deed or trust deed with its RPPC “folio real”, then match the seller, the property description, the cadastral key, the surfaces and, for a condo, the condo documents.
Look back at least to the previous transfer, and 10 to 20 years for older houses, hillside homes or lots that look irregular.
Stop the purchase if the seller, the registry record, the cadastral surface, the actual building or the property the agent showed you don’t match. Given the 2026 registry arrests, a recent transfer with odd dates or an out-of-state notary deserves a second look too.
How do I confirm there are no liens?
Have the notary request an RPPC certificate and review the folio real, then check city tax and other debts before closing.
Ask about old mortgages that were paid off but never formally cancelled at the registry: they are the most common surprise.
The proof you want is the certificate of no liens (certificado de libertad de gravamen), plus up-to-date predial and no-debt proof for that exact property.
How do I check zoning and permitted use?
Go to the city’s Dirección de Administración Urbana, using the municipal zoning regulation and the land-use (uso de suelo) procedure.
Ask for the land-use confirmation for that exact property, not a general statement about the neighborhood from the seller.
The usual Tijuana trap: assuming a house can become several rental units, a business or a short-term rental without checking density, parking, neighborhood rules and land use.
 70+pages
Can a foreigner still get a mortgage in Tijuana?
Do banks lend to foreigners for homes?
Yes, but it’s harder than for Mexican residents, and most foreign buyers still pay cash.
Banks aren’t lending more either: the number of new mortgages in Mexico rose just 0.3% in the first half of 2026, and the amount lent fell 0.1% in real terms, while Tijuana prices rose 9.7%.
Residents with Mexican income, an RFC and a credit history get the best terms. Non-residents usually go through cross-border lenders, which finance about 50% to 65% of the price, so plan on putting down 35% to 50%.
Which banks are most foreigner-friendly?
Start with Scotiabank, BBVA and HSBC, then try Santander and Banorte depending on your profile.
What makes a bank “foreigner-friendly” is its willingness to look at foreign income, residency status, RFC, the property and the trust without rejecting the file early.
Without Mexican residency, expect more documents, lower loan amounts and more scrutiny, or financing arranged outside the Mexican system.
What mortgage rates are foreigners offered?
No public figure tracks rates for foreigners alone. The benchmarks: banks granted new mortgages at 9.99% on average in June 2026 (ABM), and Banxico’s average fixed-rate quote was 11.31% in August 2026.
A resident with a solid file should get something close to that; non-residents and unusual properties pay more.
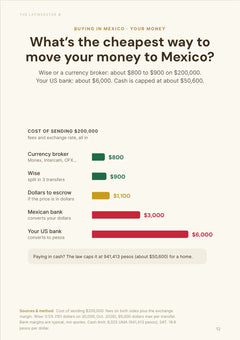
Stick to fixed rates in pesos. Variable-rate or cross-border loans can look cheaper at first, but you carry currency and reset risk, and the peso swings fast: under 17 per dollar in early September, about 18.6 in October, against a 19.20 average in 2025.
How much do you pay to buy and keep a home in Tijuana?
What are the total closing costs?
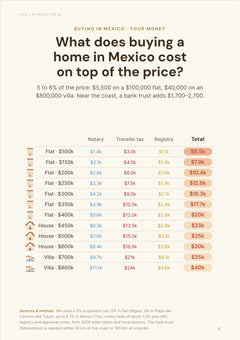
Plan on 7% to 11% of the price. On a MXN 3 million home (about USD 161,000), that’s roughly MXN 210,000 to MXN 330,000 (about USD 11,300 to USD 17,700).
It can drop to about 5% for a cash resale where you take over the seller’s trust, and reach about 14% with a new trust, a loan and paperwork fixes.
The biggest item is the ISAI transfer tax, which is progressive in Tijuana: about 1.8% on a MXN 1.5 million home, 2.3% on MXN 3 million and 4% on MXN 10 million. Many guides still say a flat 2%, which has been wrong since 2021.
Then come notary fees, registry, appraisal, certificates and, for foreigners, the SRE permit and the bank’s trust setup fee.
What annual property tax should I budget?
Predial in Tijuana is about 0.43% of the cadastral value, with a minimum of about MXN 468 a year in 2026.
Cadastral values are usually well below market prices, so a home worth MXN 3 to 5 million typically pays about MXN 6,400 to MXN 15,000 a year (about USD 344 to USD 806, or EUR 306 to EUR 718).
Add the trust fee (USD 550 to USD 700 a year), which often costs more than the predial itself.
How is rental income taxed for foreigners?
A non-resident landlord pays 25% of the gross rent, with no deductions for repairs, management or interest.
Mexican tax residents are taxed on net income at progressive rates, with real expenses or a flat 35% deduction, which usually ends up lower.
For short-term rentals, platforms withhold 4% income tax if you give them an RFC (20% if you don’t), 16% VAT applies, and guests pay Baja California’s 5% lodging tax.
How much does home insurance cost?
PROFECO’s 2026 comparison found policies from about MXN 4,910 to MXN 25,900 a year (about USD 264 to USD 1,390) for a home insured at about MXN 4 million.
The usual cover is fire and basic damage, with earthquake, liability, contents and mortgage-required life insurance added when needed.
In Tijuana, the price mostly depends on the insured value, construction quality, hillside exposure, earthquake cover and whether you rent the place out.
 70+pages
Do Americans have to report a Tijuana fideicomiso to the IRS?
Not as a foreign trust. Since Revenue Ruling 2013-14, the IRS treats a standard Mexican fideicomiso, where the bank only holds title and acts on your instructions, as direct ownership, so you don’t file Forms 3520 or 3520-A just for holding the home.
Bank accounts are a different story. If you open a Mexican account to collect rent or pay bills and your foreign accounts top USD 10,000 combined at any point in the year, the FBAR applies.
Rental income and the gain on a sale still go on your US return. Keep the receipts for the 25% Mexican tax you pay, since it can usually be credited against US tax on the same income.
What to check: that your trust contract is a plain one (if the trustee gets broader powers, the 2013 ruling may not cover it), and that your US tax preparer knows about the property before your first rent check.
Our methodology
This article explains what a foreigner can legally own in Tijuana, how the bank trust works, what visas change, how a purchase runs, which checks to make, how financing works, what buying and owning cost, and what US buyers report to the IRS.
The rules come from official sources first: the Foreign Investment Law, SRE pages on restricted-zone trusts and their fees, the Income Tax Law and SAT, Banxico, consular visa guidance, and Tijuana’s 2026 revenue law, cadastre, land-use office and the Baja California public registry. Where no official number exists, such as bank trust fees, cross-border loan terms or notary fees, we used recent 2026 market sources.
Market figures come from the SHF price index (first half of 2026), asking-price medians from listing portals, AirDNA (twelve months to September 2026), BBVA Research for mortgage volumes and PROFECO for insurance. The closing-cost and ISAI figures match our line-by-line breakdown of Tijuana’s 2026 tariffs. The fraud section relies on dated local reporting by ZETA and El Imparcial.
We checked these figures in October 2026 and converted amounts at about 18.6 pesos per US dollar and 20.9 pesos per euro.
Some limits: asking prices aren’t sale prices, consulates apply residency thresholds case by case, bank fees and rates change with each file, and predial and insurance ranges are planning estimates. People named in fraud investigations are presumed innocent. Have a Mexican notary, a lawyer and your accountants on both sides of the border confirm your own case.
Key sources used for this analysis include: SRE restricted-zone trust permit, SRE costs and timing, the Foreign Investment Law, the consular guide to buying property in Mexico, Mi Consulado temporary residence, 2026 residency solvency figures, Tijuana 2026 revenue law, Baja California Congress publication, Tijuana Catastro, Baja California RPPC, RETYS lien certificate, Tijuana land-use office, Tijuana zoning regulation, SAT arrendamiento regime, Mexico Income Tax Law, Banxico mortgage-rate data, CONDUSEF mortgage simulator, BBVA Research, Homia’s 2026 fideicomiso fee comparison, Global Property Mortgages, Sociedad Hipotecaria Federal, AirDNA Tijuana, PROFECO, ZETA on registry fraud (September 2026), El Imparcial on AMPI’s fraud warning (May 2026), US reporting rules for fideicomisos and Calcu.mx exchange-rate history.