Summary
Yes, selectively: prices are still rising (+7.3% a year in the second quarter of 2026), but the boom is cooling, so a buyer who pays cash and picks a solid property has more room to negotiate than a year ago.
Homes are still beating inflation by a wide margin: 7.9% price growth in the first half of 2026 against 3.45% consumer inflation in September.
The odd part is credit. BBVA counted only 0.3% more mortgages in the first half of 2026 than a year earlier, while new-housing inventory jumped 34.6% in 2025. Prices are rising on a market that isn't borrowing more.
Mortgages are still expensive. Banxico's average fixed-rate mortgage quote was 11.31% in August 2026, even though the policy rate is down to 6.50%, and most analysts expect no further cut in 2026.
Waiting for cheaper loans rarely pays. On a MXN 2.4 million loan, one point less in interest saves about MXN 1,600 a month, while a 5% price rise on a MXN 3 million home costs MXN 150,000.
The peso has just weakened, from just under 17 per dollar in early September to about 18.6 in late October. A MXN 5 million home now costs about US$269,000 instead of roughly US$294,000.
Dollar buyers should not bet on the peso weakening much further: most end-2026 forecasts sit between 17.3 and 18.2 per dollar.
Mexico City is the easier long-term buy: prices rose 4.6% in the first half of 2026, against 11.1% in Guadalajara and 9.7% in Tijuana.
Resort markets need much more caution. Los Cabos (+96%), Cancún (+94%) and Playa del Carmen (+90%) almost doubled in the five years to the end of 2025.
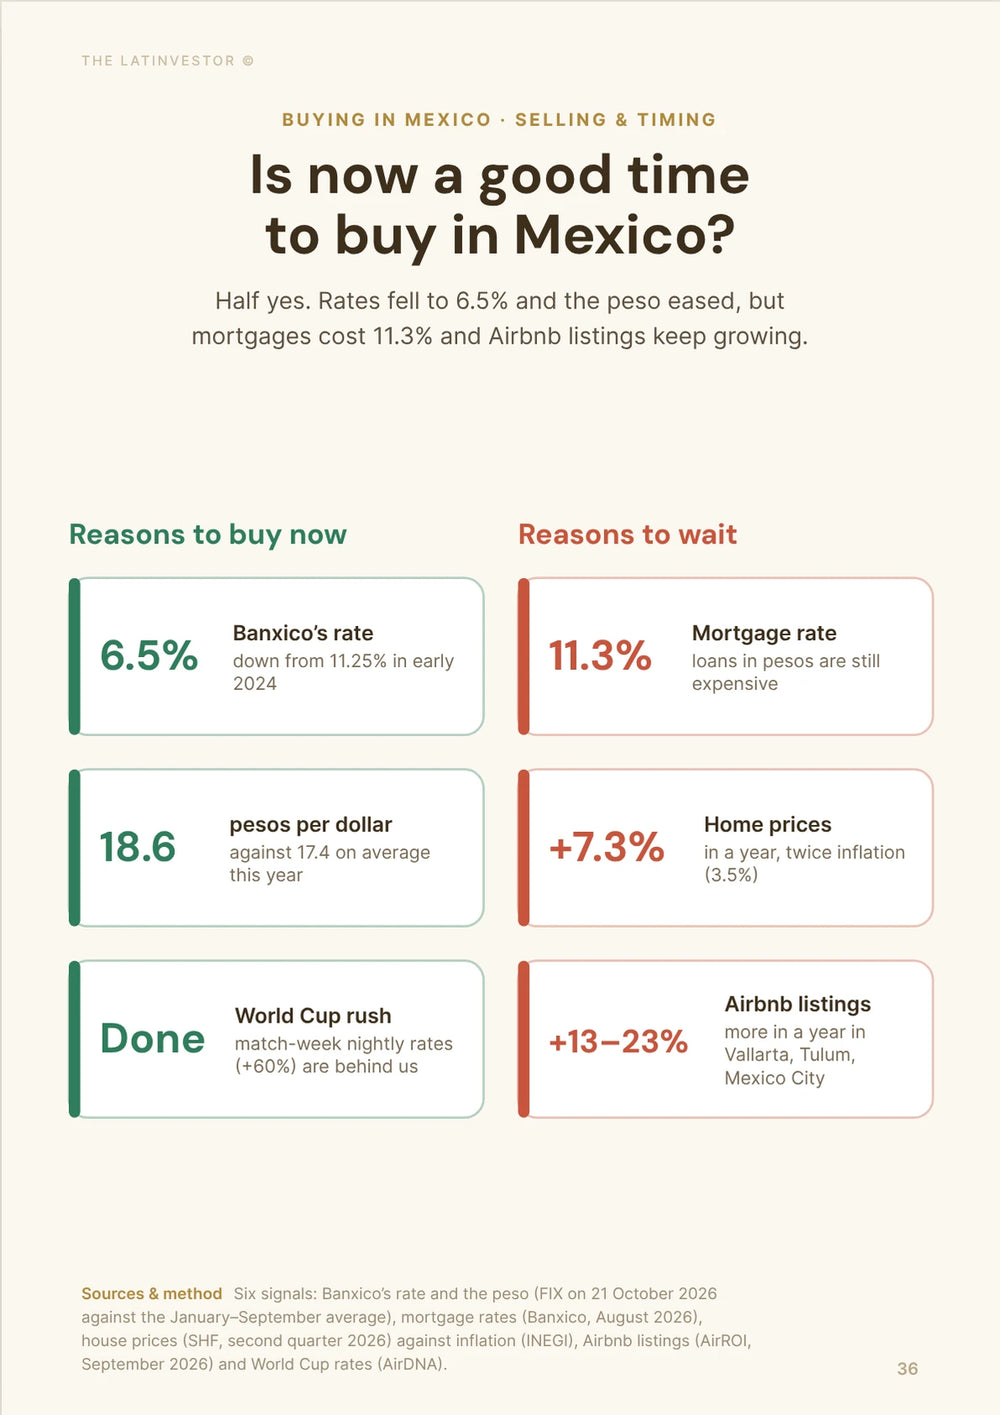
Rents favor cash buyers. Gross yields average 5.79% nationally and 6.77% in Mexico City, which leaves about 4.5% to 5% after costs, well below an 11% mortgage.
Cancún is weak as a rental play, with a 4.6% average gross yield. Tulum has turned into a buyer's market: nightly rates are down 23.6% in a year and property sales roughly halved between 2023 and 2025.
Airbnb rules are tightening. Mexico City's 50% cap on nights is law, even if most of it was still stuck in court in October 2026, so the property should work as a long-term rental.
The federal housing program (667,000 homes contracted by September 2026) targets low-income families and won't pull down prices in the areas foreigners buy.
A national crash looks unlikely, with the economy still growing (+1.9% in the second quarter of 2026). The real risk is local: an oversupplied resort condo.
The best buy now is boring: a finished property, clean title, real local demand, realistic rent, and a price that still works if appreciation slows further.

Are property prices in Mexico still going up?
Yes. Prices are still rising fast, although the market has come off its hottest pace.
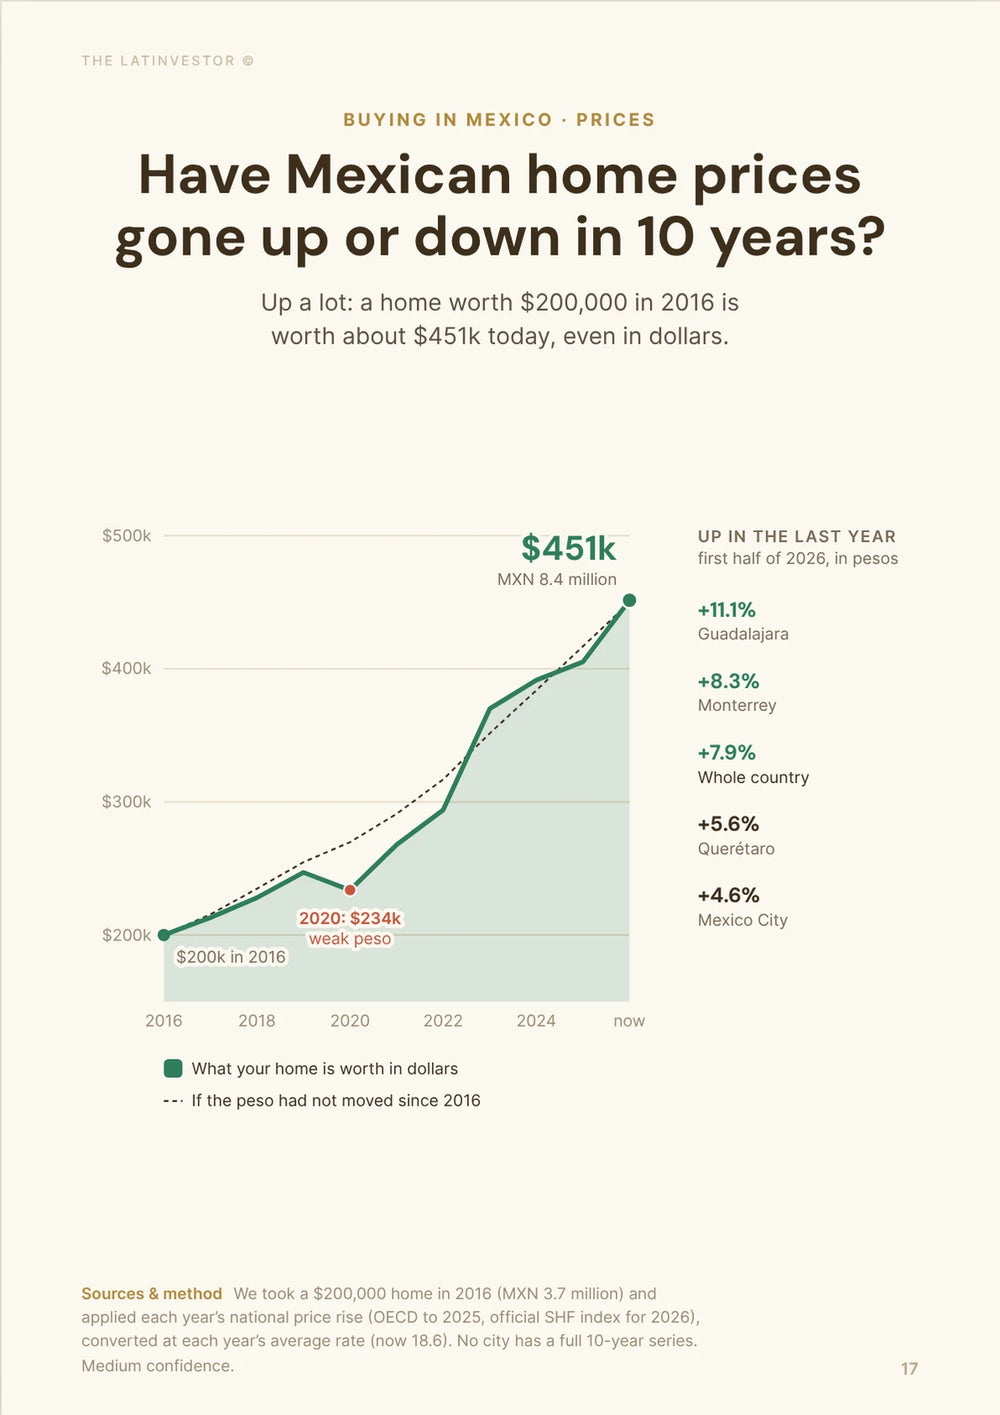
The Sociedad Hipotecaria Federal (SHF) housing index gives the cleanest national picture. Homes bought with a mortgage rose 7.3% year over year in the second quarter of 2026, after 8.6% in the first quarter, which puts first-half growth at 7.9%. For comparison, the index gained 8.7% over 2025.
Prices are still running well ahead of everyday prices. INEGI's annual inflation was 3.45% in September 2026, so homes are appreciating about four and a half points faster than inflation. Buyers are paying more for the property itself, not just keeping up with inflation.
The SHF data also show how wide the market is. The median mortgaged home was valued at about MXN 1.30 million in the first half of 2026, and the average at about MXN 1.96 million. Foreign buyers looking at Roma Norte, Polanco, Los Cabos or prime Riviera Maya developments will be far above those national benchmarks.
| Mexico housing measure | Latest reading | Previous reference | What we see |
|---|---|---|---|
| Q2 2026 home-price growth | 7.3% | 8.6% in Q1 2026 | Growth is slowing |
| First-half 2026 home-price growth | 7.9% | 8.7% in 2025 | Prices remain strong |
| Consumer inflation (September 2026) | 3.45% | — | Housing is still outrunning inflation |
| Median mortgaged-home value | MXN 1.30M | — | Typical financed housing remains far below prime expat markets |
| Average mortgaged-home value | MXN 1.96M | — | National averages hide large regional premiums |
Is Mexico's property boom finally cooling?
Yes. It's cooling enough to give buyers more time to think, negotiate and walk away from overpriced deals.
The trend shows it better than any single number: 8.7% over 2025, 8.6% in the first quarter of 2026, then 7.3% in the second quarter.
All property types are slowing together, so this isn't one weak segment dragging the average down. In the first half of 2026, new homes rose 8.3%, existing homes 7.5%, houses 8.4%, and apartments 7.4%.
We'd treat Mexico today as a slowing seller's market. Sellers can still point to rising prices, but buyers don't need to rush to beat someone else to a property.
Why are prices still rising when mortgage lending has stalled?
Because prices are being pushed by sellers, developers and cash buyers, not by a wave of new credit, and that's exactly where buyers can push back.
BBVA Research counted only 0.3% more mortgages in the first half of 2026 than a year earlier, and the amount lent was down 0.1% after inflation. Over the same period, SHF prices rose 7.9%. On top of that, registered new-housing inventory grew 34.6% in 2025, so there's more new stock on the market.
When prices rise but buyers don't borrow more, the gap usually closes through slower sales, longer listings and discounts, first in new developments. That's already visible in Tulum and in parts of Los Cabos.
What to do: ask the developer how many units are still unsold and since when, ask for the last three closing prices in the building (not the list prices), and negotiate on finished units that have been listed for months. A completed, unsold unit is the easiest place to get a discount right now.
Are mortgage rates in Mexico still too high?
Yes. Mexican mortgages are still expensive enough to ruin an average investment deal.
Banco de México cut its policy rate from 11.25% at the start of its easing cycle to 6.50%, then held it there in August and September 2026. A Citi survey published in October 2026 found that most analysts expect no change for the rest of 2026 or in 2027.
Home loans have fallen much less. Banxico's average fixed-rate mortgage quote was 11.31% in August 2026, and the average rate on new loans was 10.13% in March 2026. Strong borrowers can get somewhat better offers, but buyers are still looking at double-digit rates.
So the central bank has cut almost five points while mortgages have barely moved. Anyone waiting for 6% or 7% mortgages has been disappointed so far, and investors feel it most, because rental yields sit well below borrowing costs.
| Financing measure | Current level | Earlier level | What changed |
|---|---|---|---|
| Banxico policy rate | 6.50% | 11.25% before easing cycle | Central-bank rates fell sharply, now on hold |
| Average fixed mortgage quote (Aug. 2026) | 11.31% | — | Housing credit remains expensive |
| Average Mexico gross rental yield | 5.79% | — | About half the cost of a mortgage |
| Mexico City gross yield | 6.77% | — | Better than many cities, still below mortgage cost |
| Cancún gross yield | 4.60% | — | Very difficult to finance profitably at current rates |
Should buyers wait for Mexican mortgage rates to fall?
Not if cheaper loans are the only reason to wait.
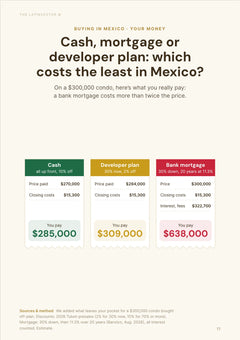
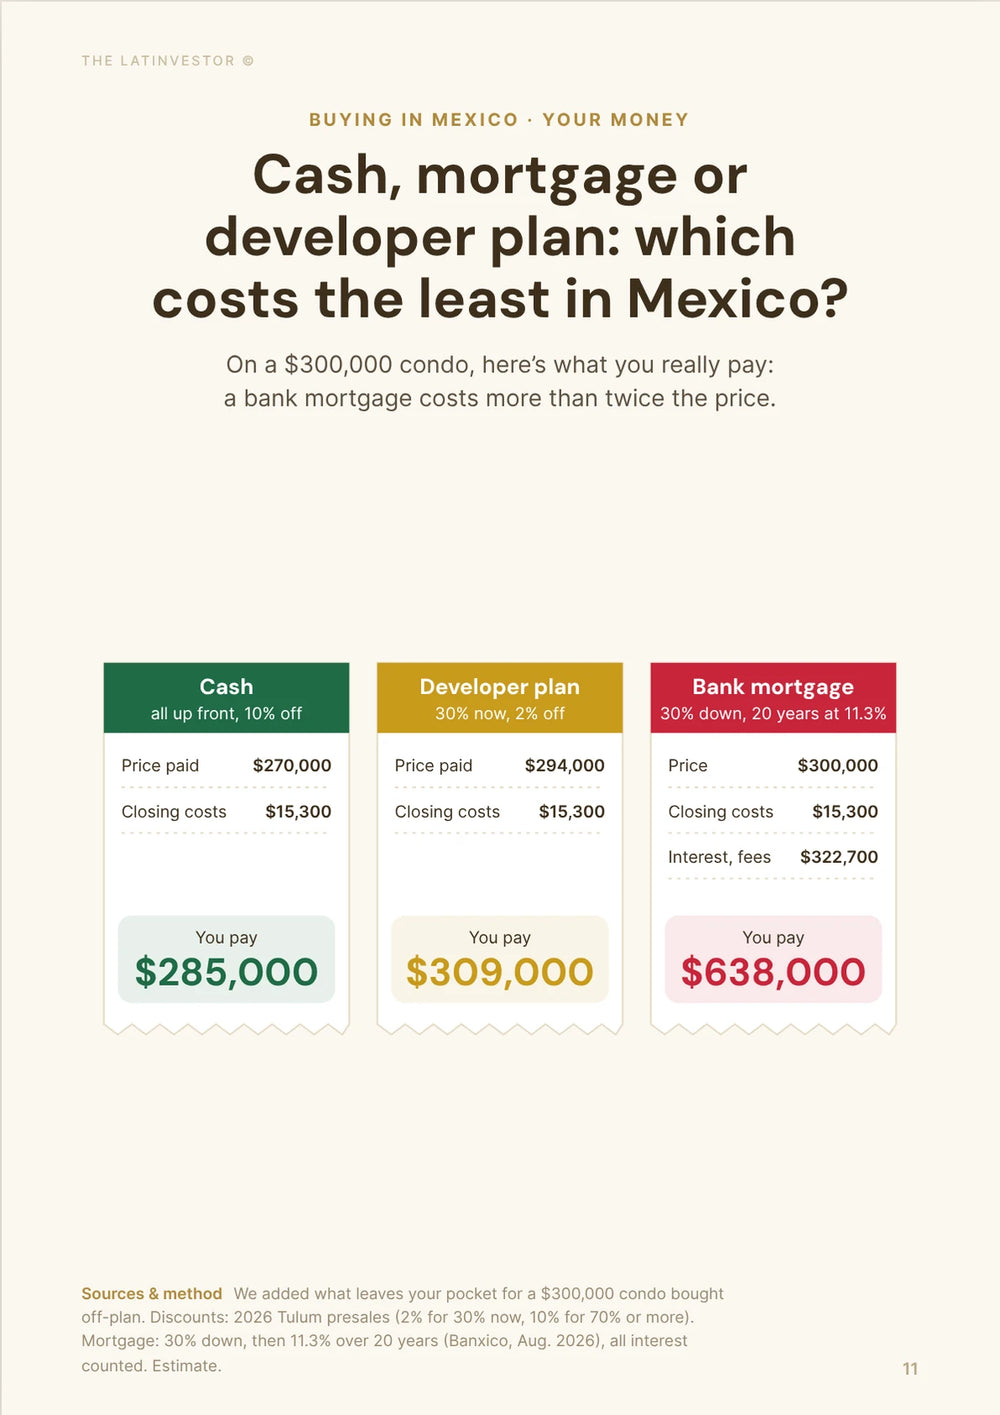
Take a MXN 3 million home with a 20% down payment. Borrowing MXN 2.4 million over 20 years at about 11.3% gives a monthly payment of roughly MXN 25,300.
One full point less in interest would cut that payment by only about MXN 1,600 a month. A 5% price rise on the same home adds MXN 150,000 (about US$8,060) to the price, and a 7% rise adds MXN 210,000. A small move in price easily wipes out the saving.
And there's no sign of a quick drop: Banxico is on hold, and the US Federal Reserve raised rates in September 2026, which leaves Banxico even less room to cut. We'd wait for a better property or a better price, not for a cheaper mortgage.
Has the peso's October slide made Mexico cheaper for dollar buyers?
A little, yes. The peso has weakened by about 9% since early September, so dollar buyers get noticeably more pesos than they did a few weeks ago.
The peso traded below 17 per dollar at the start of September 2026. After the Federal Reserve raised rates in mid-September, it slid for weeks: it crossed 18 on October 1, Banxico's FIX rate was 18.49 on October 16, and the dollar sits at about 18.6 pesos now.
On a MXN 5 million home, that's the difference between roughly US$294,000 at 17 pesos and about US$269,000 today, around US$25,000 saved without the seller moving on price.
Keep it in perspective, though. The dollar averaged 19.20 pesos over 2025, so Mexican property is still more expensive in dollars than it was last year, and peso prices have kept rising on top of that.
| Mexican property price | At about 17 MXN/USD (early Sept. 2026) | At about 18.6 MXN/USD (late Oct. 2026) | At 19.20 MXN/USD (2025 average) |
|---|---|---|---|
| MXN 3M | ~$176K | ~$161K | ~$156K |
| MXN 5M | ~$294K | ~$269K | ~$260K |
| MXN 10M | ~$588K | ~$538K | ~$521K |
Should dollar buyers convert now or wait for a better exchange rate?
If you've found the property, convert at least part of the money now: most forecasts expect the peso to strengthen again, not weaken further.
In September 2026, BBVA Research expected about 17.3 pesos per dollar at the end of 2026, and Banxico's survey of private analysts about 17.57. Citi's October survey, taken after the slide, is the most cautious at 18.20. Every one of those forecasts is below today's 18.6.
Nobody can call currencies, and a Fed that keeps hiking could push the peso weaker. But waiting for 19 or 20 means betting against most forecasters.
What to do: agree the price in pesos where you can, so you control the conversion, split the conversion into two or three tranches once the offer is accepted, use a transfer service rather than your bank's counter rate (bank sell rates were 18.73 to 19.10 on October 15 when the market was at 18.55), and keep a buffer of 5% to 10% in case the rate moves before closing.
Is Mexico City property a better buy than the hottest coastal markets?
For a long-term buyer, yes: Mexico City is easier to justify than most tourism-driven markets.
SHF's metro data put first-half 2026 price growth in the Valle de México at 4.6%. Guadalajara was up 11.1%, Tijuana 9.7% and Monterrey 8.3%.
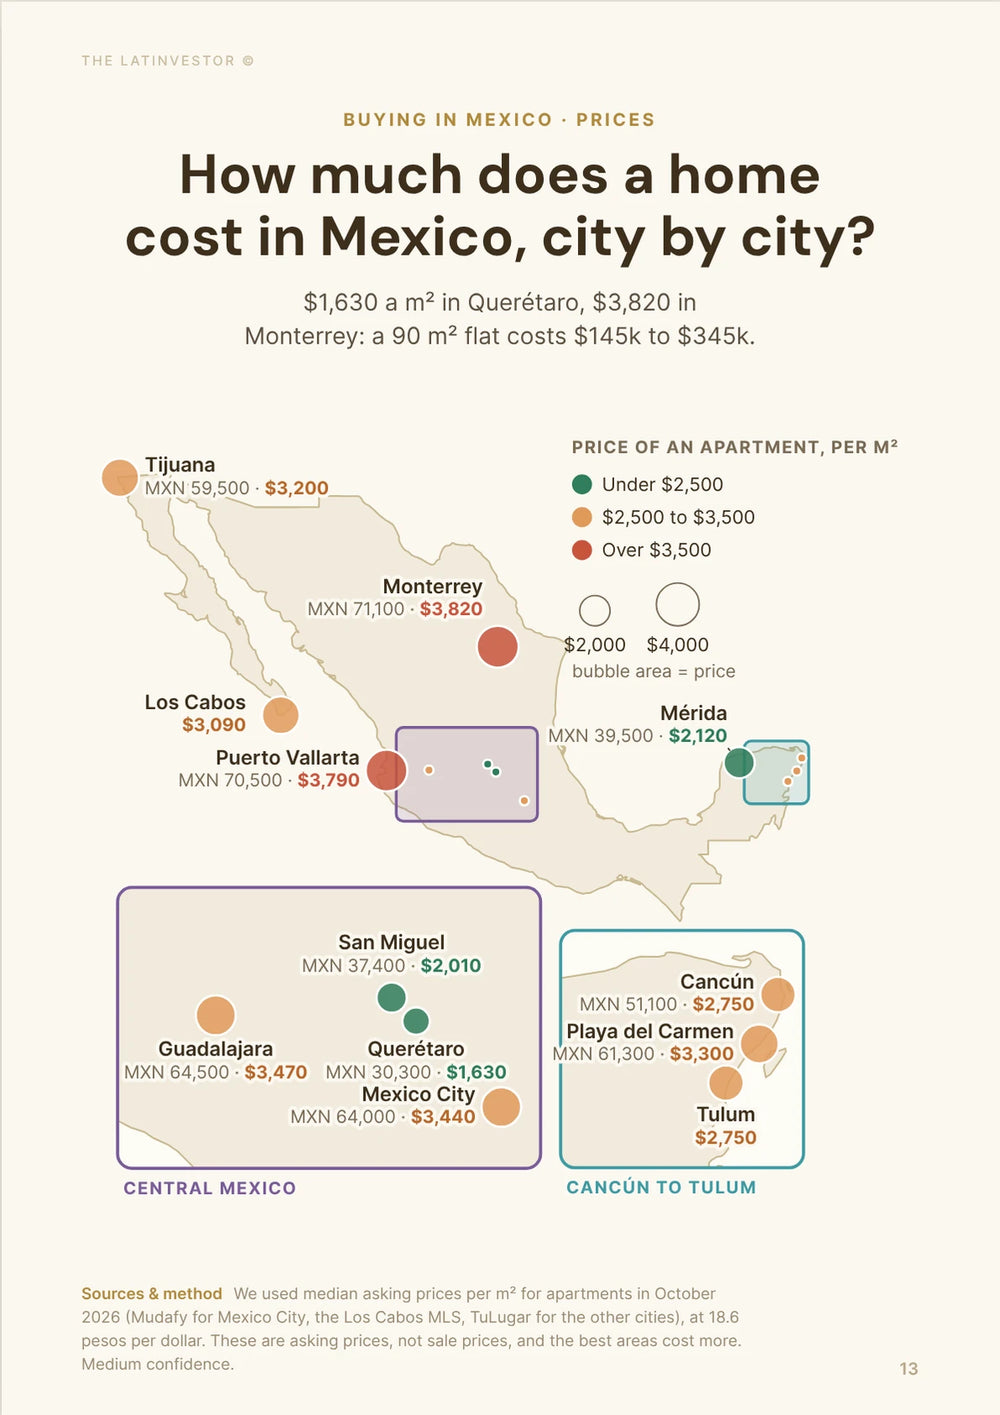
That doesn't make prime Mexico City cheap. TuLugar's listings put the citywide median asking price for apartments at about US$3,040 per m² (MXN 56,500) in October 2026, and Roma Norte, Condesa and Polanco ask well above that.
The reason we prefer it is the demand. Mexico City has millions of permanent residents, office jobs, universities, government and a huge long-term rental market. Rents for a two-bedroom were up 9.6% in the year to June 2026 according to Inmuebles24, faster than prices. A property there doesn't need another tourism boom to stay useful.
The slower price growth also means you're buying after a much smaller run-up than in Los Cabos, Cancún or the Riviera Maya.
Which Mexican property markets are still getting expensive fastest?
Guadalajara stands out, while Tijuana and Monterrey are also rising much faster than Mexico City.
According to SHF's metro index for the first half of 2026, Guadalajara rose 11.1%, Tijuana 9.7%, Puebla-Tlaxcala 8.5%, Monterrey 8.3%, Querétaro 5.6%, Toluca 5.1% and the Valle de México 4.6%.
The five-year view shows the gap even better. By the end of 2025, homes in Los Cabos were worth about 96% more than five years earlier. Benito Juárez, which includes Cancún, was up about 94%, and Solidaridad, where Playa del Carmen sits, about 90%.
Guadalajara was up about 66% over those five years and Tijuana almost 78%. Mexico City rose about 41%.
Another 10% rise in a market that has already almost doubled deserves more scrutiny than the same rise after years of flat prices.
| Market | Annual growth, H1 2026 | Approx. five-year gain to end-2025 | Our read |
|---|---|---|---|
| Guadalajara | 11.1% | 66% | Still very hot |
| Tijuana | 9.7% | 78% | Strong but already heavily repriced |
| Monterrey | 8.3% | 58% | Still rising quickly |
| Querétaro | 5.6% | 56% | Cooling after a strong run |
| Valle de México | 4.6% | 41% | Much calmer |
| Los Cabos | No comparable 2026 figure | 96% | Very expensive after a huge run, sales slowing |
| Benito Juárez / Cancún | No comparable 2026 figure | 94% | High starting price, thin rental yield |
Can rental income still make a Mexican property worth buying?
Yes, but today's yields favor cash buyers far more than buyers who borrow.
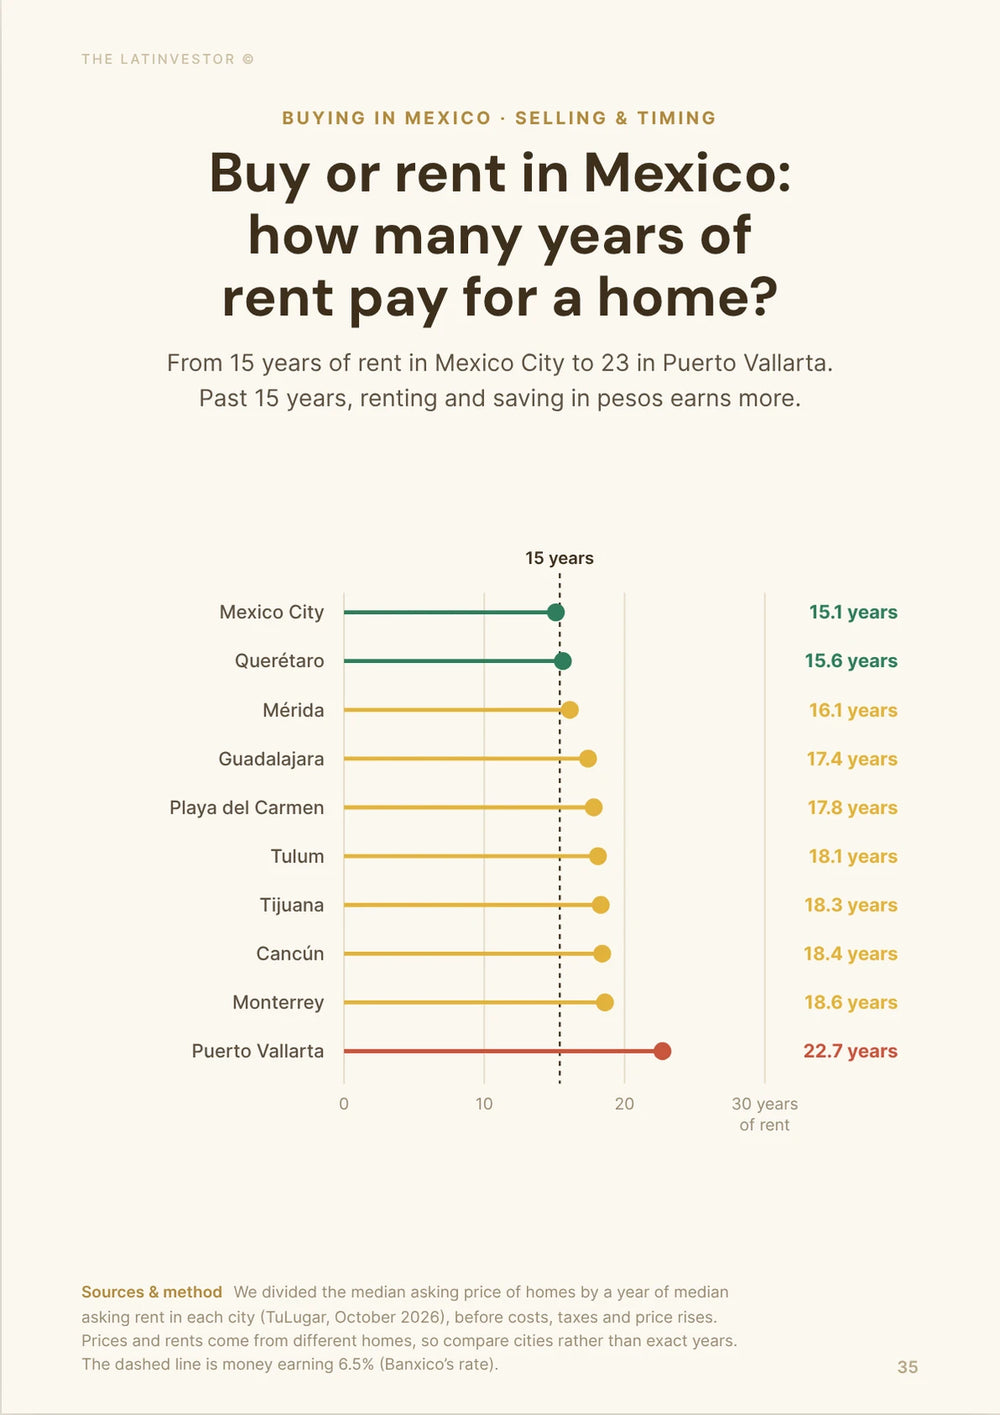
Global Property Guide's 2026 data put Mexico's average gross rental yield at 5.79%. Mexico City averages 6.77%, Puebla 6.12%, Mérida 6.08%, Monterrey 5.82%, Guadalajara 5.58% and Cancún only 4.60%.
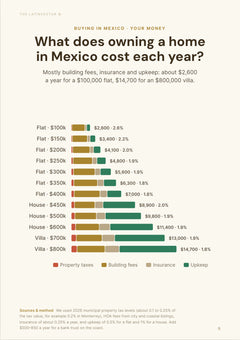
Those are gross figures, calculated on asking rents and asking prices. Condo fees, management, repairs, empty months, taxes and insurance typically take another 1.5 to 2 points off, so a 6.5% gross yield often ends up closer to 4.5% or 5% before financing.
That's fine for a cash buyer who wants income plus long-term appreciation. Borrowing at 10% to 11% to earn 5% is much harder to defend.
Is Cancún property still a good investment now?
As a pure rental investment at today's prices, Cancún looks weak.
Its 4.60% average gross yield is the lowest of the major cities covered by Global Property Guide. Short-term rentals don't change the picture much: AirDNA counts about 6,670 active listings with 54% average occupancy and a nightly rate of about US$129 over the year to September 2026.
That low income comes after one of the biggest price runs in Mexico: SHF's index shows Benito Juárez home values almost doubling in the five years to the end of 2025.
A great Cancún property can beat the city average: beach access, Hotel Zone scarcity, professional management and a real rental history all help. We'd still want to see those advantages in actual numbers. Buying an ordinary condo because Cancún gets millions of tourists is no longer enough.
Is Tulum finally becoming a buyer's market?
Yes, Tulum has become a buyer's market, and the reason should make investors careful.
AirDNA counts about 3,608 active short-term rentals in Tulum in September 2026, with 46% average occupancy, an average nightly rate of about US$125 and RevPAR of about US$58.
The trend is what matters. Nightly rates are down 23.6% in a year and RevPAR is down 10.7%, while active listings have dropped sharply. Occupancy and revenue per remaining listing are up, which suggests weaker operators are leaving and the survivors cut prices to fill nights. On the sales side, El Economista counted 1,711 property sales in 2025, against 3,487 in 2023, with a large stock of condos still unsold.
For buyers, that means real negotiating room on finished units, resales and developers under pressure. Use it to buy something with a verified rental history. Projected Airbnb returns on another pre-construction unit deserve very little trust today.
Has Airbnb become riskier for property investors in Mexico?
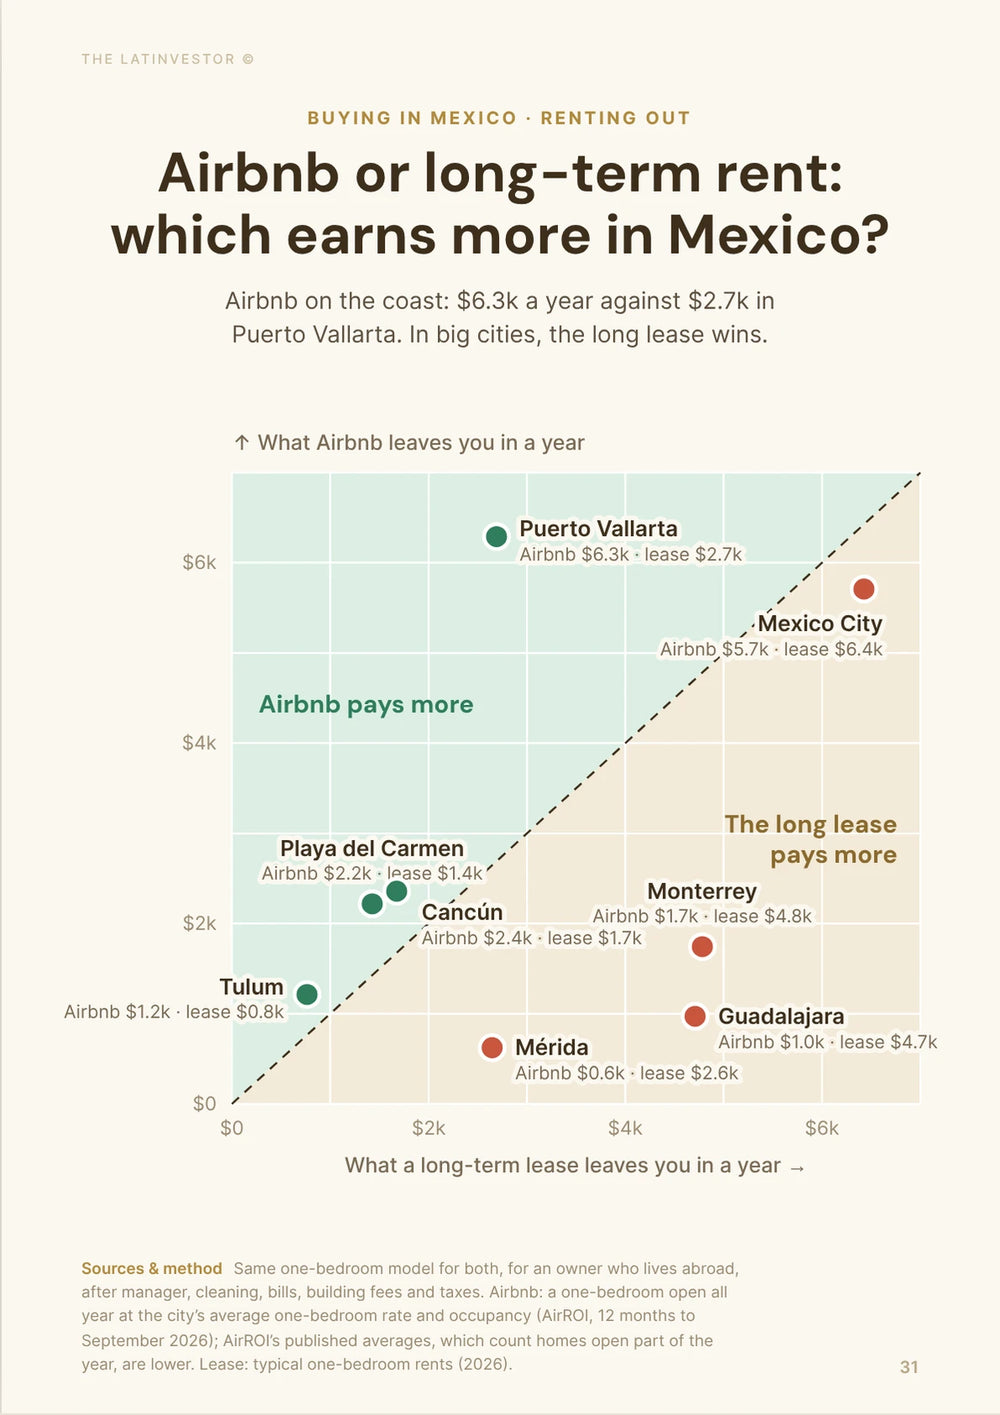
Yes. An Airbnb-first purchase now carries enough regulatory and operating risk that the property should still work as a long-term rental.
Mexico City's law now caps short-term rentals at 50% of the nights in a year (about 182 nights), with a host registry and limits on multiple units. As of October 2026, El Financiero and Excélsior reported that most of these rules were still not enforced, held up by extensions and court challenges. That uncertainty is a risk in itself: don't pay a price that only works at 70% occupancy.
Quintana Roo is moving the same way with RETUR-Q, its tourism-provider registry. And at the federal level, platforms withhold 4% income tax from individual hosts, with 16% VAT on top, so hosts have to deal with registrations and taxes, not just a listing.
The operating numbers show the risk too. In Tulum, more nights are booked but nightly rates are falling, because owners compete on price.
So we'd value a condo on long-term rental demand, resale liquidity and the neighborhood, not on a spreadsheet projecting 70% Airbnb occupancy. If it only works in a near-perfect vacation-rental scenario, we'd pass.
Will Mexico's huge housing program push property prices down?
Probably not anytime soon. Mexico is building a lot more housing, but most of it doesn't compete with what foreigners and upper-middle-income buyers want.
SEDATU reported 667,000 homes contracted under the federal Vivienda para el Bienestar program by September 2026, 277,000 under construction and 89,000 assigned to families. The six-year target is 1.8 million homes.
Those are big numbers, but the program targets lower-income households, with homes mostly priced around MXN 600,000 and an Infonavit ceiling raised from MXN 630,000 to MXN 862,000 in late September 2026. A new affordable home on the edge of a city does nothing to add condos in Roma Norte, beachfront Los Cabos or central Playa del Carmen.
Mexico also still has a real housing shortage. SEDATU and CONAVI's 2025 update counted about 8.33 million households, around 21% of the total, living in inadequate housing.
So we expect more construction to cool parts of the market gradually, not to cause a national oversupply shock. Local oversupply is another story: Tulum shows that a national shortage doesn't protect an area where developers have built too many identical investor condos.
Does buying property in Mexico make less sense for foreigners now?
Not much less. Ownership is still straightforward, but buying and selling costs mean you need to hold for years, not months.
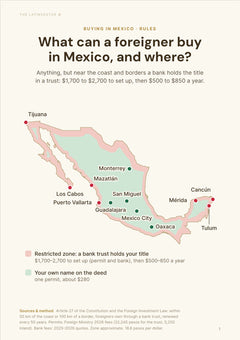
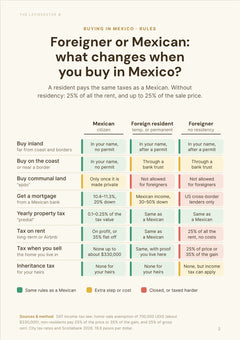
Foreigners can own residential property directly outside Mexico's restricted zone.
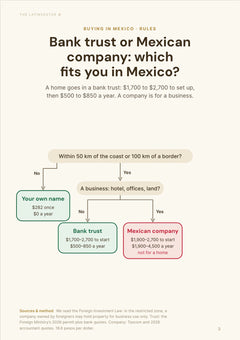
Within 50 kilometers of the coast or 100 kilometers of a border, a foreign buyer uses a bank trust (fideicomiso). The bank holds title as trustee, and you keep the right to use, sell, rent and pass on the property. The trust lasts 50 years and is renewable.
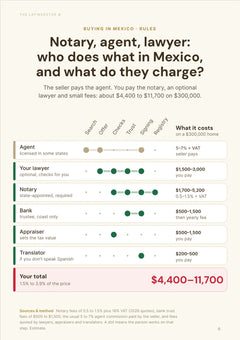
That's routine in Cancún, Tulum, Playa del Carmen, Puerto Vallarta and Los Cabos, but it costs money: the SRE permit is MXN 21,650 (about US$1,160) in 2026, and banks typically charge around US$550 to US$800 to set up the trust and US$550 to US$700 a year to run it.
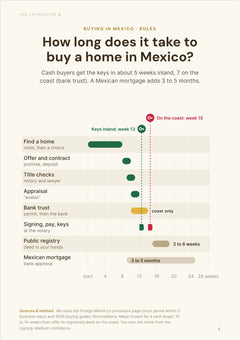
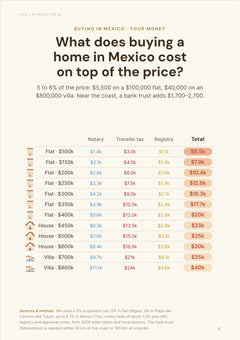
Closing costs make quick resales hard too. Acquisition tax, notary, registration, appraisal and trust costs typically add about 6% to 9% of the price for a foreign buyer, depending on the state.
Add currency swings like the 9% move of the past few weeks, and we'd only buy if you're comfortable holding for at least five years.
Could Mexican property prices actually crash from here?
A nationwide crash looks unlikely.
SHF data still show prices rising in every major metro area it covers. The economy is growing slowly but growing: GDP was up 1.9% year over year in the second quarter of 2026, according to INEGI.
There are weak spots, but they don't add up to the usual crash setup. There's no collapse in jobs, no wave of forced sales and no nationwide glut arriving all at once.
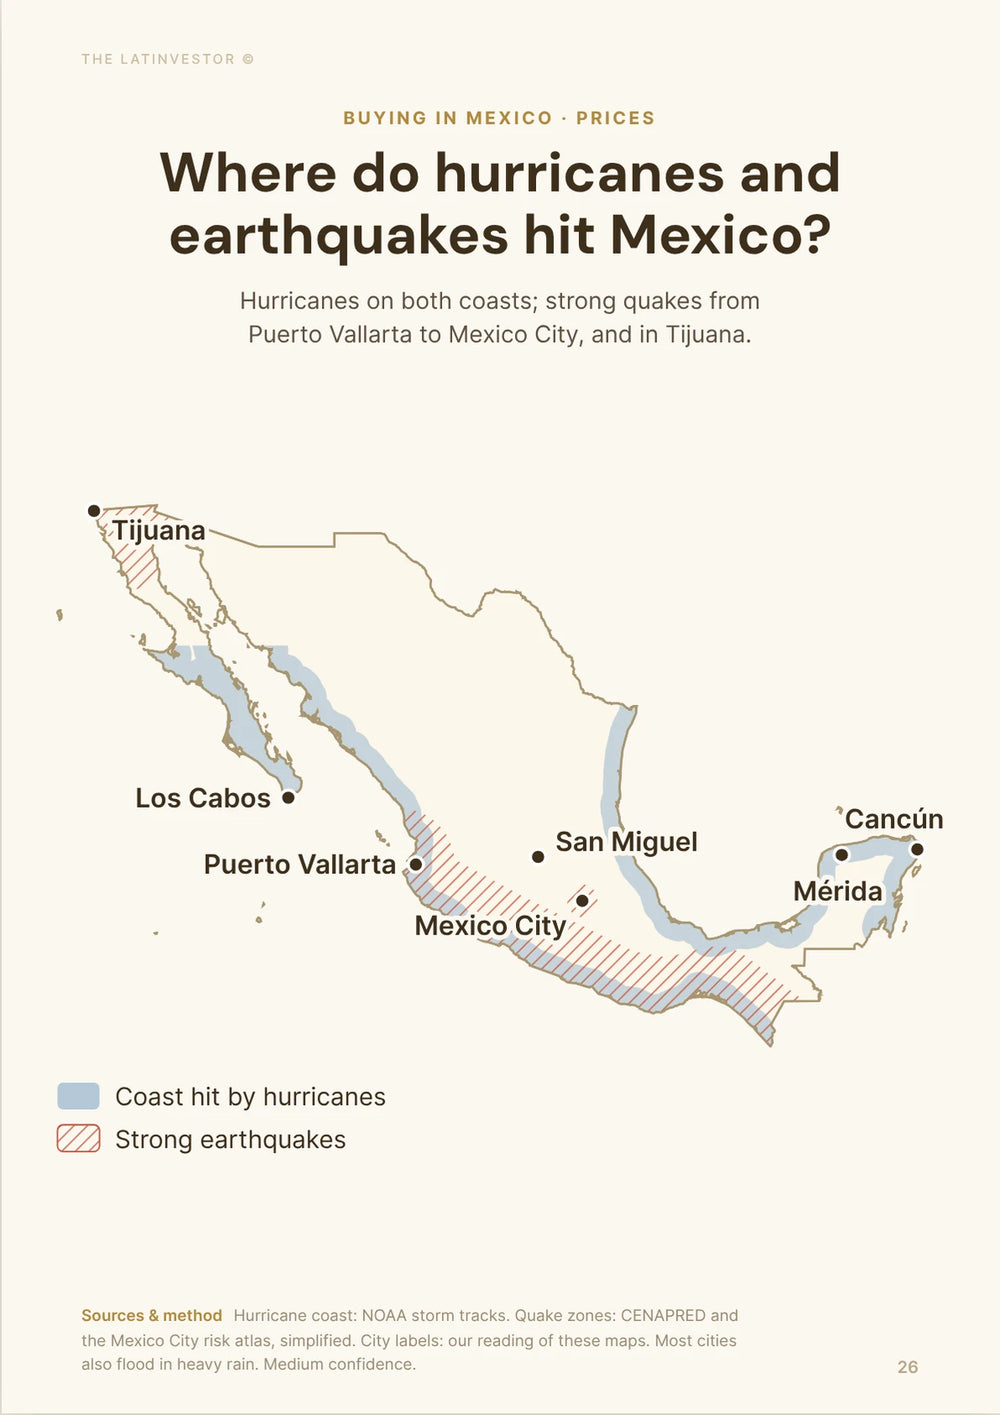
High mortgage rates are the biggest pressure, and more construction should slow price growth over time. Tourism-heavy markets could fall much harder than the national average if international demand weakens.
The realistic downside is local. A generic condo in an oversupplied resort development can lose value while a scarce family home in a strong job market keeps rising. Waiting for all of Mexico to get 20% cheaper is a much bigger bet than the data support.
So is it a good time to buy property in Mexico now?
Yes, selectively. Mexico is a reasonable place to buy good property for the long term, and a poor place to buy a mediocre one with expensive debt and hope the market saves the deal.
Prices are still rising, so waiting for a crash is hard to justify. But growth is slowing (7.3% in the second quarter of 2026) and mortgage lending is flat, so buyers have less reason to rush and more room to negotiate.
Cash buyers have the clearest advantage. They avoid mortgage rates above 10% and can still find gross yields around 6% to 7% in the stronger cities. Mexico City stands out because its prices have risen much more calmly than in Guadalajara or the big resort markets.
Dollar buyers have a small window: the peso has gone from under 17 to about 18.6 per dollar since early September, and most forecasts expect it to strengthen again. If you're ready to buy, that's a reason to move, not to wait.
Resort markets need even more discipline. Cancún combines thin rental yields with years of strong price growth. Tulum gives you negotiating power, and its rental numbers show why.
The best purchase today is boring: a finished property, clean title, an established neighborhood, real local demand, a sensible price, realistic rent, and enough margin that it still works without another year of strong price growth.
If you're financing heavily, buying pre-construction on projected Airbnb returns, or chasing a resort market because it doubled in five years, we'd wait or look elsewhere.
Our methodology
This article estimates whether now is a good time to buy property in Mexico by looking at what actually changes a purchase decision: price trends, mortgage lending and rates, rental yields, the exchange rate, differences between cities, short-term-rental performance, housing supply, ownership rules and crash risk.
Price trends come from Sociedad Hipotecaria Federal's housing index (second quarter of 2026, with metro data for the first half), and five-year gains from SHF's historical series as published by Global Property Guide. Mortgage lending comes from BBVA Research, mortgage rates and the policy rate from Banco de México, inflation and GDP from INEGI, and exchange-rate forecasts from BBVA Research, Banxico's analyst survey and Citi's survey. Rental yields come from Global Property Guide, short-term-rental figures from AirDNA, and asking prices from TuLugar.
Ownership rules and the trust permit cost come from the Secretaría de Relaciones Exteriores. Bank trust fees and closing costs are third-party estimates (Homia, Compass Abroad), and housing supply figures come from SEDATU and CONAVI.
We checked these figures in October 2026. Conversions use about 18.6 pesos per US dollar and 20.9 pesos per euro.
The limits: SHF covers homes bought with a mortgage, not cash purchases in resort areas, and there's no comparable 2026 price growth figure for Los Cabos or Cancún. Asking prices and asking rents are not closing prices. Gross yields come before expenses, and AirDNA figures are averages that hide big gaps between properties. Exchange-rate forecasts are just that.
Key sources used for this analysis include: SHF housing price index, Q2 2026, SHF housing index data 2025-2026, IIEG summary of the SHF Q2 2026 index, Milenio on 2025 home-price growth, Global Property Guide price history, BBVA Research, Situación Inmobiliaria H2 2026, BBVA Research, Situación Inmobiliaria H1 2026, Banco de México mortgage rate quotes, Banco de México quarterly report Q1 2026, Banco de México monetary-policy decisions, El Financiero on the Citi expectations survey, Banco de México FIX exchange rate, UnoTV on the peso's October fall, Excélsior bank exchange rates, October 15, 2026, BBVA Research, Situación México September 2026, INEGI consumer prices, September 2026, México, ¿cómo vamos? on Q2 2026 GDP, Global Property Guide rental yields, El Economista on Mexico City rents, TuLugar Mexico City market data, AirDNA Tulum, AirDNA Cancún, El Economista on Tulum oversupply, El Financiero on Mexico City short-term rental rules, Excélsior on the 50% limit, SEDATU on Vivienda para el Bienestar, Diario Oficial on Bienestar home prices, SEDATU/CONAVI housing deficit 2025, SRE trust permit costs, SRE restricted-zone trust guidance, Homia bank trust fees 2026, and Compass Abroad closing costs 2026.