

Summary
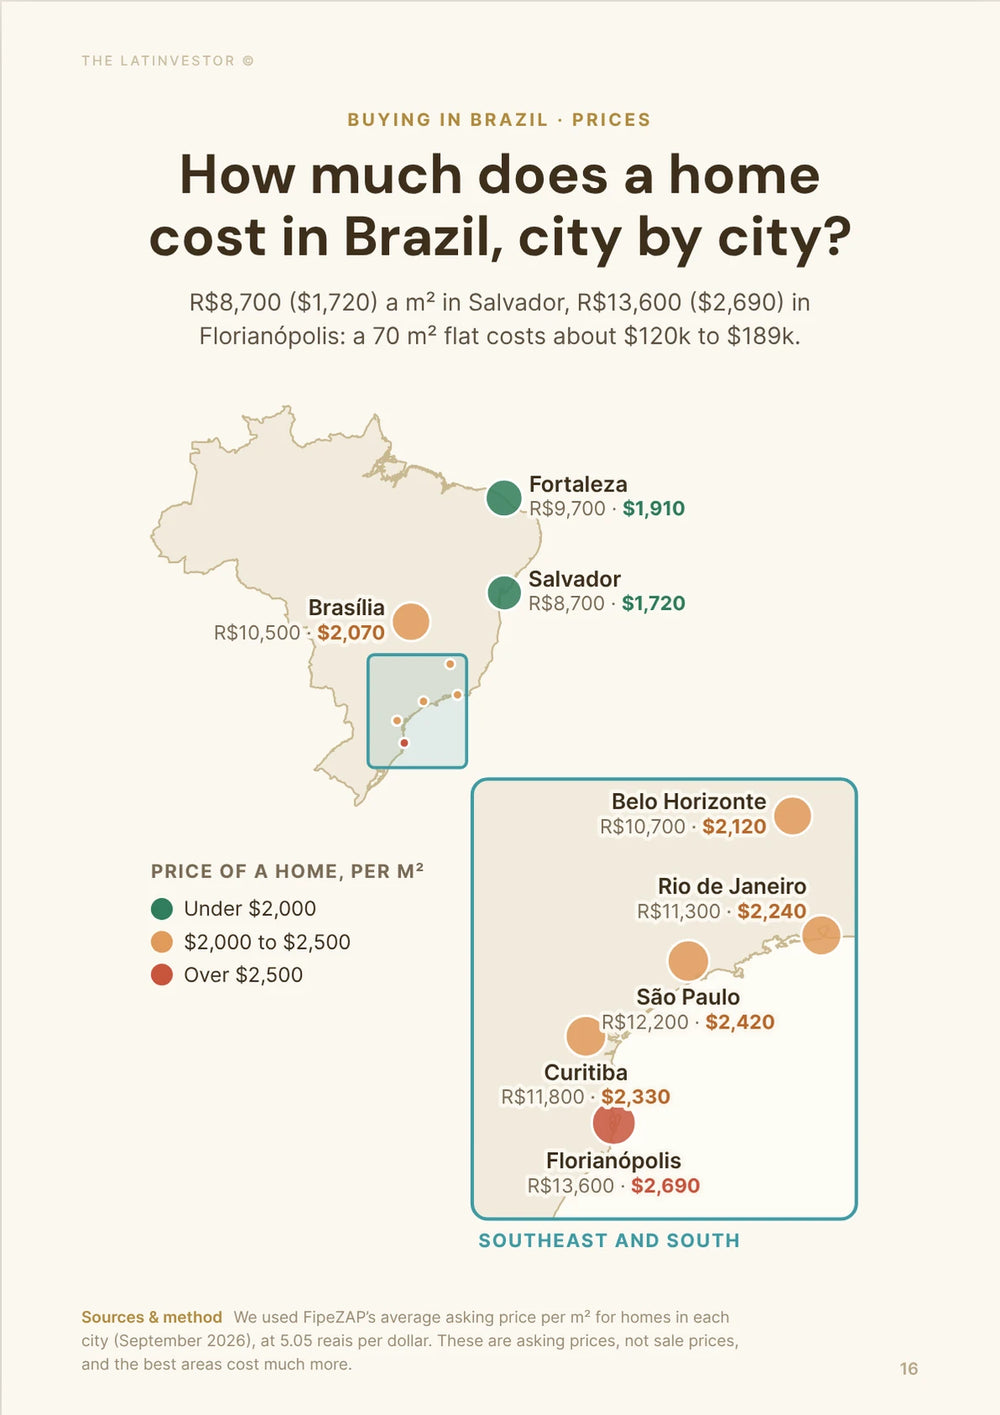
For rental income, the best places are mid-priced, metro-connected areas like Botafogo and Flamengo in Rio, with gross yields around 6.8%, ahead of famous addresses like Leblon. For price growth, look at the Northeast capitals. Nationally, FipeZAP asking prices average R$ 10,015 per square meter (about USD 1,980).
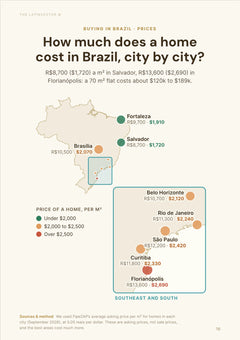
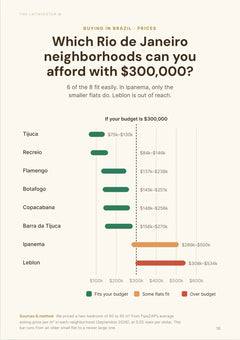
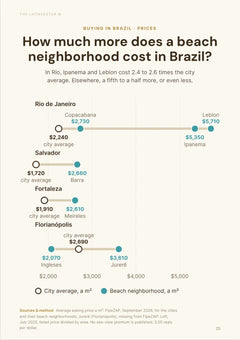
Leblon is the most expensive neighborhood we track, at R$ 28,837 per square meter, followed by Ipanema (R$ 26,996) and Itaim Bibi in São Paulo (R$ 19,989). Tijuca in Rio is at R$ 7,011.
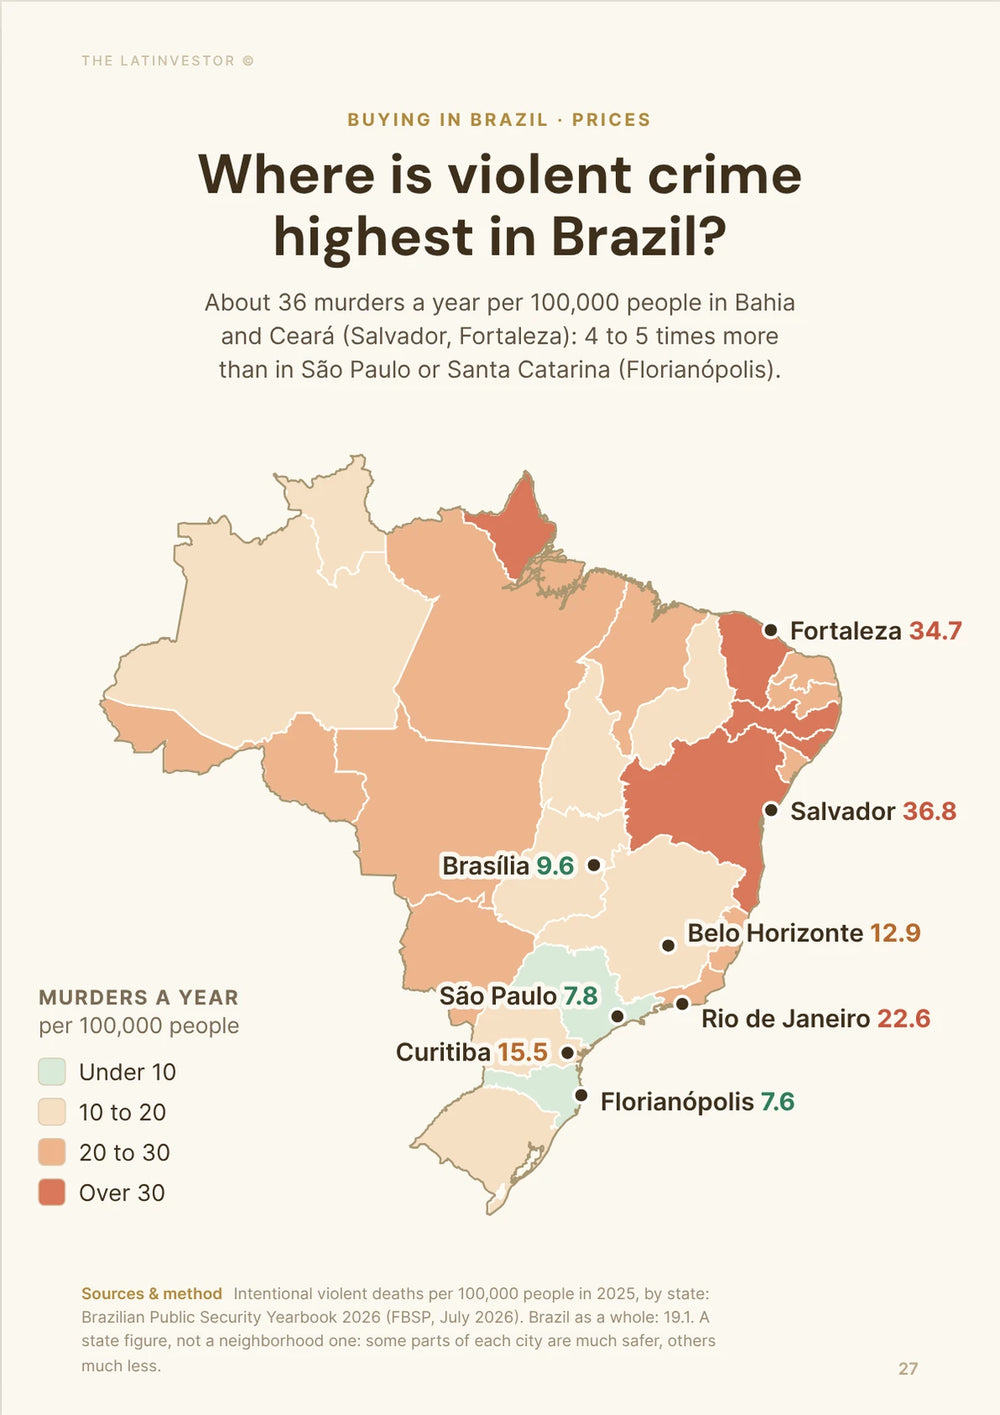
Salvador (+10.38%) and Fortaleza (+10.2%) posted the biggest price rises of the big cities we track in the year to September 2026. São Paulo rose only 3.64%, which is a 0.9% loss after inflation.
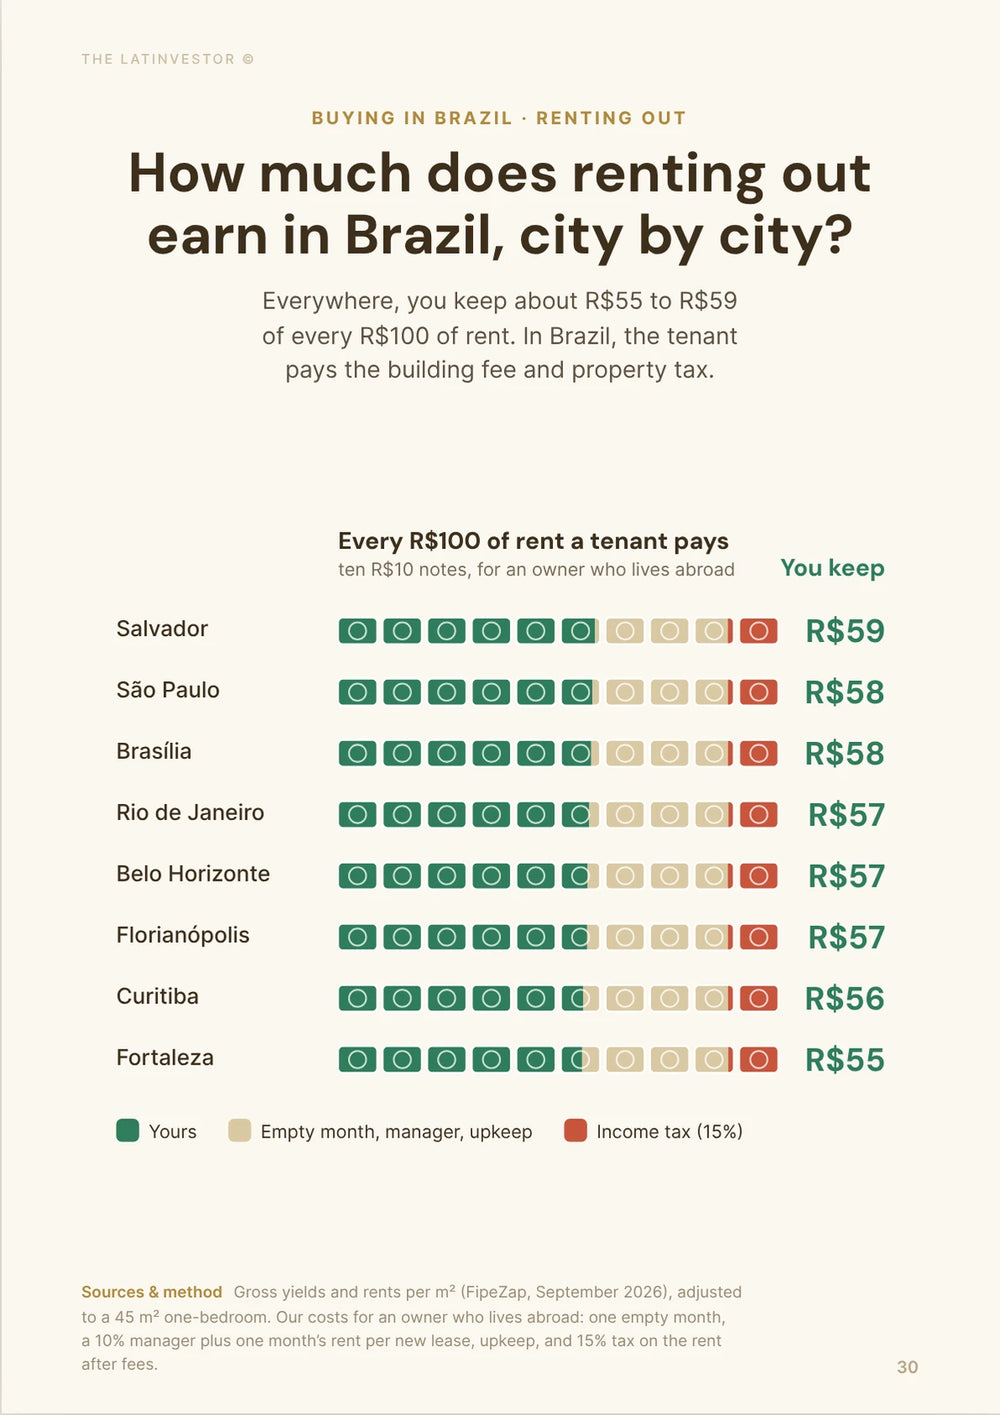
Gross yields are highest in cheaper or central pockets, like São Paulo's Centro and República (about 8.02%), Sudoeste in Brasília (7.36%) and Salvador (7%). Leblon gives about 5.08%, and a non-resident loses 15% of rent to withholding tax.
On Airbnb, an average Rio listing grossed about R$ 71,981 over the last year on AirROI, at 42.6% occupancy, but active listings grew 50% in a year.
Since the STJ's May 2026 ruling, Airbnb in a residential building can require a two-thirds owner vote, so check the condo rules before you pay for a short-term-rental location.
Long-term rents are rising fast where tenants want to live: FipeZAP asking rents rose 14.8% in Rio in a year, and about 19.5% in Botafogo and Flamengo.
The up-and-coming areas sit near new transit and renewal programs: São Paulo's Metro Line 6-Orange opened its first six stations in July 2026, and our estimate is 15% to 30% growth over two to three years near such stations.
Some areas need care: São Paulo's Cantareira reservoir was at 41.1% at the end of September 2026, with nightly water-pressure cuts, and República's high yield comes with oversupply and street-level safety issues.
For long-term growth, Florianópolis rose 64.2% over five years, and a FipeZAP-based model expects 7% to 8.5% in Florianópolis, Salvador and Fortaleza over the next 12 months, against 3.69% in São Paulo.
Locals favor places like Vila Nova Conceição, Leblon, Lago Sul and Batel (R$ 17,575 per square meter in Curitiba). Expats cluster in Itaim Bibi, Pinheiros, Ipanema, Leblon and Lagoa da Conceição.
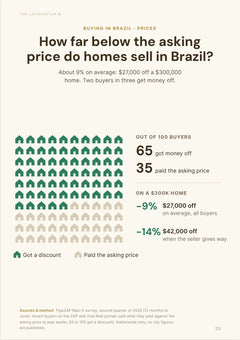
Bottom line: if you want income, buy a mid-priced, metro-connected apartment and negotiate 9% to 14% off asking; if you want growth, look at the Northeast capitals, accepting more risk.


Which neighborhoods cost the most, and the least, in Brazil?
Which areas in Brazil have the highest property prices per square meter?
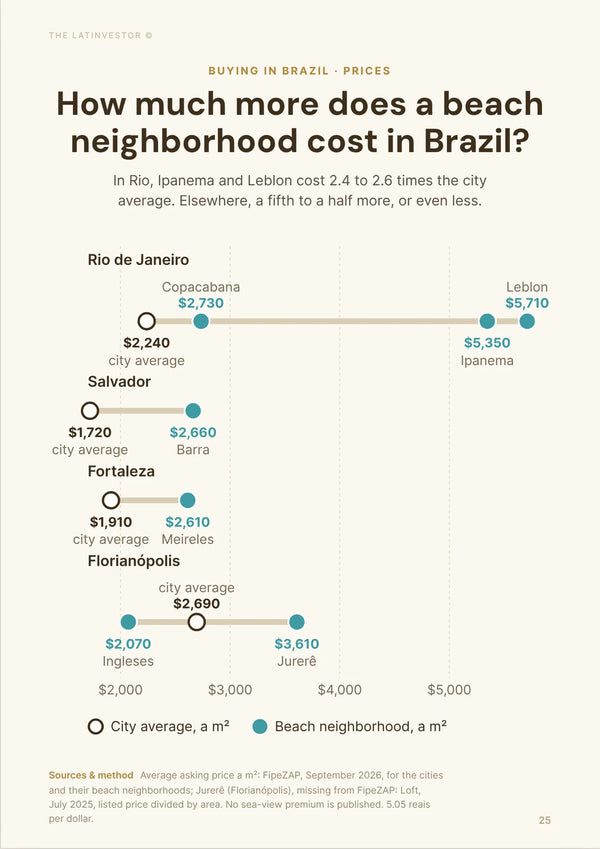
Leblon and Ipanema in Rio de Janeiro are the most expensive neighborhoods FipeZAP tracks, at R$ 28,837 and R$ 26,996 per square meter in September 2026 (about USD 5,710 for Leblon). In São Paulo, the top spots are Itaim Bibi (R$ 19,989), Pinheiros (R$ 18,260) and Jardins (R$ 18,028).
The very best addresses go higher still, like Vila Nova Conceição and Jardim Europa in São Paulo, but FipeZAP doesn't publish them separately. Our estimate is that renovated units with views there ask well above R$ 20,000 per square meter.
Each of these expensive neighborhoods commands premium prices for distinct reasons:
- Leblon (Rio de Janeiro): beachfront scarcity, walkable restaurants, and the safest perception in Zona Sul.
- Jardim Europa (São Paulo): large house plots near Ibirapuera Park with gated security and privacy.
- Vila Nova Conceição (São Paulo): proximity to Faria Lima's finance jobs and top schools.
- Ipanema (Rio de Janeiro): iconic beach lifestyle combined with strong international buyer demand.
Which areas in Brazil have the most affordable property prices?
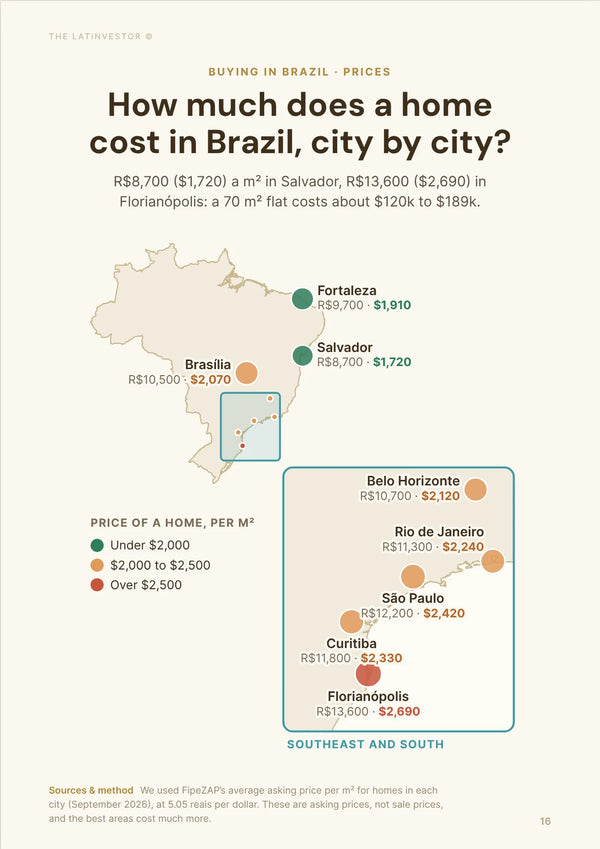
Among the neighborhoods FipeZAP tracks, Tijuca in Rio (R$ 7,011 per square meter, about USD 1,390) and Recreio (R$ 7,897) are the cheapest, along with Vila Andrade (R$ 8,372) and Santana (R$ 9,288) in São Paulo. Whole cities are cheaper too: Salvador averages R$ 8,691 and Fortaleza R$ 9,660.
Further out, places like Penha and Vila Matilde in São Paulo's Zona Leste, or Méier and Madureira in Rio's Zona Norte, are cheaper still, but FipeZAP doesn't publish them, so check recent listings and the property's registration (matrícula) yourself.
The main trade-offs in these lower-priced areas include longer commutes to business districts in Zona Leste neighborhoods like Penha, less walkable street retail and security variability in parts of Méier and Madureira, and thinner resale liquidity compared to established prime zones in all these cities.
Where are prices rising fastest in Brazil right now?
In the Northeast. In the year to September 2026, FipeZAP asking prices rose 10.38% in Salvador and 10.2% in Fortaleza, against 8.31% in Florianópolis, 5.57% in Rio, 5.51% nationally and only 3.64% in São Paulo. With inflation at 4.58%, São Paulo actually lost 0.9% in real terms.
At the neighborhood level, the biggest jumps were Praia do Futuro II in Fortaleza (+21.7%), Barra in Salvador (+15%), Ondina (+13.9%) and Graça (+13.8%) in Salvador, Leblon (+13.2%) and Aldeota in Fortaleza (+13%). Meanwhile, São Paulo's trendy Pinheiros slipped 0.3% and Vila Mariana gained only 0.4%.
Two things to keep in mind. These are asking prices, and buyers in FipeZAP's Q2 2026 survey got an average discount of 9%, or 14% when a discount was negotiated. And fast-rising areas can cool quickly: Salvador and Fortaleza were already classed as "cooling" in September 2026, meaning growth is slowing, not reversing.
So if you buy where prices are running, negotiate hard, and compare with recent sales in the same building, not just with portal listings.
 Brazil Property Prices
Where do rental yields look best in Brazil?
Which neighborhoods in Brazil have the highest gross rental yields?
The highest gross yields we found are in São Paulo's Centro and República (about 8.02%), Sudoeste in Brasília (7.36%), Graça and Pituba in Salvador (about 6.9% to 7%), Águas Claras in Brasília (6.98%), and Flamengo and Botafogo in Rio (about 6.8%).
The national FipeZAP average is 6.13%. The most famous addresses yield the least: Leblon about 5.08%, Ipanema 5.25%, Jardins 5.59%, and Batel in Curitiba just 3.76%. Curitiba's Água Verde, often sold as a yield play, gives about 4.7%.
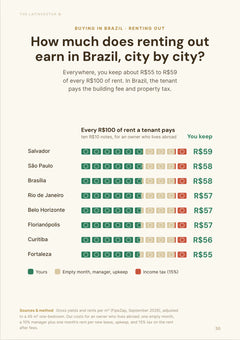
These are gross figures. As a non-resident, 15% of the rent is withheld as tax, which takes the 6.13% national average to about 5.2% before vacancy and repairs. In a long-term lease, the tenant normally pays the condo fee and IPTU.
These top-yielding neighborhoods deliver better returns than others for specific reasons:
- Centro and República (São Paulo): cheap studios near jobs and transit, but block-by-block safety varies and supply keeps growing.
- Sudoeste and Águas Claras (Brasília): civil servants and professionals keep demand steady.
- Graça and Pituba (Salvador): family and professional demand at low purchase prices.
- Botafogo and Flamengo (Rio de Janeiro): metro access and young professionals, without Leblon's prices.
- Vila Mariana (São Paulo): metro, universities and hospitals keep tenants coming, at about 5.89%.
Where does Airbnb still work in Brazil?
Which neighborhoods in Brazil perform best on Airbnb?
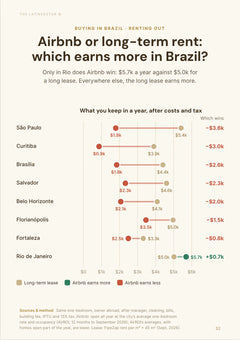
Rio de Janeiro is still Brazil's strongest Airbnb city: on AirROI, an average listing grossed about R$ 71,981 over the year to September 2026, roughly R$ 6,000 a month, at 42.6% occupancy and R$ 624 a night. Copacabana, Ipanema and Leblon do most of that business.
In São Paulo, the average is much lower, at about R$ 32,797 a year, with 40.1% occupancy and R$ 309 a night, driven by business travel in Pinheiros, Itaim Bibi and Vila Madalena. Florianópolis sits in between at about R$ 46,111, but it's very seasonal, with 37.4% occupancy over the year.
These are averages before platform fees, cleaning and running costs, which AirROI puts at around a quarter of revenue. Results depend heavily on property quality, guest reviews, and timing around Carnival and New Year.
Each of these Airbnb hotspots outperforms for distinct reasons:
- Copacabana (Rio de Janeiro): beach access and iconic status attract international tourists year-round.
- Ipanema (Rio de Janeiro): higher-end travelers willing to pay premium rates for walkable dining.
- Pinheiros (São Paulo): proximity to Faria Lima offices drives consistent corporate bookings.
- Vila Madalena (São Paulo): nightlife and cultural scene appeal to younger leisure visitors.
- Jurerê Internacional (Florianópolis): seasonal beach tourism creates peak summer demand.
Which tourist areas in Brazil are becoming oversaturated with short-term rentals?
Supply is growing much faster than demand. On AirROI, active Airbnb listings rose 50% in a year in Rio (to 33,138), 66% in São Paulo (to 34,925), 48% in Florianópolis and 74% in Salvador.
Competition is fiercest on the beachfront strips of Copacabana and Ipanema, and in the micro-studio clusters of central São Paulo like Consolação and República, where many new buildings were designed with short stays in mind.
When listings grow this fast, hosts end up cutting nightly rates to keep their occupancy. Before buying for Airbnb in these areas, check month-by-month occupancy and rates for similar units nearby, not just the city average.
 70+pages
Does the STJ's 2026 Airbnb ruling change where you should buy?
Yes, it changes which buildings you should buy in. On 7 May 2026, Brazil's Superior Court of Justice (STJ) ruled that offering an apartment on platforms like Airbnb in an exclusively residential condominium can require approval by two-thirds of the owners.
Then on 17 September 2026, the STJ picked the question for a binding ruling (Tema 1.443): does a simple "residential use" clause allow a ban, or does the building need an explicit one? Similar court cases are suspended nationwide until it decides.
Some rules are already clear. In São Paulo, affordable-housing units (HIS-1, HIS-2 and HMP) can't legally be used for short stays. Rio still has no general municipal license for Airbnb; a city bill on seasonal letting is still in committee.
What to do: before you buy for Airbnb, ask for the convenção de condomínio and the minutes of recent assemblies, and prefer buildings designed for short stays, with an explicit clause allowing them. If the building is residential-only, price it as a long-term rental, not as an Airbnb.
Where is long-term rental demand strongest in Brazil?
Which neighborhoods in Brazil have the strongest demand for long-term tenants?
Demand is strongest where jobs and transport meet: Itaim Bibi and Pinheiros in São Paulo, Botafogo and Flamengo in Rio de Janeiro, and Asa Sul in Brasília. Rents show it: in the year to September 2026, FipeZAP asking rents rose 14.8% in Rio, including about 19.5% in Botafogo and Flamengo and 20.2% in Copacabana.
Rents are rising faster than prices almost everywhere: 9.13% nationally, 16.59% in Fortaleza and 6.22% in São Paulo. Florianópolis is the exception, at 3.56%, below inflation. Well-priced apartments in these areas tend to rent quickly, though there's no reliable public vacancy figure by neighborhood.
Different tenant profiles drive demand in each of these neighborhoods:
- Itaim Bibi (São Paulo): finance and tech professionals working in the Faria Lima corridor.
- Pinheiros (São Paulo): creative industry workers and young couples seeking walkable lifestyle.
- Botafogo (Rio de Janeiro): young professionals and graduate students near PUC university.
- Flamengo (Rio de Janeiro): families wanting Zona Sul access at more reasonable rents.
- Asa Sul (Brasília): government employees and diplomats with stable long-term contracts.
What makes these neighborhoods especially attractive to long-term tenants is the combination of reliable public transit access, walkable supermarkets and services, and consistent building security, which together reduce the daily friction that drives tenant turnover elsewhere.
What are the average long-term monthly rents by neighborhood?
A one-bedroom of 35 to 50 square meters rents for about R$ 3,500 to R$ 5,000 a month in Pinheiros, R$ 3,300 to R$ 4,700 in Itaim Bibi and R$ 2,950 to R$ 4,200 in Jardins, based on FipeZAP rents per square meter in September 2026.
In cheaper areas, the same one-bedroom rents for about R$ 2,300 to R$ 3,300 in São Paulo's Centro and República, R$ 1,700 to R$ 2,450 in Água Verde (Curitiba) and R$ 1,450 to R$ 2,050 in Asa Sul (Brasília).
For mid-range areas, expect R$ 2,550 to R$ 3,650 for a one-bedroom in Vila Mariana and R$ 4,400 to R$ 6,200 for a two-bedroom. In Rio, a two-bedroom asks around R$ 5,500 in Botafogo and R$ 5,100 in Barra da Tijuca.
At the top, Leblon and Ipanema ask about R$ 120 per square meter a month, so a 60 square meter apartment runs around R$ 7,000 or more. In Pinheiros, a two-bedroom asks R$ 6,000 to R$ 8,500.
 70+pages
Which areas are up-and-coming in Brazil?
Which neighborhoods in Brazil are gentrifying and attracting new investors?
The clearest cases are near new transit and renewal programs: Barra Funda and Santa Cecília in São Paulo, and Santo Cristo and Gamboa in Rio's port area, along with Glória and Catete in Rio and the edges of Santa Teresa where renovation activity is increasing.
The signal is in rents: QuintoAndar asking rents in Rio's Centro jumped 48.8% in the year to July 2026, helped by the city's Reviver Centro program, which encourages turning old offices into homes. In São Paulo, the city more than doubled the area eligible for Requalifica Centro retrofit incentives in June 2026, from 1,170 to 2,780 hectares.
There's no reliable neighborhood price index for these pockets yet, so treat any promise of fast growth with caution. Buy on today's rent, not on the story.
Which areas in Brazil have major infrastructure projects planned that will boost prices?
The biggest one is São Paulo's Metro Line 6-Orange: its first six stations (João Paulo I, Freguesia do Ó, Santa Marina, Água Branca, Sesc-Pompeia and Perdizes) opened on 3 July 2026. Nine more, including Higienópolis-Mackenzie, PUC-Cardoso de Almeida, FAAP-Pacaembu, Bela Vista and São Joaquim, are still to come.
Elsewhere, Rio's port area keeps its Porto Maravilha and VLT tram links, Fortaleza opened a 2.4 km VLT branch to the airport via Mucuripe in February 2026, and Florianópolis is widening the SC-401 road toward the northern beaches.
Historically in Brazil, neighborhoods within a 10-minute walk of new metro stations have seen price increases of 15% to 30% within two to three years of line completion. That's our estimate, and timing these investments requires patience as project delays are common.
Which areas should you avoid as a property investor in Brazil?
Which neighborhoods in Brazil with lots of problems should I avoid and why?
Approach with caution certain blocks of Rio's Centro that remain isolated from revitalization, the oversupplied micro-studio zones of São Paulo's República, and any building with unclear condominium rules on rentals.
Each of these problem areas has specific issues investors should understand:
- Centro/Porto edges (Rio de Janeiro): security remains inconsistent block-by-block despite headlines.
- República (São Paulo): the 8% yield on paper comes with a flood of small studios, which limits pricing power.
- Buildings with hostile short-stay rules: after the STJ's 2026 ruling, a two-thirds owner vote can block Airbnb.
- Flood-prone streets: specific blocks face recurring water damage; Florianópolis got about 350 mm of rain in 24 hours in January 2025.
In São Paulo, water is the new worry. The Cantareira reservoir was at 41.1% at the end of September 2026 and entered the "attention" band on 1 October, and water pressure is being cut for 8 hours a night. Check that the building has a large enough water tank (caixa d'água) before you buy.
For these problem areas to become viable investments, they would need sustained improvements in daily security and street-level infrastructure, not just headline-grabbing projects, combined with absorption of existing oversupply before new inventory arrives.
Which areas in Brazil have stagnant or declining property prices as of 2026?
São Paulo is the clearest case: FipeZAP asking prices rose 3.64% in the year to September 2026, a 0.9% fall after inflation. Within the city, Pinheiros slipped 0.3% and Vila Mariana gained only 0.4%, while Itaim Bibi rose 3.4%.
Nationally, prices rose 5.51%, only 0.89% above inflation. Unsold new units reached 355,290 at the end of June 2026, 8.2% more than a year earlier, which weighs on new-build corridors where many similar towers launched at once.
The underlying causes of price weakness differ across these areas:
- Oversupplied new-build zones: too many identical studio towers competing on price, not quality.
- High-fee older towers: condo fees of R$ 2,000 or more, against an average of R$ 842 on São Paulo listings (Loft, 2026), make ownership expensive.
- Weak job growth locations: rents cannot keep pace when local employment options decline.
 70+pages
Which areas in Brazil have the best long-term growth potential?
Which areas in Brazil have historically appreciated the most recently?
Florianópolis stands out: its asking prices rose about 64.2% over the five years to September 2026, according to a calculation from FipeZAP data. Over the last year alone, the biggest gainers among well-known areas were Leblon (+13.2%), Ipanema (+10.3%) and Copacabana (+9.9%) in Rio, and Barra (+15%) and Graça (+13.8%) in Salvador.
Over the longer run, the prime pockets of São Paulo's Pinheiros and Jardins, Rio's Leblon and Ipanema, and Florianópolis's Jurerê and Campeche have led the market. There's no reliable public ten-year index for each neighborhood, so we don't give exact figures.
The main driver of above-average appreciation in these areas has been the combination of genuine supply constraints from geography or zoning, durable high-income employment nearby, and improving local amenities that attracted both owner-occupiers and investors willing to pay premiums.
Which neighborhoods in Brazil are expected to see price growth in coming years?
A FipeZAP-based model expects the fastest growth over the next 12 months in Fortaleza (8.52%), Salvador (7.43%) and Florianópolis (7.17%), ahead of Rio (6.48%) and São Paulo (3.69%), against 5.42% nationally. Buyers are more cautious: in FipeZAP's survey, they expected 2.5%.
At the neighborhood level, the best bets combine reasonable prices with rising rents: Botafogo and Flamengo in Rio (rents up about 19.5%), Vila Mariana and Perdizes in São Paulo (Perdizes now has a Line 6-Orange station), and Aldeota in Fortaleza (rents up 34.2%).
The single most important catalyst expected to drive future price growth in these neighborhoods is the continued tightening of rental markets, which signals underlying demand that eventually translates into purchase price increases as more renters become buyers. With the Selic at 13.75%, that shift will be slow until credit gets cheaper.
What do locals and expats really think about different areas in Brazil?
Which areas in Brazil do local residents consider the most desirable to live?
Locals rank Vila Nova Conceição and Jardim Europa in São Paulo, Leblon and Jardim Botânico in Rio de Janeiro, Lago Sul in Brasília, and Batel in Curitiba (R$ 17,575 per square meter, the city's priciest) as the most desirable places to live.
Each of these locally preferred neighborhoods stands out for specific reasons:
- Vila Nova Conceição (São Paulo): quiet tree-lined streets with top schools and Ibirapuera access.
- Leblon (Rio de Janeiro): beach lifestyle combined with restaurants and perceived safety.
- Jardim Botânico (Rio de Janeiro): green spaces, cultural venues, and family-friendly atmosphere.
- Lago Sul (Brasília): large houses, lake views, and proximity to embassies and top hospitals.
- Batel (Curitiba): walkable shopping, dining, and consistent building quality.
These locally preferred areas tend to attract upper-middle-class families, established professionals, and business owners who prioritize security, school quality, and daily convenience over maximizing space or minimizing price.
Local preferences often align with foreign investor targets in prime zones, but locals also value mid-market neighborhoods with good schools that foreigners typically overlook, such as Perdizes in São Paulo (R$ 13,455 per square meter) or Laranjeiras in Rio (R$ 11,092).
Which neighborhoods in Brazil have the best reputation among expat communities?
Expats favor Itaim Bibi, Pinheiros and Jardins in São Paulo, Ipanema and Leblon in Rio de Janeiro, and Lagoa da Conceição in Florianópolis, where a one-bedroom rents for about R$ 3,500 to R$ 6,500 a month.
Expats prefer these neighborhoods over others for practical reasons:
- Itaim Bibi (São Paulo): English-friendly services, international restaurants, and corporate proximity.
- Pinheiros (São Paulo): walkable lifestyle with cafes, coworking spaces, and cultural events.
- Ipanema (Rio de Janeiro): beach access, safety perception, and tourist infrastructure.
- Leblon (Rio de Janeiro): highest perceived security and premium dining options in Rio.
- Lagoa da Conceição (Florianópolis): surf culture, natural beauty, and remote work community.
The typical expat profile in these neighborhoods includes corporate transferees in São Paulo's business districts, digital nomads and entrepreneurs in lifestyle areas, and retirees seeking beach access with modern amenities in coastal zones.
Which areas in Brazil do locals say are overhyped by foreign buyers?
Locals often point to Copacabana for its name, certain Porto revitalization blocks in Rio that remain unfinished, and beachfront Florianópolis, where Argentinians made up 83% of the foreign purchase activity analyzed by the local brokers' council.
Locals believe these areas are overvalued for specific reasons:
- Copacabana (Rio de Janeiro): aging building stock and density issues despite the famous name.
- Porto/Centro edges (Rio de Janeiro): revitalization progress is slower than marketing suggests.
- Jurerê Internacional (Florianópolis): seasonal demand means empty streets for much of the year.
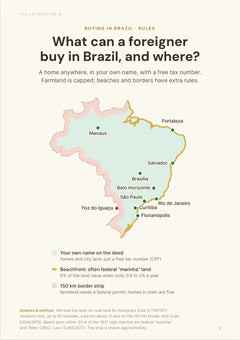
A "beach" apartment also doesn't mean a swimmable beach. In mid-October 2026, only 11 of 38 sampling points in Salvador were fit for swimming, and in Rio, Ipanema had 1 of 3 and Botafogo 0 of 2, while Leblon and Copacabana had all theirs fit. These are weekly readings, so look at several months before paying a sea-view premium.
Foreign buyers typically see brand recognition and beach proximity in these areas, while locals focus more on daily livability factors like building maintenance, year-round street activity, and realistic rental income potential that often falls short of foreigner expectations.
Which areas in Brazil are considered boring or undesirable by residents?
Residents commonly dislike car-dependent suburban developments far from metro lines, purely residential blocks without street retail or restaurants, and neighborhoods with inconsistent security that creates daily stress.
Residents find these area types unappealing for straightforward reasons:
- Car-dependent suburbs: long commutes and lack of walkable amenities reduce quality of life.
- Purely residential blocks: no cafes or services means driving for every small errand.
- Security-inconsistent zones: the stress of telling safe from unsafe streets every day.
- High-rise monocultures: identical towers without neighborhood character or community feel.
Our methodology
This article compares Brazil's main cities and neighborhoods on price, price growth, rental yield, Airbnb performance, rental demand and risk, to show where buying makes the most sense for a foreign investor today.
Prices, rents and yields come from the FipeZAP indexes for September 2026, by city and by neighborhood, compared with IBGE's IPCA inflation. Airbnb figures come from AirROI only, and forecasts from a model based on FipeZAP. Where we give our own estimate (prime-address prices, growth near new metro stations, neighborhood rankings), we say so.
Rules come from official sources: the STJ for the 2026 rulings on short-term rentals in condominiums, Receita Federal for the 15% tax on a non-resident's rent, and city and state governments for renewal programs, transit projects and water supply.
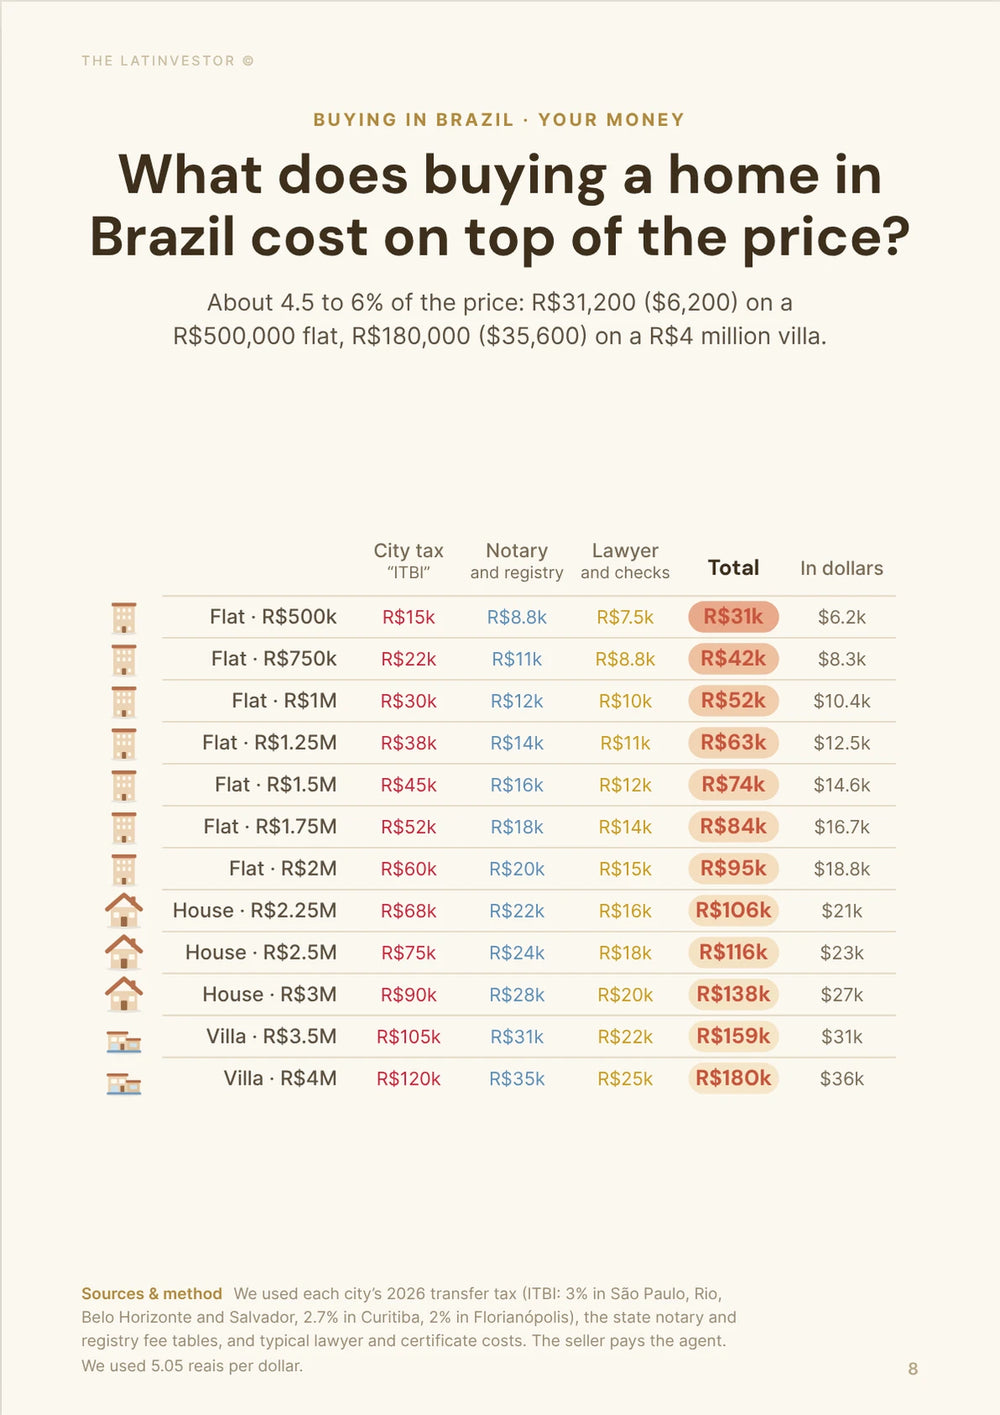
We checked these figures in October 2026. Conversions use about 5.05 reais per US dollar and 5.65 reais per euro.
FipeZAP measures asking prices and rents, not final deals, and buyers report average discounts of 9% to 14%. Neighborhood yields are gross and estimated, and city averages hide big gaps from one block to the next.
Key sources used for this analysis include FipeZAP sale index (September 2026), FipeZAP rent index (September 2026), Hasta (FipeZAP data and model), MySide (São Paulo neighborhoods), MySide (Rio neighborhoods), FipeZAP Raio-X discount survey, IBGE IPCA, Banco Central do Brasil (Selic), CBIC, AirROI (Rio de Janeiro), AirROI (São Paulo), InsideAirbnb, STJ (May 2026), STJ (Tema 1.443), Exame (São Paulo HIS rules), Receita Federal, ADEMI-RJ (QuintoAndar rents), Prefeitura do Rio (Reviver Centro), Prefeitura de São Paulo (Requalifica Centro), Poder360 (Line 6-Orange), Governo do Ceará (VLT), ANA (Cantareira), Ceni & Southier, Registro de Imóveis do Brasil, Tô Em Casa (beach tests), QuintoAndar and Portas (condo fees).