


Summary
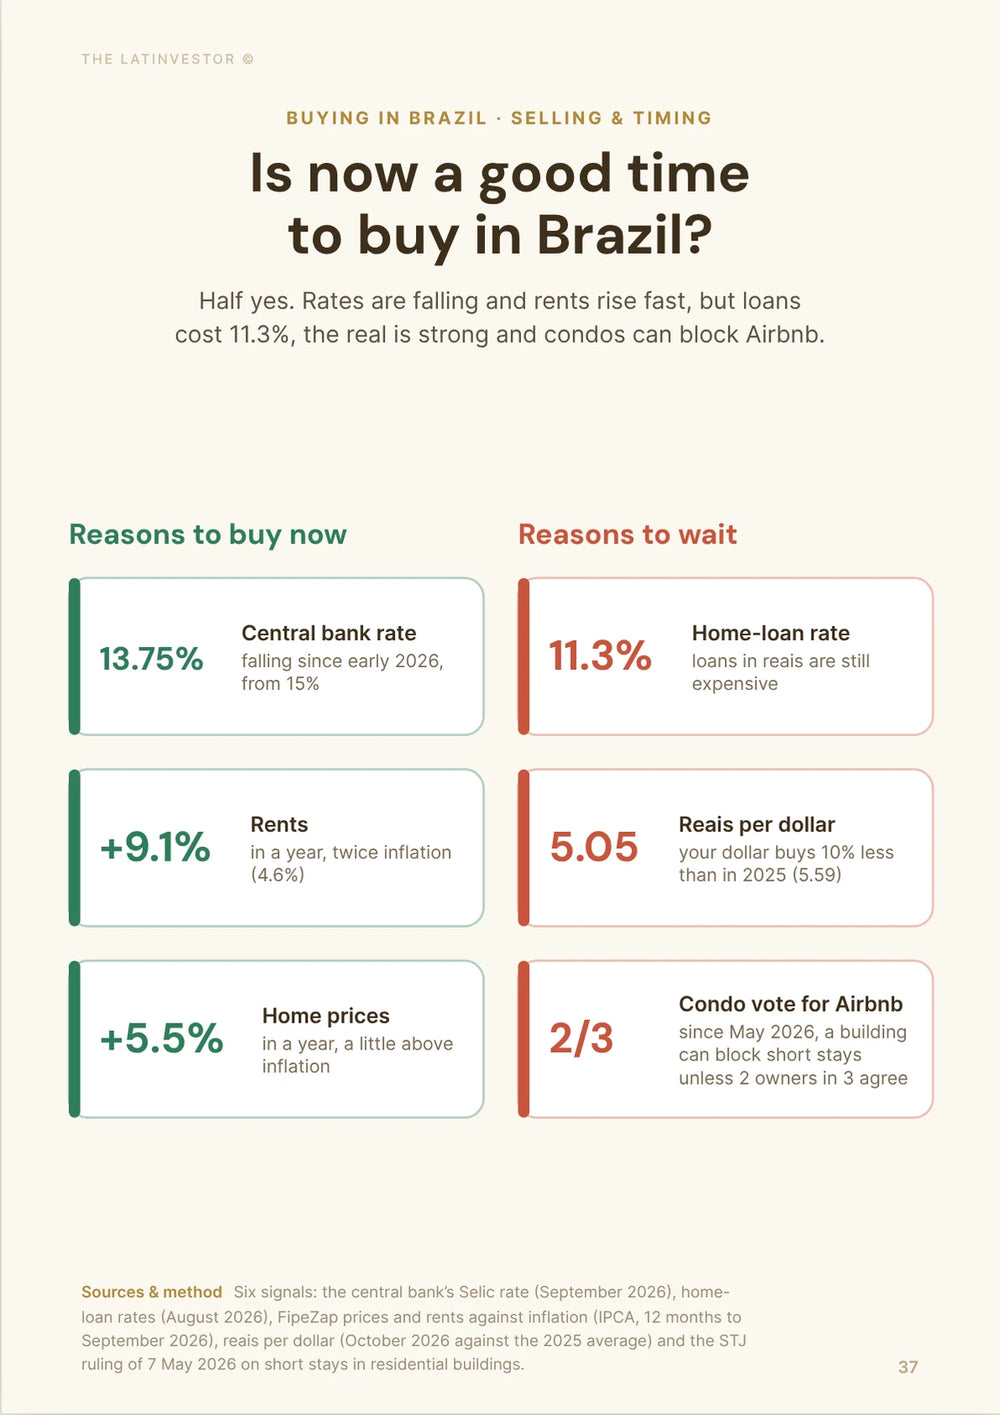
Yes for a cash buyer who wants rental income, less so for anyone betting on fast price gains. FipeZAP asking prices rose 5.51% in the year to September 2026, only 0.89% after inflation, while rents rose 9.13%.
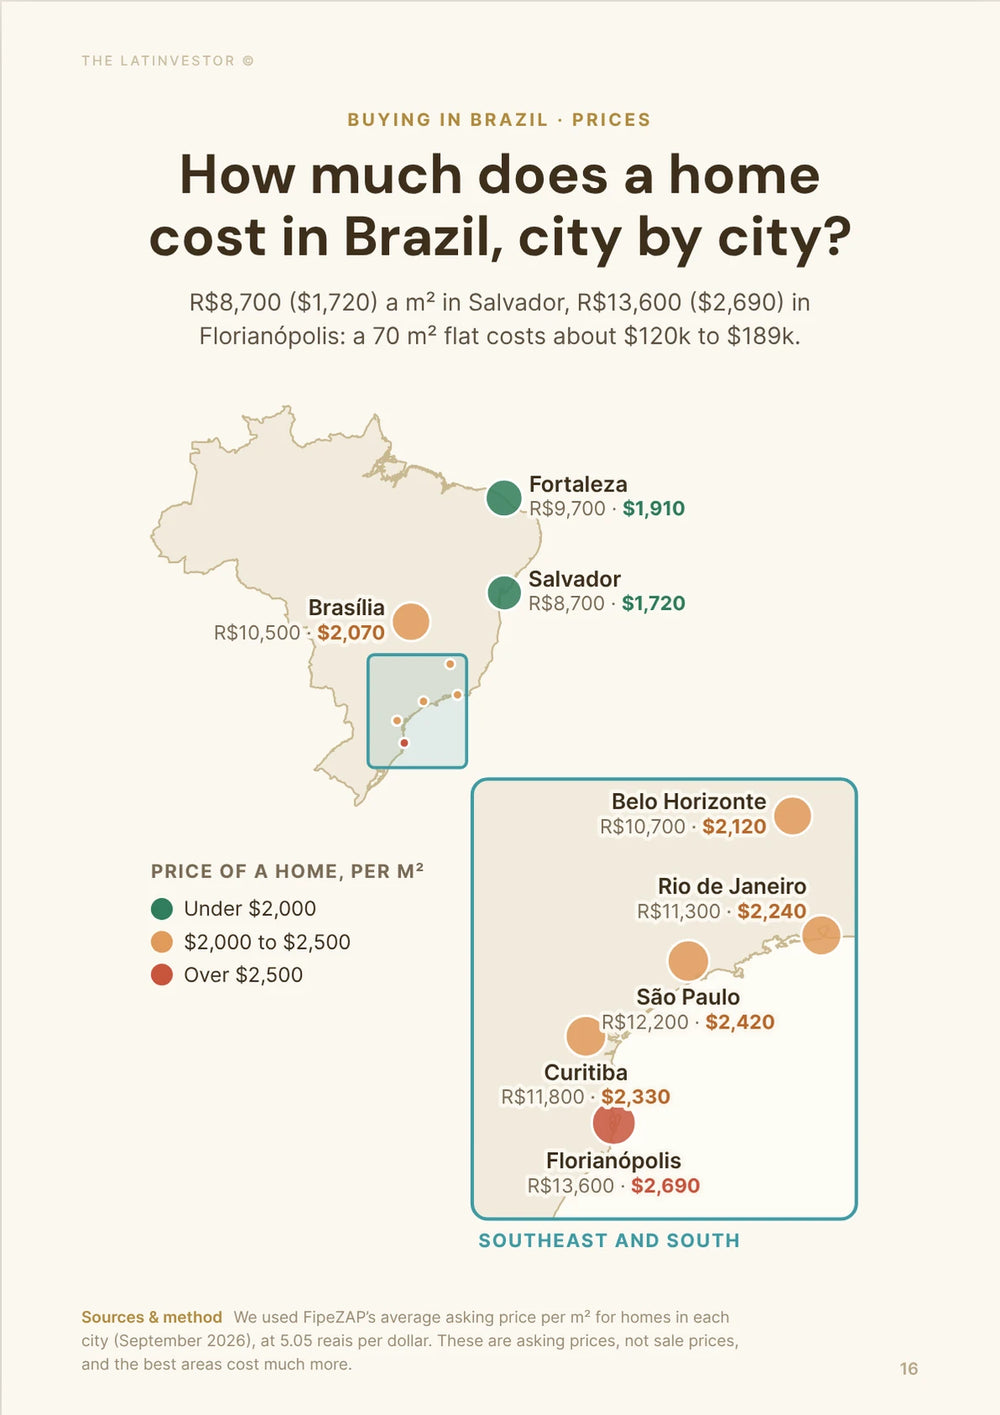
Prices aren't running away: the national average is BRL 10,015 per square meter (about USD 1,980), and buyers report an average discount of 9% off asking, 14% when they negotiate one.
A crash looks unlikely, but so does a boom. Buyers surveyed by FipeZAP expect 2.5% growth over 12 months, and a FipeZAP-based model points to about 5.4%.
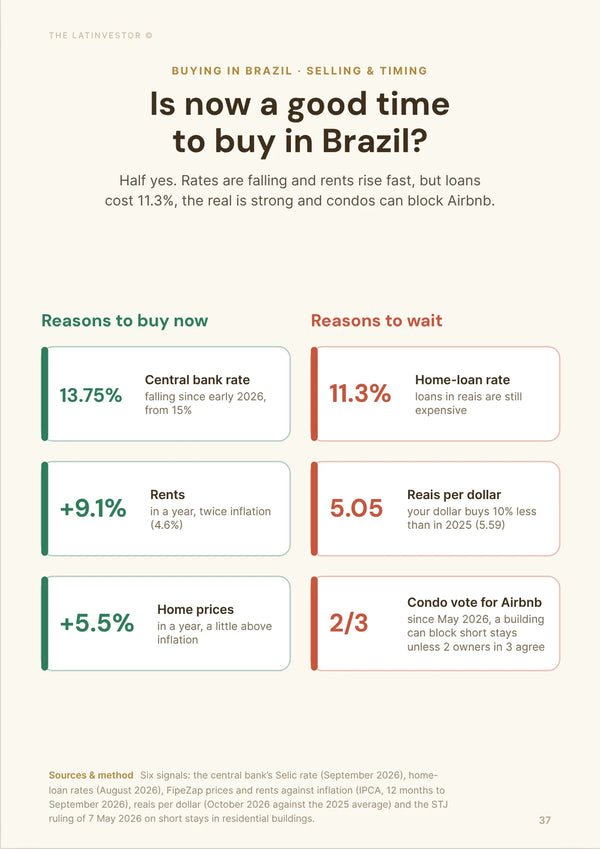
Don't wait for cheap credit. The Selic was cut from 14% to 13.75% in September 2026 and the market expected only 13.25% by year end. Non-residents rarely get a mortgage anyway.
For dollar buyers, Brazil got about 17% more expensive in a year, because prices rose in reais and the real is stronger than its 2025 average.
The presidential runoff between Lula and Flávio Bolsonaro is on 25 October 2026. It doesn't change what foreigners can buy, but it can move the real, so don't change your whole budget into reais in one go.
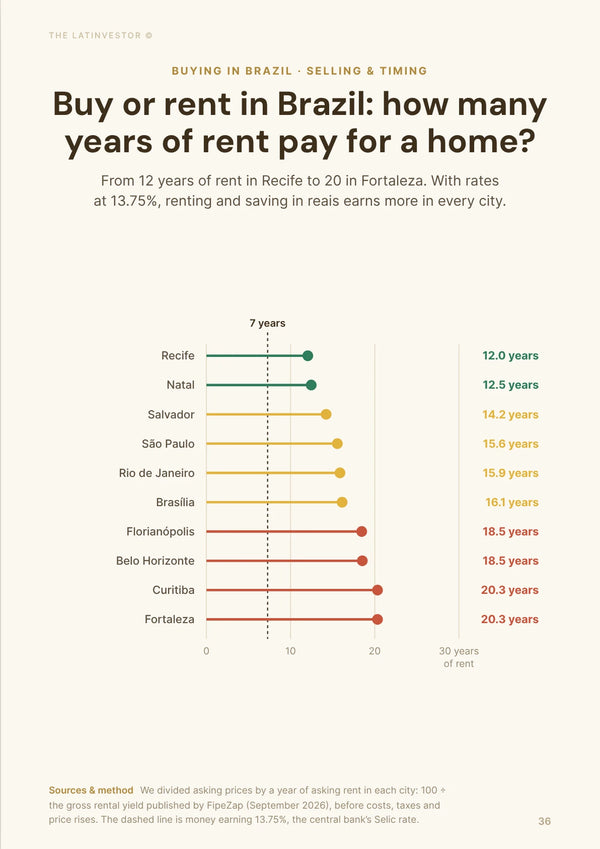
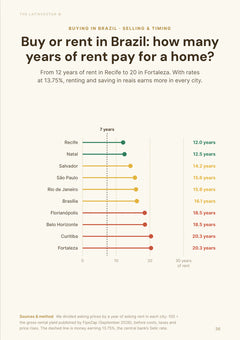
Against rents, prices look fair: FipeZAP's gross yield of 6.13% means about 16 years of rent to pay for an apartment. Against local incomes, they look expensive.
Local catalysts are city-level: Novo PAC mobility projects and São Paulo's new outorga onerosa land values, which make new projects in Pinheiros or Vila Mariana more expensive to build.
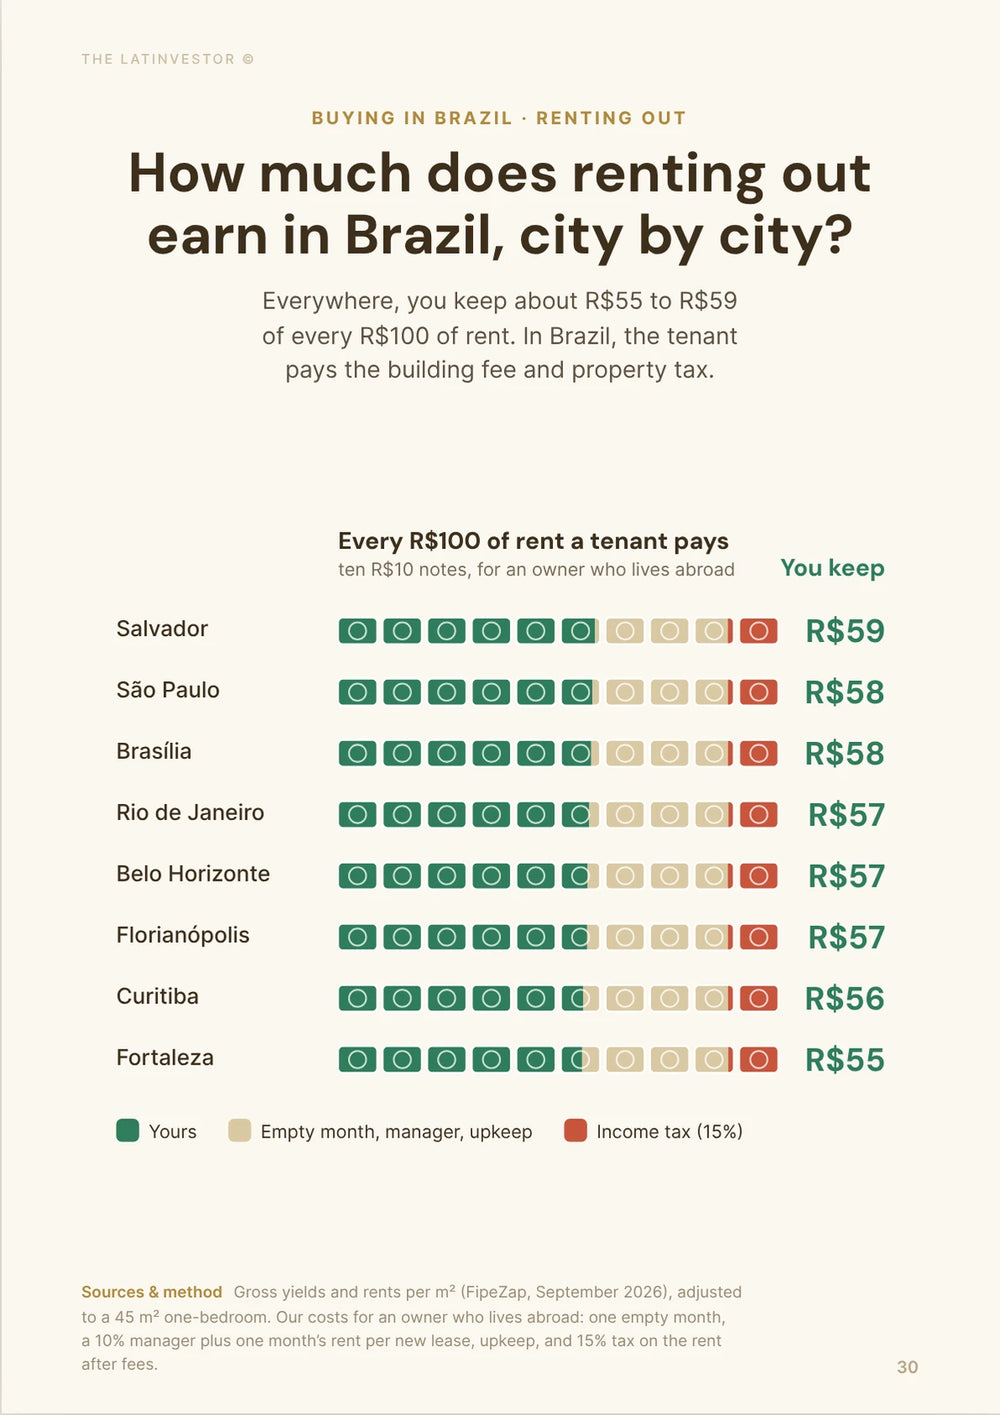
Tenants are easy to find in the right places, because high rates keep people renting. A non-resident pays 15% tax withheld on gross rent, which takes a 6.13% gross yield to about 5.2%.
New-build stock is not shrinking: 355,290 unsold new units at the end of June 2026, 8.2% more than a year earlier, which gives buyers room to negotiate on mid- and high-end projects.
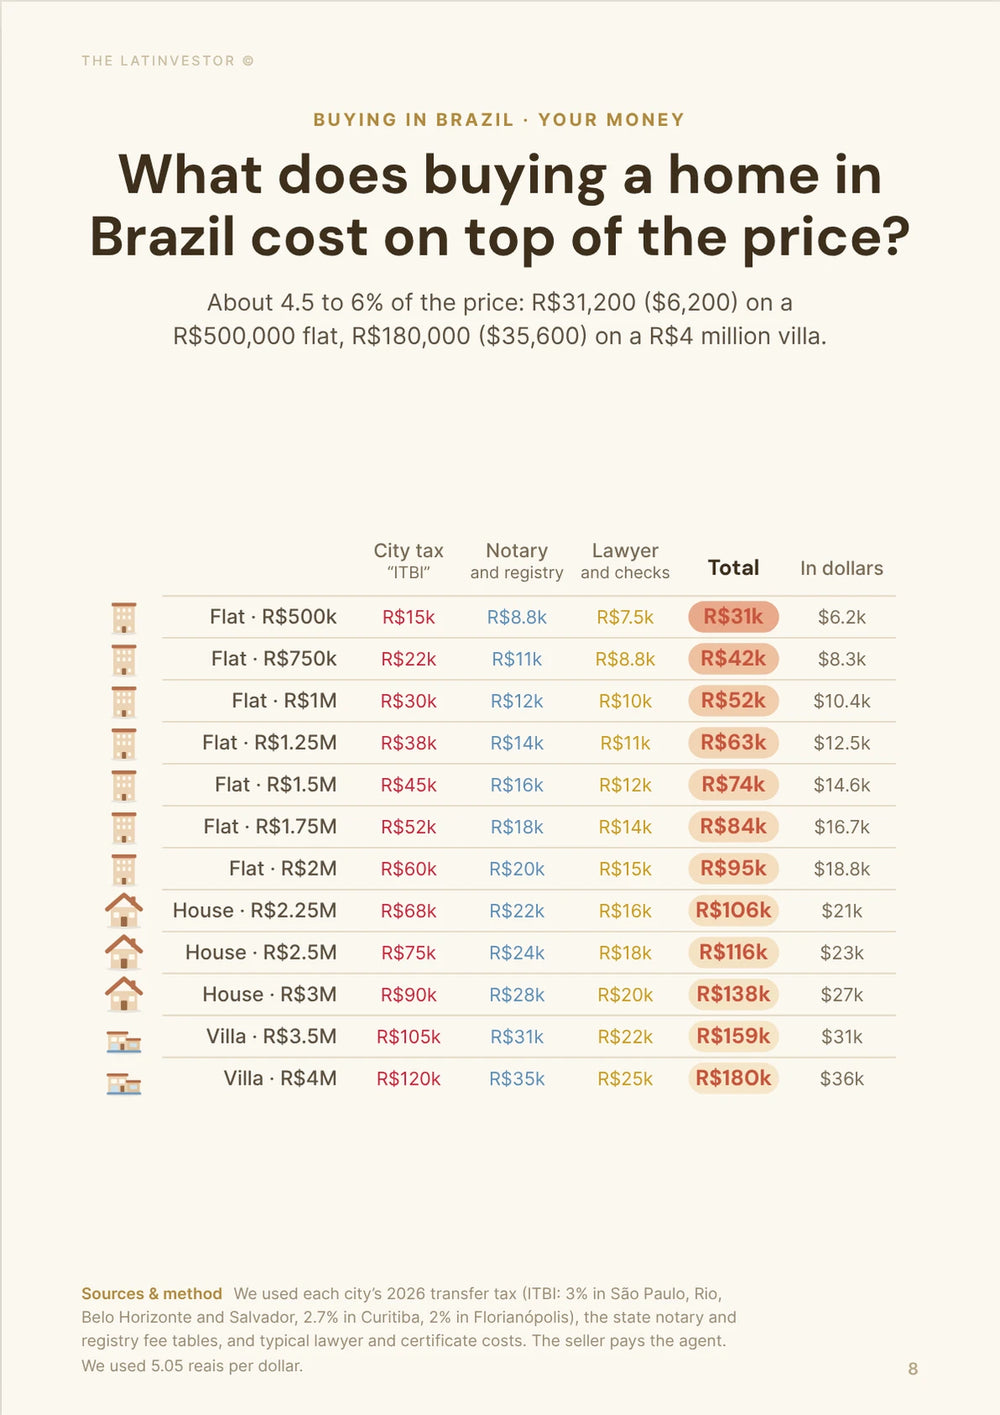
Plan to hold at least five years. Buying costs 4% to 6% and the agent's commission on resale is 6% to 8%, so a round trip costs about 10% to 14% before tax.
Bottom line: buy a liquid, well-located city apartment, in cash, at a real discount to asking, and judge it on its rent, not on a quick resale. This is not financial advice.


Is it smart to buy now in Brazil, or should you wait?
Do prices look too high in Brazil right now?
Not much, in our view. Mainstream city apartments look close to fair value, maybe 0% to 8% above it by our estimate, while prime beachfront and luxury areas can look 15% to 30% expensive compared with what they rent for.
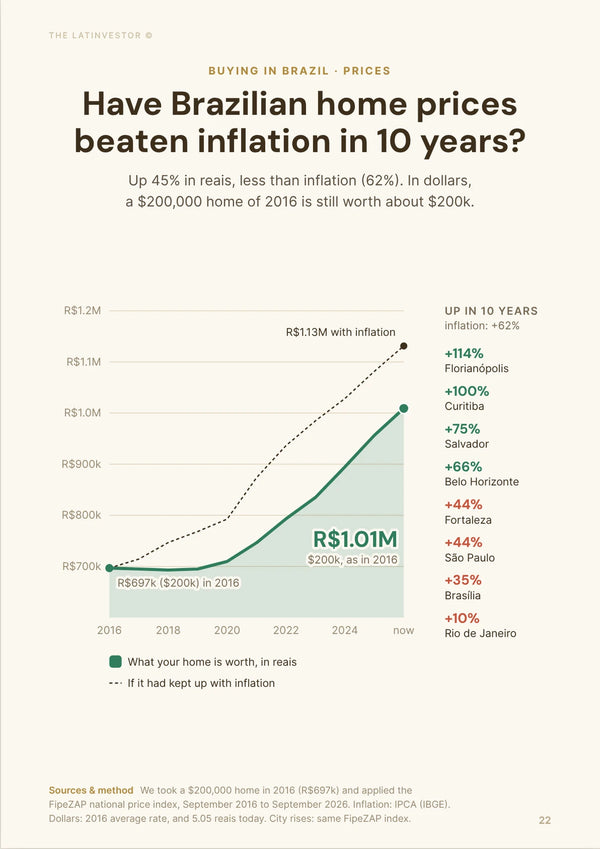
FipeZAP's national asking price was BRL 10,015 per square meter in September 2026 (about USD 1,980), up 5.51% in a year. With inflation at 4.58%, the real gain was 0.89%. That's a firm market, not a euphoric one.
Rents rose 9.13% over the same period, faster than prices, so today's price level is backed by real tenant demand rather than speculation.
Could prices drop in Brazil over the next year?
The risk of a real drop looks low to medium, and it's concentrated in expensive new builds and investor-heavy areas.
Our working range for the next 12 months is roughly -5% to +7% in reais, with weaker mid- and high-end stock near the bottom and affordable or rental-heavy stock near the top. In past downturns, nominal prices barely fell; inflation did the damage, so the more likely risk is flat prices that lose value in real terms.
The warning signs to watch are already there: unsold new units up 8.2% in a year, and contract cancellations at the big developers up 41.4% in Q1 2026. A severe nationwide drop would still need high rates to combine with job losses and forced selling.
Could prices jump again in Brazil?
Not broadly. Buyers surveyed by FipeZAP in April 2026 expected prices to rise 2.5% over 12 months, and Hasta's model based on FipeZAP data projects about 5.42% to September 2027, to BRL 10,558 per square meter.
The upside is in small apartments near jobs and transit, where we think 5% to 10% a year is possible if credit gets cheaper. Luxury areas that are already expensive have less room.
The trigger would be a clear fall in the Selic, because many Brazilian buyers are waiting for mortgages to get less painful. That's coming slowly, not suddenly.
Is it a buyer's or a seller's market?
Mixed. Buyers have the upper hand in many mid- and high-end projects and resale homes, while sellers still hold it for affordable, well-located rental apartments.
Developers had 355,290 unsold new units at the end of June 2026, 8.2% more than a year earlier, and ABRAINC counted 14.8 months of unsold supply in the mid- and high-end segment in March 2026. That's room to negotiate.
Discounts are real: in FipeZAP's Q2 2026 buyer survey, the average discount was 9% across all purchases, and 14% among buyers who got one. Treat 10% below asking as a normal target on anything that isn't scarce.
 Brazil Property Market
This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
Should you wait for lower interest rates before buying in Brazil?
No, especially if you pay cash. The Copom cut the Selic from 14% to 13.75% on 16 September 2026, and in mid-October the Focus survey expected only 13.25% by the end of 2026 and about 12% by the end of 2027. The next Copom meeting is on 3 and 4 November.
Mortgages are still expensive: in September 2026, regulated housing loans averaged about 7.98% a year plus TR at Caixa, against 11.77% at Bradesco, 11.85% at Santander and 11.87% at Itaú. Lending is growing anyway, with savings-funded mortgages up 37.5% from January to August, to BRL 132.5 billion.
For a foreigner, rate cuts change little. Banks usually ask for Brazilian nationality, naturalization or permanent residency, so non-residents almost always buy cash. While credit stays this expensive, cash buyers are rare and sellers know it: use that to negotiate now, rather than wait for cuts that will also bring local buyers back.
Is Brazil still cheap if you pay in dollars or euros?
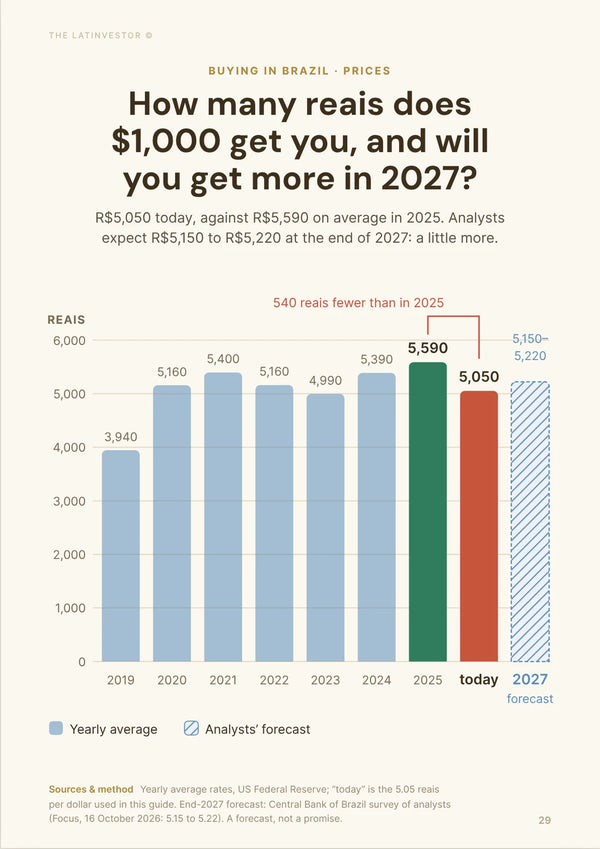
Less than a year ago. For a dollar buyer, Brazil got about 17% more expensive in 12 months: prices rose 5.51% in reais, and the real is about 10% stronger than its 2025 average.
A property worth R$1 million today costs about $198,000 at 5.05 reais per dollar. A year earlier, the same property was worth about R$948,000, which was about $170,000 at the 2025 average rate of 5.59 reais per dollar.
Forecasters don't expect a big swing back: the Focus survey expects about 5.13 reais per dollar at the end of 2026, and Itaú about 5.30. Don't stretch your budget on the hope that the real will weaken. Negotiate harder on price instead, since that's the part you control.
Does the October 2026 election change anything for buyers?
Not the rules, but possibly the exchange rate. Flávio Bolsonaro and President Lula finished close in the first round on 4 October 2026 and meet in a runoff on 25 October. Polls before the runoff showed a tight race.
Neither result changes what a foreigner can buy: urban property stays open to non-residents with a CPF. What can move is the real, and with it the dollar price of everything in this article. On 19 October, the dollar closed at about 5.05 reais.
What to do: if you're already negotiating, don't stop because of the election. Agree the price in reais, and move your money in two or three transfers rather than all at once, so one bad week for the currency doesn't decide your budget. If you haven't started looking, there's no reason to rush a currency exchange before the result.
 70+pages
Are homes overpriced or fairly priced in Brazil?
Are homes overpriced compared with rents and incomes?
Fair against rents, expensive against incomes. FipeZAP's gross yield was 6.13% in September 2026, which means about 16 years of gross rent to pay for an apartment, and 6.74% for 1-bedroom units. Coastal trophy and luxury markets rent for much less than that.
Against local salaries it's harder: by our estimate, a middle-class apartment in São Paulo or Rio costs 8 to 12 years of household income, against 4 to 6 years in a comfortable market. With mortgages at 8% to 12% a year, many locals rent instead, which is good news for landlords.
Are prices above their long-term average?
In reais, yes. After inflation, only a little, and mostly in the strongest capitals.
The last 12 months brought 5.51% nominal growth and 0.89% real growth, much calmer than the boom before the 2014 downturn. Inflation and high rates have absorbed most of the nominal increase since then, so mainstream markets are not far above their previous peak in real terms.
What local changes could move prices in Brazil?
Are big infrastructure projects coming?
Yes, but their effect is local. The main one is Novo PAC, especially urban mobility, sanitation, drainage and housing projects, plus São Paulo Metro Line 6 and Rio's port area.
Timelines are uneven, because Novo PAC projects go from federal selection to local contracts and construction at very different speeds. The strongest price effect will likely show between now and the early 2030s, near projects that actually cut commute times. Don't pay a premium for a line that only exists on paper.
Are zoning or building rules changing?
At city level, yes. The clearest example is São Paulo's update of the land values used to calculate the outorga onerosa, the fee developers pay to build above the basic allowance.
It makes new projects more expensive in high-demand areas, which supports prices of existing apartments there. The areas most affected are dense São Paulo neighborhoods and corridors such as Pinheiros, Vila Mariana, Butantã, Tatuapé, Barra Funda and Vila Prudente.
Are foreign-buyer, mortgage or rental rules changing?
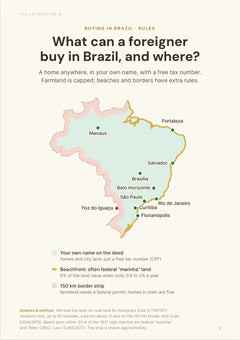
Foreign-buyer rules aren't. A non-resident can still buy an urban house or apartment in their own name; the restrictions concern rural land (Lei 5.709/1971 and INCRA) and rural property within 150 km of the land borders.
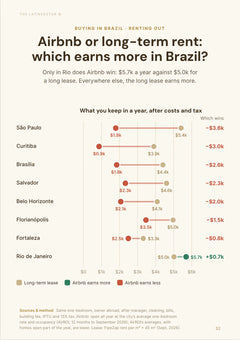
What did change in 2026 is short-term renting. On 7 May 2026, the STJ ruled that professionally run short stays don't fit an exclusively residential condominium unless two-thirds of the owners vote for it, and on 17 September it picked the question for a binding ruling (Tema 1.443), which is still pending. If your plan relies on Airbnb, check the building's convenção and latest assembly minutes before you sign.
On the mortgage side, the support goes to Minha Casa Minha Vida, the subsidized program for lower-income Brazilian families, not to market-rate loans or foreign buyers.
 70+pages
Will it be easy to find tenants in Brazil?
Is renter demand growing faster than supply?
In the best city areas, yes. High mortgage rates keep young workers and middle-income families renting longer in São Paulo, Rio, Brasília, Belo Horizonte, Curitiba, Recife, Fortaleza and Goiânia, and FipeZAP asking rents rose 9.13% in a year, to BRL 54.77 per square meter across 36 cities.
Supply is more mixed. Brazil builds a lot, but not enough affordable, rental-ready apartments near jobs, metro lines, universities and hospitals.
Are rentals letting faster?
In prime apartment areas, yes. From our own portal checks, well-priced small units in the strongest neighborhoods often let in about three to five weeks, while overpriced or badly located units can take two to three months or more. Brazil has no official days-on-market figure for rentals, so treat this as an estimate.
The reason is simple: households priced out of buying compete for the same small apartments near transit, hospitals, universities and offices.
Are vacancies dropping in the best areas?
Effective vacancy looks low in Pinheiros, Vila Mariana, Bela Vista and Tatuapé in São Paulo, Botafogo and Tijuca in Rio, Savassi in Belo Horizonte, Batel and Água Verde in Curitiba, and Boa Viagem in Recife.
By our estimate, a well-priced small apartment there sits empty about 3% to 5% of the year, against 7% to 12% for generic stock in weaker locations. Landlords in these areas can choose tenants with stronger proof of income.
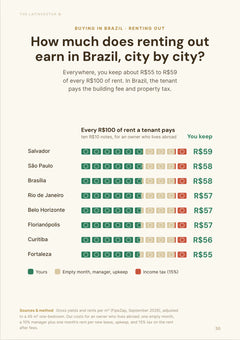
Two things to price in: in a long-term lease, the tenant pays the condo fees and IPTU (Lei 8.245, art. 23), and if you live abroad, 15% of the gross rent is withheld as tax. That takes FipeZAP's 6.13% gross yield to about 5.2% before vacancy and management.
Is the market tightening in Brazil?
Is for-sale inventory shrinking?
No. Unsold new units reached 355,290 at the end of June 2026, 8.2% more than a year earlier, even if that dipped 2.1% from March. Minha Casa Minha Vida stock is tighter than mid- and high-end projects, where ABRAINC counted 14.8 months of supply.
Are homes selling faster?
New homes, a bit. Developers sold 226,536 new units in the first half of 2026, 5.4% more than a year earlier, helped by Minha Casa Minha Vida.
Mid- and high-end resale homes aren't clearly selling faster, because mortgages are still expensive. Our reading is that selling time is stable to slightly longer for market-rate resale, and shorter for well-priced affordable units.
Are new launches slowing down?
They've stopped growing. Developers launched 211,651 new homes in the first half of 2026, against 212,338 a year earlier.
The reason is caution: land, construction, financing and buyer credit are all expensive. Read quarterly figures carefully, because holiday periods weigh on activity.
Is new construction failing to keep up?
Not overall. It fails where it matters most for a landlord: affordable, central apartments near transit in the strongest cities.
The bottleneck isn't the number of units, it's the lack of cheap, well-located land to build apartments that normal tenants and buyers can afford.
 70+pages
Will it be easy to sell later in Brazil?
Is resale liquidity strong enough?
For mainstream apartments in known neighborhoods, yes. For luxury homes, remote gated properties and overpriced beach houses, much less.
By our estimate, a well-priced apartment in a big capital takes about two to four months to sell. What helps most is a practical location: a safe area near jobs, transport, shops, schools or hospitals.
Is selling time getting longer?
For expensive homes that need a financed buyer, probably. For good small apartments in high-demand rental areas, no.
Our estimate is two to four months for liquid mainstream apartments, and six months or more for overpriced, large or badly located properties. The reason is credit: at 8% to 12% a year, fewer buyers can comfortably make an offer.
Is it realistic to sell at a profit?
For a good apartment held long enough, yes. For a rushed resale of an overpriced or hard-to-sell property, rarely.
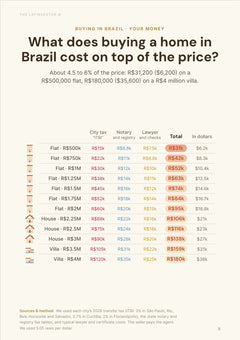
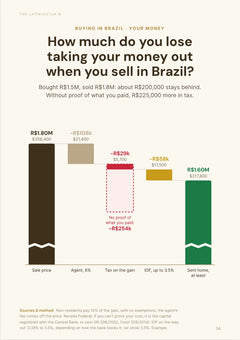
Plan on at least five years. Buying costs about 4% to 6% (ITBI and registry fees), and the agent's commission when you sell is usually 6% to 8%. That's about 10% to 14% for the round trip, or R$100,000 to R$140,000 on a R$1 million home (about $19,800 to $27,700, or €17,700 to €24,800), before capital gains tax of 15% on gains up to R$5 million.
What helps most is buying below asking in a liquid rental neighborhood: the rent gives you time, and resale demand protects your exit.
Our methodology
This article estimates whether now is a good time to buy property in Brazil: how prices compare with rents, incomes and the past, where the market could go in 12 months, how easy it is to rent and resell, and what the Selic, the real and the 2026 election change for a foreign buyer.
Prices and rents come from the FipeZAP indexes for September 2026, compared with IBGE's IPCA inflation. New-build supply and sales come from CBIC and ABRAINC-Fipe, the Selic and mortgage rates from the Banco Central do Brasil, mortgage volumes from ABECIP, and forecasts from the Focus survey, the FipeZAP Raio-X buyer survey and Hasta's FipeZAP-based model. Where a figure is our own estimate (fair value, vacancy, letting and resale times, income multiples), we say so.
Rules come from official sources: INCRA and Lei 5.709/1971 for rural land, Receita Federal for the CPF and taxes, Lei 8.245 for leases, and the STJ for the 2026 rulings on short-term rentals in condominiums. Election results come from TSE figures reported in the press.
We checked these figures in October 2026. Conversions use about 5.05 reais per US dollar and 5.65 reais per euro.
FipeZAP measures asking prices, not sale prices, and buyers report average discounts of 9% to 14%. CBIC and ABRAINC cover new developments only, and national figures hide big gaps between cities.
Key sources used for this analysis include FipeZAP sale index (September 2026), FipeZAP rent index (September 2026), FipeZAP Raio-X, FipeZAP discount survey via Portas, IBGE IPCA, CBIC, ABRAINC-Fipe, Banco Central do Brasil (Selic), Banco Central do Brasil (mortgage rates), Focus survey, ABECIP, Hasta, US Federal Reserve, STJ (May 2026), INCRA, Receita Federal and O Povo (TSE results).