
Summary
Up, but slowly. FipeZAP asking prices rose 5.51% in the year to September 2026, to BRL 10,015 per square meter (about USD 1,980). Inflation was 4.58%, so the real gain was only 0.89%.
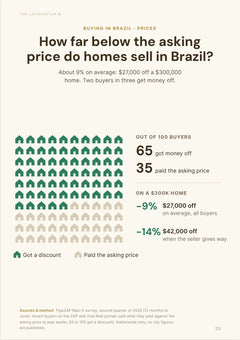
A typical 70 square meter apartment is listed at around BRL 700,000 (about USD 139,000), and buyers report paying 9% below asking on average.
Small units lead: 1-bedroom apartments rose 7.48% in a year, against 3.87% for 3-bedrooms.
The heat is in the Northeast and Espírito Santo. Vila Velha rose 14.76%, Salvador 10.38% and Fortaleza 10.2%, while São Paulo managed 3.64% and Curitiba and Belo Horizonte under 2%, less than inflation.
Building costs are rising faster than home prices: the INCC was up 6.66% in the year to September, against 5.51% for FipeZAP asking prices.
Forecasts for the next 12 months are modest. Buyers in the FipeZAP survey expect 2.5%, a FipeZAP-based model points to 5.42%, and our base case is 4% to 6%, so roughly flat after inflation.
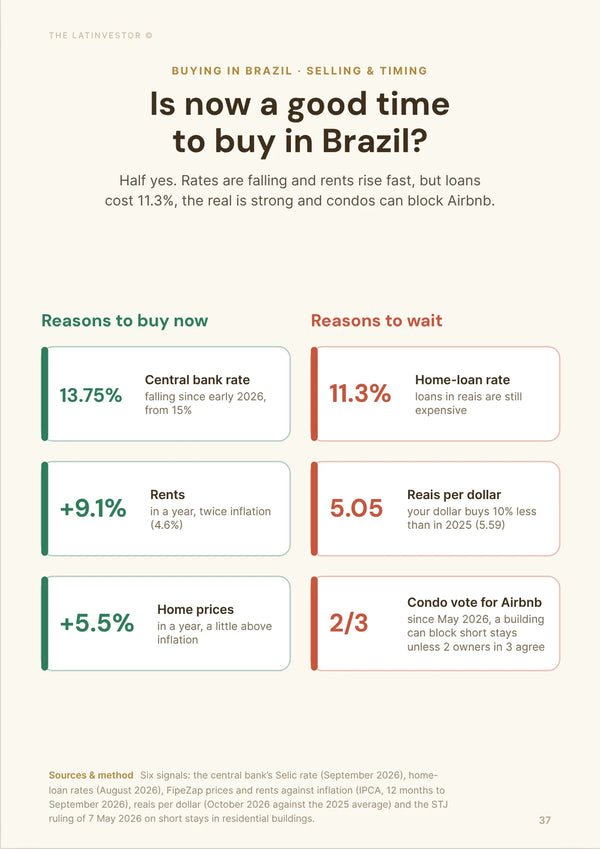
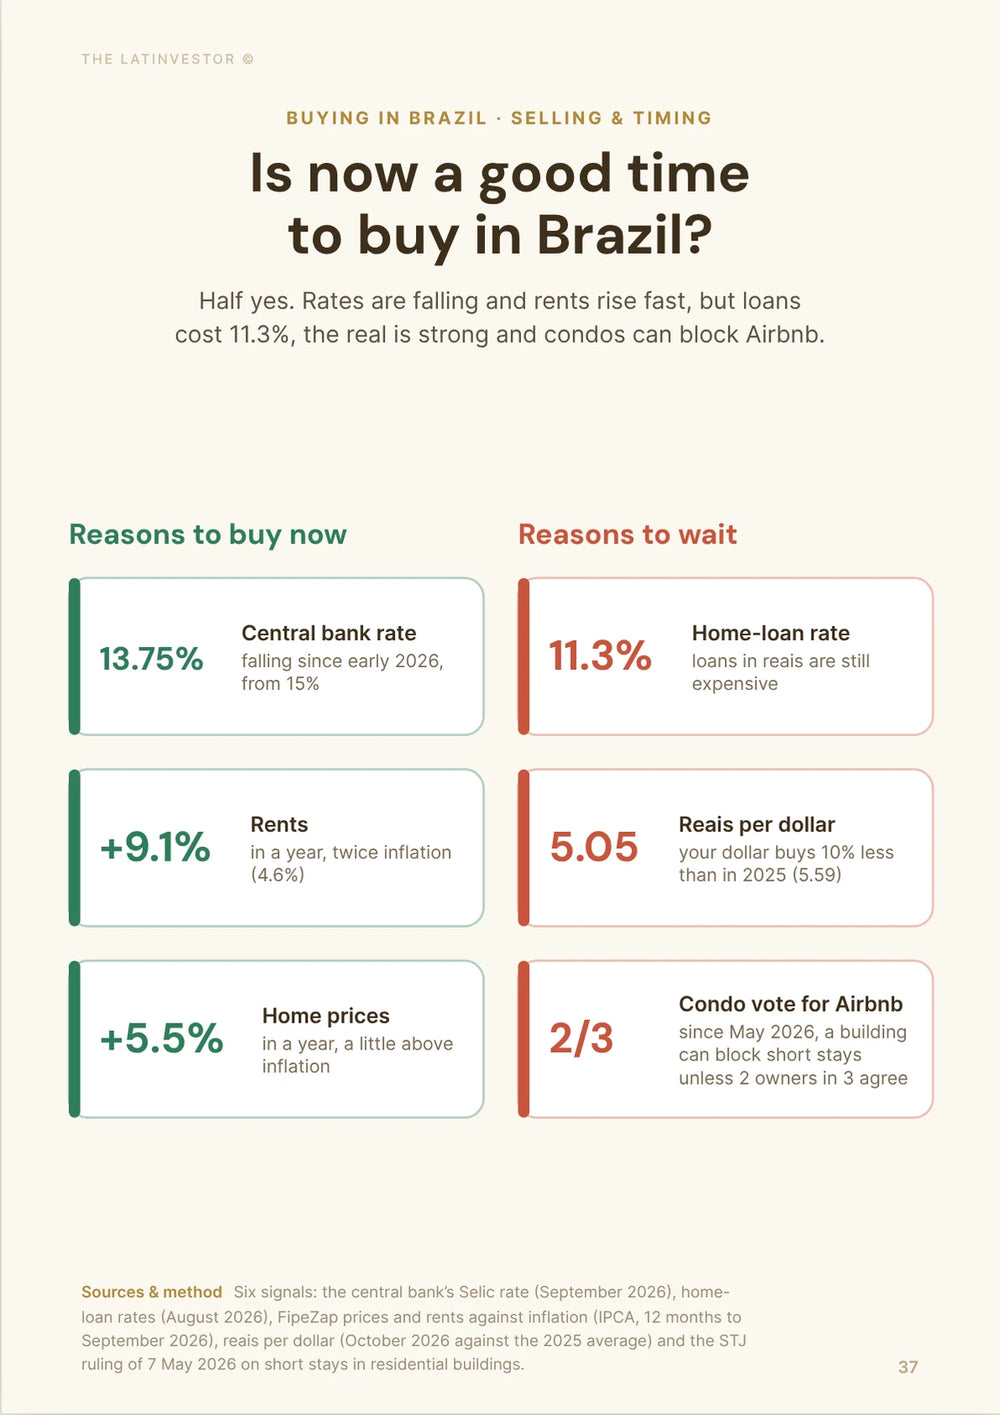
The Selic was cut to 13.75% in September 2026. The Focus survey expects 13.25% at the end of 2026, 12% at the end of 2027 and 10.50% at the end of 2028, which would help borrowers slowly, not overnight.
For a cash buyer, now is a decent time to negotiate: unsold new stock was 8.2% higher in June than a year earlier, and buyers who got a discount report 14% off on average.
Over 5 years, our base case is 20% to 30% higher in nominal terms, about 4% to 5.5% a year. Over 10 years, it's 50% to 70%, and inflation alone would explain most of it.
Bottom line: in Brazil, price growth mostly keeps pace with inflation. Pick the city and the unit carefully, buy below asking, and count on rent for most of the return.


How fast are prices rising in Brazil right now?
Slowly in real terms. Prices go up every year in reais, but in September 2026 the national index was only 0.89% ahead of inflation, and some big cities fell behind it.
Brazil isn't one market. A 1-bedroom in Fortaleza, a family apartment in São Paulo and a beach condo in Santa Catarina don't move for the same reasons, and in 2026 they didn't move at the same speed.
How much does a home cost?
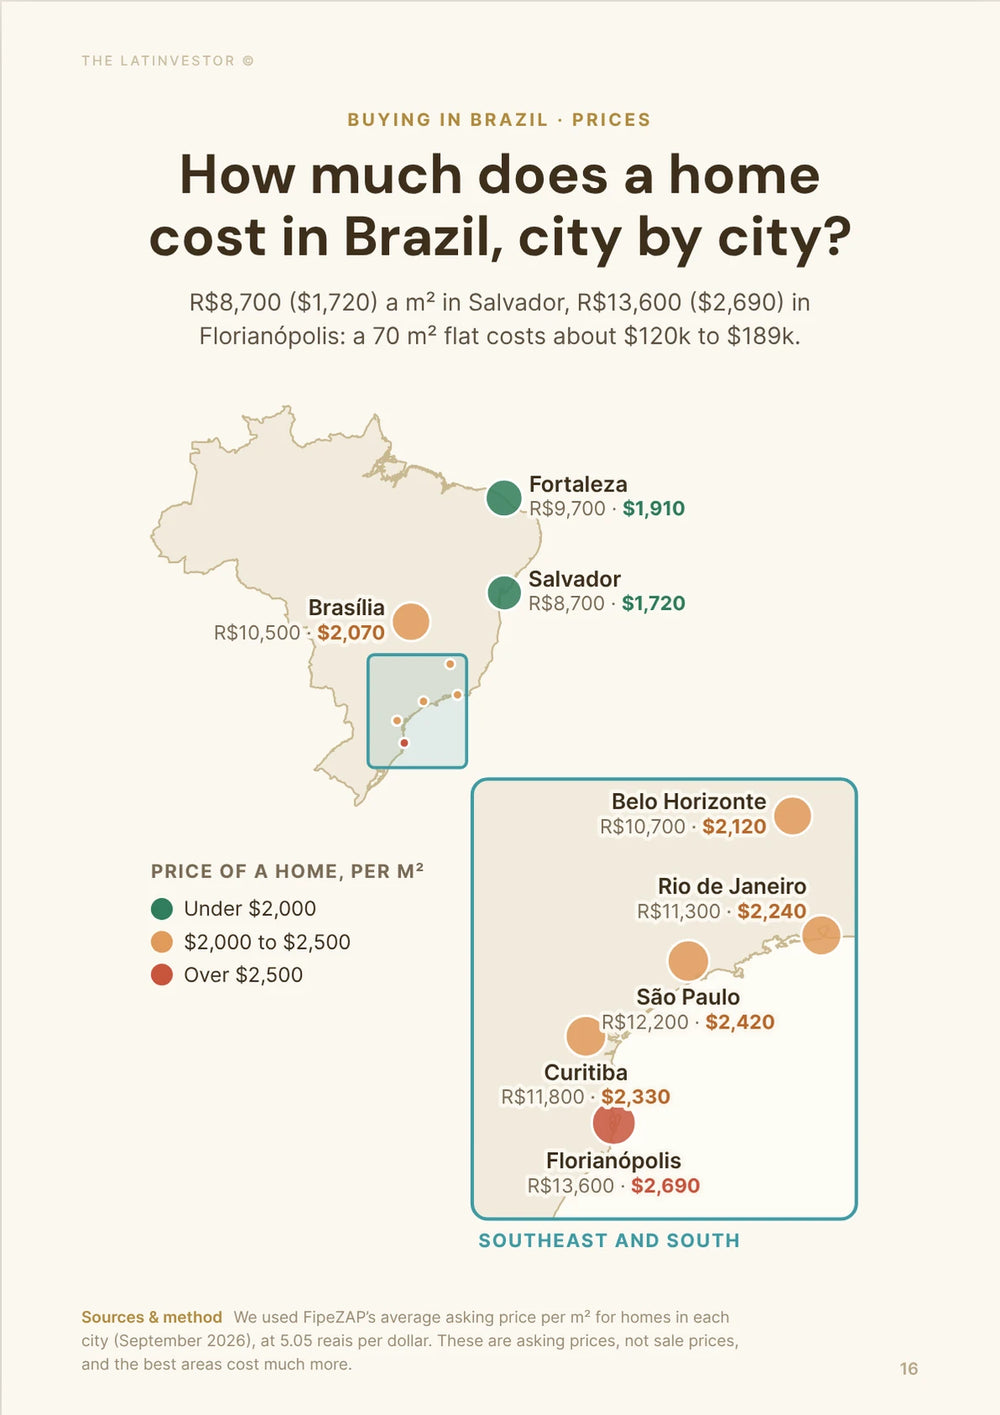
The national FipeZAP asking price was BRL 10,015 per square meter in September 2026, about USD 1,980 or EUR 1,770.
That puts a typical 70 square meter apartment at around BRL 700,000 (about USD 139,000 or EUR 124,000) at asking price. A 2-bedroom is listed a bit lower per square meter, at BRL 8,989 on average.
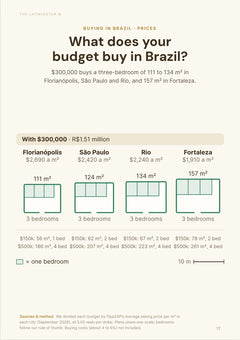
Prices vary a lot by city: about BRL 8,691 per square meter in Salvador, BRL 11,302 in Rio de Janeiro, BRL 12,206 in São Paulo and BRL 13,607 in Florianópolis. These are asking prices; in FipeZAP's Q2 2026 buyer survey, the average discount was 9%.
How much have property prices increased in Brazil over the past 12 months?
By 5.51% in the year to September 2026, and by 4.04% since January. With IPCA inflation at 4.58% over the same 12 months, the real gain was 0.89%.
By size, 1-bedroom apartments rose 7.48%, 2-bedrooms 5.40%, 3-bedrooms 3.87% and 4-bedrooms or more 5.19%.
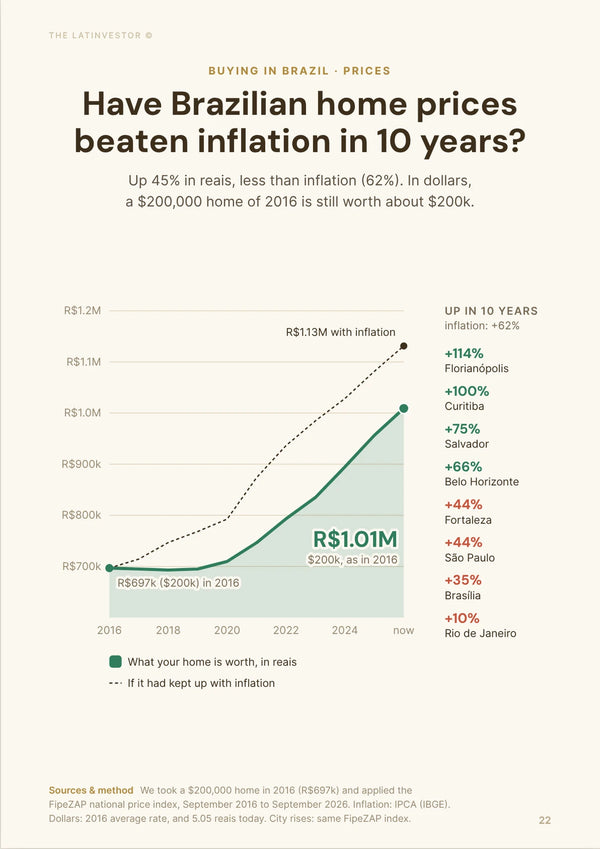
By city, the spread is wide: Vila Velha +14.76%, Vitória +11.93%, Salvador +10.38%, Fortaleza +10.2%, Brasília +9.8% and Florianópolis +8.31%, against Rio +5.57%, São Paulo +3.64%, Belo Horizonte +1.97%, Curitiba +1.86% and Porto Alegre +0.85%.
Which neighborhoods have the fastest rising property prices?
The fastest risers in FipeZAP's September 2026 data are in Salvador and Fortaleza: Barra in Salvador (+15.0%), Ondina (+13.9%) and Graça (+13.8%), plus Aldeota (+13.0%) and Praia do Futuro II (+21.7%) in Fortaleza.
Prime beach districts are moving too: Leblon rose 13.2%, Ipanema 10.3% and Copacabana 9.9% in Rio, and Agronômica 12.4% in Florianópolis. Meireles in Fortaleza, often named as the hot spot, rose a more modest 7.4%.
The pattern is the same everywhere: scarce, walkable addresses near the beach, with restaurants, security and rental demand. A neighborhood figure is based on fewer listings than a city figure, so treat a 20% jump as a sign of interest, not a guarantee.
Which property types are increasing faster in value?
Small apartments. The 1-bedroom is the top performer, with 7.48% growth in the year to September 2026, against 5.40% for 2-bedrooms and 3.87% for 3-bedrooms.
The reason is affordability. With mortgages at 8% to 12% a year, more buyers and tenants settle for smaller units, and investors like them because they rent easily near jobs, beaches and universities.
Large older apartments with high condo fees are the laggards, because buyers now look at the total monthly cost, not just the price.
What is driving property prices up or down?
Up: building costs, rents and demand for small units. Down: expensive credit and rising unsold stock.
Rents rose 9.13% in the year to September 2026 on FipeZAP, faster than prices, which keeps investors interested. Savings-funded mortgage lending also jumped 37.5% from January to August, to BRL 132.5 billion.
The brake is the cost of money. With the Selic at 13.75%, many families can't qualify for the apartment they want, and developers had 355,290 unsold new units at the end of June 2026, 8.2% more than a year earlier.
 Brazil Property Market
This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
Are home prices keeping up with inflation and building costs?
Barely with inflation, and not with building costs. In the year to September 2026, asking prices rose 5.51%, IPCA inflation 4.58% and the INCC construction cost index 6.66%.
That squeeze shows up in two places. Developers pass higher costs on to new launches, so new builds get pricier than resale homes in the same area. And if you buy off-plan, the balance you owe is usually indexed to the INCC until you get the keys, so a 6.66% cost increase lands on your bill, not the developer's.
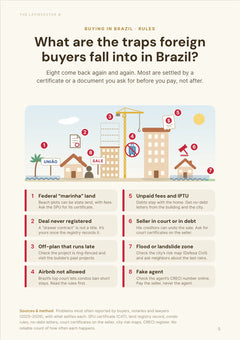
What to do: compare the price per square meter of a launch with resale units nearby, ask for the payment schedule with INCC indexation spelled out, and check whether the project has patrimônio de afetação. Under Lei 13.786/2018, walking away can cost you up to 25% of what you paid, or up to 50% when the project has it.
In some cities, prices are already losing ground in real terms: Curitiba (+1.86%) and Belo Horizonte (+1.97%) rose less than inflation over the last 12 months. A seller there who refuses to negotiate is betting on a market that isn't moving.
What is the property price forecast for Brazil in 2026 and 2027?
Positive in reais, close to flat after inflation. Nobody serious is forecasting a boom or a crash.
Prices were already up 4.04% between January and September 2026, so the calendar year should end at about 5% to 5.5% if the last quarter follows the same pace.
How much are property prices expected to increase in Brazil over the next 12 months?
Our base case is 4% to 6% in nominal terms over the next 12 months. With the Focus survey expecting 4.30% inflation in 2027, that's between a small real loss and a 1.5% real gain.
The two available forecasts sit on either side. Buyers surveyed by FipeZAP in April 2026 expected only 2.5% growth over 12 months, while Hasta's model based on FipeZAP data projects 5.42% to September 2027, to about BRL 10,558 per square meter (about USD 2,090).
The main assumptions: the Selic keeps falling slowly, inflation stays around 4% to 5%, and there's no credit shock.
| City | Asking price (BRL/m², Sept 2026) | Last 12 months | Hasta model, next 12 months |
|---|---|---|---|
| Fortaleza | 9,660 | +10.2% | +8.52% |
| Salvador | 8,691 | +10.38% | +7.43% |
| Florianópolis | 13,607 | +8.31% | +7.17% |
| Rio de Janeiro | 11,302 | +5.57% | +6.48% |
| Brasília | 10,453 | +9.8% | +3.76% |
| São Paulo | 12,206 | +3.64% | +3.69% |
| Curitiba | 11,766 | +1.86% | +1.39% |
| Belo Horizonte | 10,686 | +1.97% | +1.08% |
| Brazil (FipeZAP index) | 10,015 | +5.51% | +5.42% |
Which neighborhoods will see the highest price growth in Brazil in the next 12 months?
Most likely the same beach districts that led in 2026: Aldeota and Meireles in Fortaleza, Barra, Ondina and Rio Vermelho in Salvador, Praia do Canto in Vitória, and Tambaú and Cabo Branco in João Pessoa.
Their cities have the strongest momentum, and the Hasta model gives Fortaleza 8.52% and Salvador 7.43% for the next 12 months. In the best streets, our estimate is 7% to 12%.
The catalyst is the same everywhere: few good homes in walkable coastal neighborhoods, with strong local and tourist demand. One to watch is Campeche in Florianópolis, where beach demand and newer buildings meet.
What property types will appreciate the most in Brazil in the next 12 months?
Studios and 1-bedroom apartments in good rental locations, as in 2026. Our estimate is 6% to 8% for them, a bit more in strong coastal districts.
Small units keep two advantages: they're the easiest homes to finance at current rates, and they rent fast. FipeZAP's gross yield is 6.74% for 1-bedrooms, against 6.13% for all sizes.
The type most likely to lag is the large older apartment with high condo fees. If you're buying one, use that to negotiate.
How will interest rates affect property prices in Brazil?
Rates are the main brake, and it's loosening slowly. The Copom cut the Selic from 14% to 13.75% in September 2026, and the next meeting is on 3 and 4 November.
In the Focus survey of 19 October 2026, economists expected the Selic at 13.25% at the end of 2026, 12% at the end of 2027 and 10.50% at the end of 2028. Mortgage rates should follow with a lag: in September 2026, regulated housing loans cost about 7.98% a year plus TR at Caixa, and 11.77% to 11.87% at Bradesco, Santander and Itaú.
One point matters. By our calculation, on a BRL 500,000 30-year loan with decreasing payments (SAC), going from 11.87% to 10.87% cuts the first monthly payment by about BRL 380 (about USD 75), before TR and insurance. That's what pushes buyers back into the market, and why lower rates would mostly lift mid-size family apartments.
What are the biggest risks for property prices?
Rates staying high for longer, unsold stock building up and the real. Of the three, high rates are the most likely.
The Focus survey has already moved its Selic forecasts up and down several times in 2026. If cuts stall, mortgage demand stays weak and sellers of large apartments in São Paulo, Rio, Brasília and Belo Horizonte will have to negotiate more.
Supply is the second warning sign: 355,290 unsold new units in June 2026, 8.2% more than a year earlier. For a foreign buyer, add currency risk: a 10% move in the real can cancel a year of price growth when you convert back to dollars or euros.
Is it a good time to buy a rental property?
Yes, if you buy a liquid, well-located small apartment below asking. No, if you're paying for prestige and counting on price growth.
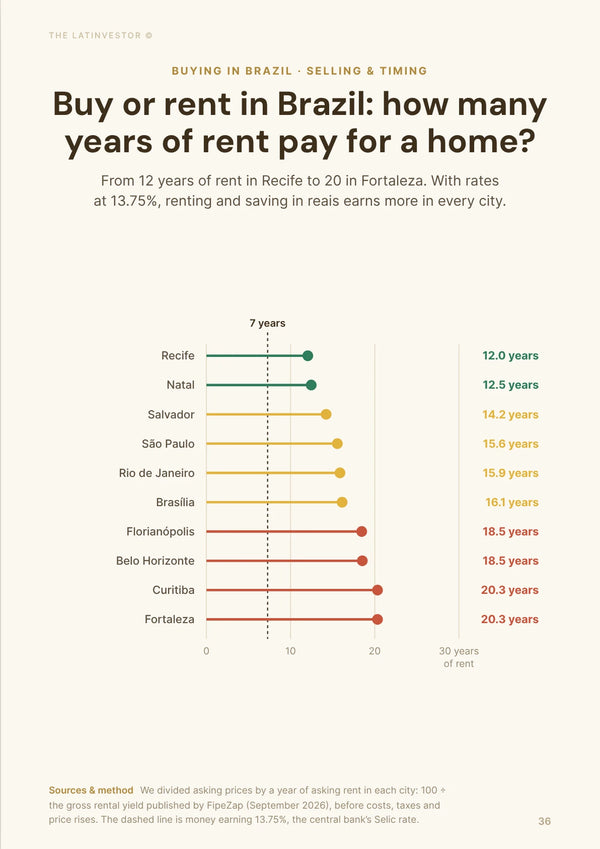
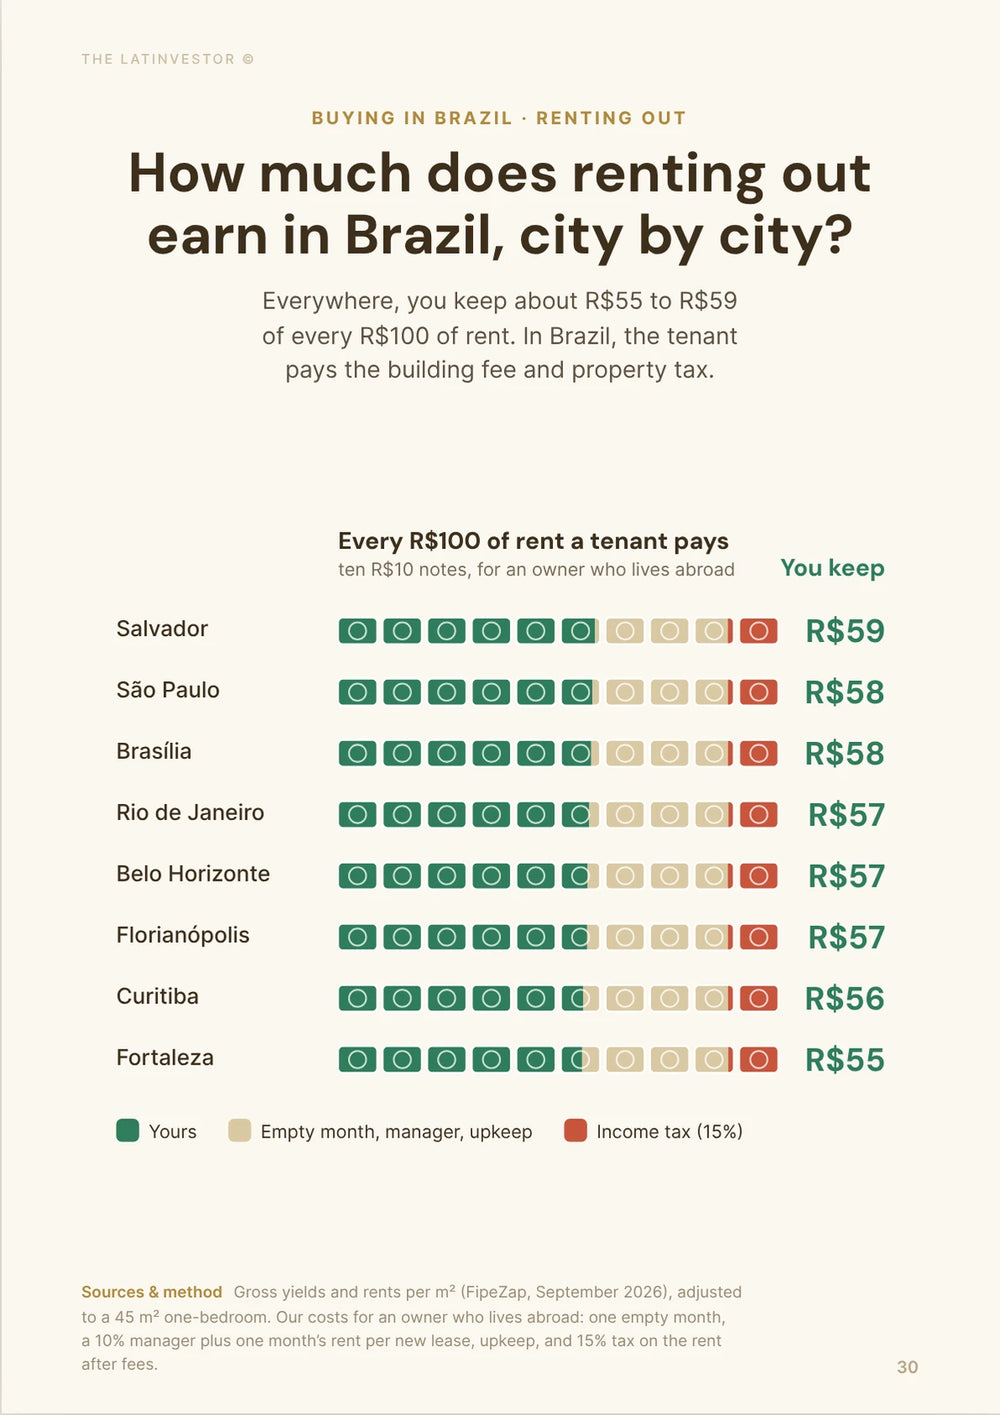
The case for buying: rents rose 9.13% in a year, and the FipeZAP gross yield is 6.13%. If you live abroad, 15% of the gross rent is withheld as tax, which takes that to about 5.2% before condo fees, IPTU, vacancy and management.
The case for waiting: if rates fall as expected, more local buyers come back in 2027 and 2028, but so does competition. Today's cash buyer faces fewer rivals.
 70+pages
Should you buy now or wait for lower rates in Brazil?
If you pay cash, buying now is usually better than waiting. You negotiate against sellers who have few buyers with mortgages, and that advantage shrinks as rates fall.
The numbers support it. In FipeZAP's Q2 2026 survey, the average discount was 9%, and 14% when the buyer got one. Unsold new stock was 8.2% higher than a year earlier, and mid- and high-end developers are carrying inventory they want to move.
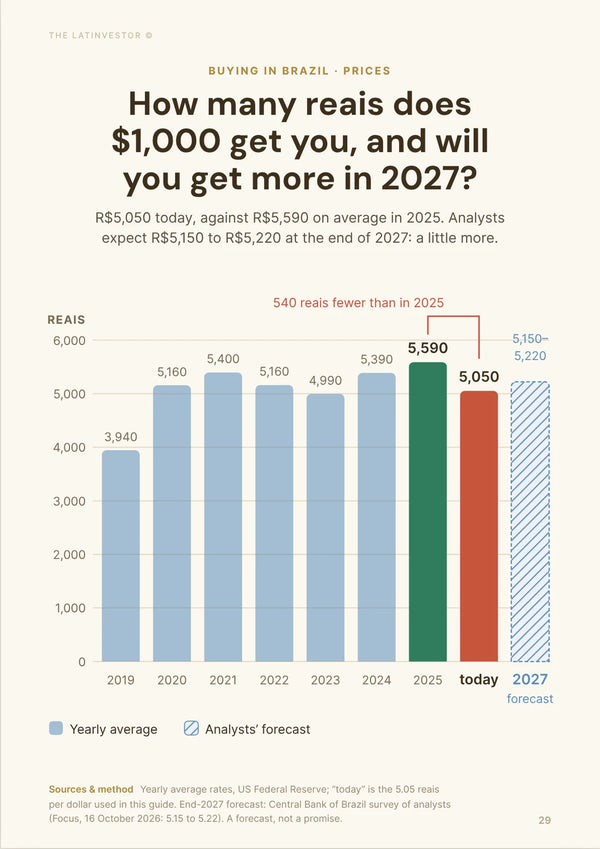
If you need a Brazilian mortgage, waiting can make sense: the Focus survey sees the Selic falling from 13.75% today to 12% by the end of 2027. But if you live abroad, rate cuts won't change much for you, because banks rarely lend to non-residents anyway.
What to do now: open at 15% below asking on resale units that have been listed for a while, ask developers for discounts or better payment terms on finished unsold units, and don't overpay today for a rate cut that hasn't happened yet.
Where will property prices be in 5 years in Brazil?
Higher in reais, but much of that will be inflation. The winners will be specific cities and streets, not the country as a whole.
Recent history shows how uneven it is: Florianópolis rose about 64% and Curitiba about 62% in five years, according to a calculation based on FipeZAP data, yet Curitiba has nearly stalled in the last 12 months.
What is the 5-year property price forecast for Brazil?
Our base case is 20% to 30% higher in nominal terms by 2031, about 4% to 5.5% a year. That would take the national average from BRL 10,015 to roughly BRL 12,000 to 13,000 per square meter (about USD 2,380 to 2,570).
A conservative case is around 12% over five years, a real loss if inflation stays near 4%. An optimistic case is about 40%, if the Selic really reaches 10.50% by 2028 and credit opens up.
The key assumption is that Brazil gets to lower rates without losing control of inflation. With the Focus survey at 3.80% inflation for 2028, most of the base case is simply inflation.
Which areas in Brazil will have the best price growth over the next 5 years?
Our picks are Greater Vitória in Espírito Santo, the beach districts of Fortaleza, Salvador and João Pessoa, and coastal Santa Catarina.
In the best neighborhoods there, our estimate is 35% to 50% over five years, against 20% to 30% for the country. The 5-year view gives more weight to migration, tourism and scarcity than to last year's numbers alone.
The area to watch is Vila Velha, next to Vitória, especially Praia da Costa and Itapuã: its prices jumped 14.76% in a year but, at BRL 11,533 per square meter, it's still well below Vitória at BRL 15,905.
What property type will give the best return in Brazil over 5 years?
Small apartments in strong rental locations. Combining price growth and rent, our estimate is a 45% to 55% total return over five years before costs, using 20% to 30% price growth and a net yield of about 5% a year after the 15% non-resident tax.
The trend behind it: smaller households, more renting, and demand for practical homes near jobs, beaches, universities and transit.
The best balance of return and risk is a 1- or 2-bedroom in a safe, well-connected neighborhood, not a trophy house that takes a year to sell.
How will new infrastructure projects affect property prices in Brazil over 5 years?
Mostly through metro, BRT and bus corridors, plus sanitation upgrades under Novo PAC.
Based on our listing checks, homes near finished, useful transport often carry a premium of about 5% to 15%. The premium is much weaker when a project is late or far from daily needs.
The likely winners are station and corridor areas in São Paulo (Metro Line 6), Belo Horizonte (Metro Line 2), Salvador, Fortaleza, Recife and Curitiba, plus Rio's port district. Pay for what's built, not what's announced.
How will population growth and other factors impact property values in Brazil in 5 years?
Only a little at the national level, because Brazil's population is growing slowly.
The bigger shift is smaller households: more single people, couples without children and older people living alone, which supports demand for compact apartments.
Moves within Brazil matter more than foreign buyers, with lifestyle and job moves supporting Florianópolis, João Pessoa, Fortaleza, Vitória, São Paulo and parts of Rio de Janeiro.
 70+pages
What is the 10-year property price outlook in Brazil?
Positive in reais, uncertain in real terms. It depends on inflation, credit and, above all, location.
A scarce apartment in a top district and an old house far from jobs won't follow the same path over ten years.
What is the 10-year property price prediction for Brazil?
Our base case is 50% to 70% higher in nominal terms by 2036, about 4% to 5.5% a year. Keep in mind that 4% inflation a year adds up to 48% over ten years on its own.
A conservative case is around 25%, a clear real loss. An optimistic case is close to 95%, for the best-located homes if credit gets deeper and cheaper.
The biggest unknown is Brazil's real interest rate. With the Selic at 13.75% and inflation around 4.5%, borrowing costs about 9 points above inflation, and that holds prices back even when jobs and rents are strong.
What long-term economic factors will shape property prices?
Mortgage availability, household income and building costs.
The best thing that could happen is cheaper, wider housing credit, which would let more middle-class buyers move up to better apartments and areas.
The biggest structural risk is fiscal and inflation trouble, which keeps rates high and makes 30-year mortgages hard for families to carry.
Our methodology
This article estimates where residential prices in Brazil are heading: the last 12 months, the next 12 months, and 5- and 10-year scenarios, by city, neighborhood and property type.
Current prices and past growth come from the FipeZAP sale index for September 2026, compared with IBGE's IPCA inflation and the FGV INCC construction cost index. Forecasts combine the FipeZAP Raio-X buyer survey, Hasta's FipeZAP-based model and the Banco Central's Focus survey for inflation and the Selic. The 5- and 10-year ranges are our own scenarios, built on those figures.
Interest rates and mortgage rates come from the Banco Central do Brasil, mortgage volumes from ABECIP, new-build supply from CBIC and ABRAINC-Fipe, and the rules on off-plan cancellations from Lei 13.786/2018. The 15% tax on non-residents' rent comes from Receita Federal.
We checked these figures in October 2026. Conversions use about 5.05 reais per US dollar and 5.65 reais per euro.
FipeZAP measures asking prices of ready apartments, not deed prices or houses, and buyers report average discounts of 9% to 14%. Neighborhood figures rest on fewer listings than city figures, and forecasts are scenarios, not promises.
Key sources used for this analysis include FipeZAP sale index (September 2026), FipeZAP rent index (September 2026), FipeZAP Raio-X, FipeZAP discount survey via Portas, Hasta, IBGE IPCA, INCC (FGV) via Partnr, Banco Central do Brasil (Selic), Banco Central do Brasil (mortgage rates), Focus survey of 19 October 2026 via SBT News, ABECIP, CBIC, ABRAINC-Fipe, Ceni & Southier 5-year FipeZAP calculation, Lei 13.786/2018, Novo PAC and IBGE.