

Summary
Probably yes, but slowly. Our base case is a 3% to 6% rise in US dollar prices over the next 12 months, close to the 6.3% that official promoted-housing prices gained in the year to April 2026 (ANV). No institution publishes a price forecast for Uruguay, so this is our estimate.
Most of that rise is the dollar, not a boom. Measured in UI, the inflation-linked unit, the same prices fell 1.3%, so in real terms they are roughly flat. Inflation was 4.68% over the 12 months to September 2026.
Prices are already high for the region: a 2-bedroom apartment lists at a median of USD 260,000 and apartments at USD 3,436/m² nationwide (TuLugar, October 2026). The median registered deed was USD 90,000 in July 2026 (INE), but that mixes every type of property.
Maldonado, Punta del Este's department, rose fastest in dollars (+9.3%), ahead of Montevideo (+5.1%). In UI, Maldonado was flat and Montevideo fell 2.2%.
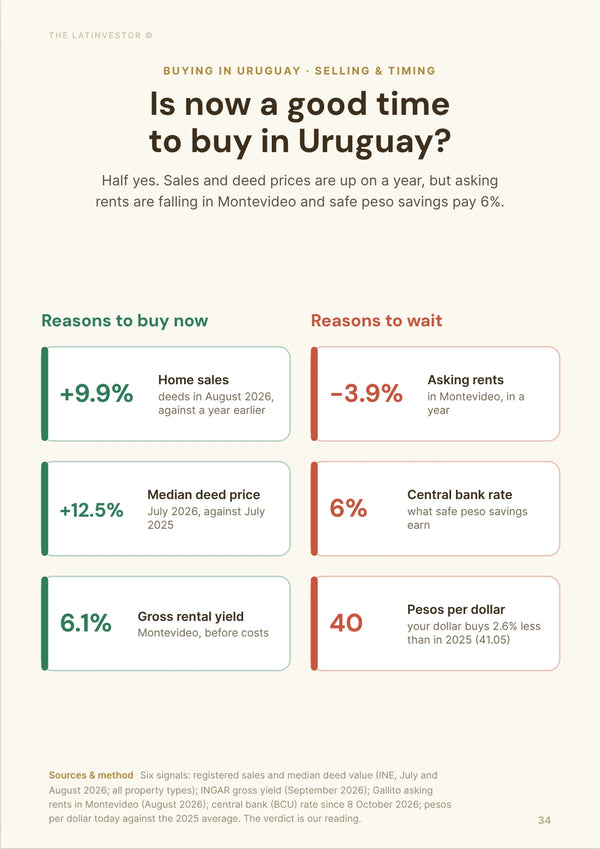
The market is active: INE registered 4,838 sales in August 2026, 9.85% more than a year earlier, and bank housing credit was up 8.8% in March 2026 (BCU).
For the next 12 months, the best bets are small, well-located apartments in Montevideo (Cordón, Tres Cruces, La Blanqueada, Buceo) and prime coastal flats. In Punta del Este we expect 1% to 4% for normal apartments and 3% to 6% for prime ones; big older houses will do less.
Rates went up, not down: the central bank raised its policy rate from 5.75% to 6.00% on 8 October 2026. One extra point on a 25-year loan cuts what a buyer can borrow by about 9%, but most foreign buyers pay cash.
The main risks are weaker Argentine demand (Argentines are 50% to 55% of buyers in Maldonado's resort market), a soft summer and tighter credit. A bad year could mean a 3% to 7% national drop in dollars (our estimate).
Don't wait for a cheaper peso: the BCU survey expects 40.5 pesos per dollar at the end of 2026 and 41.4 at the end of 2027, about 3% weaker. Property is priced in dollars, so that doesn't cut the price.
Over 5 years, Montevideo promoted-housing prices rose 26.7% in dollars (first half of 2021 to January-April 2026), about 4.8% a year. We expect 3% to 5% a year from here, or about 16% to 28% over five years.
Over 10 years, the long view is calmer: since 2017 the same series is up about 31% in dollars (3.1% a year) and only 1% in UI. Our 10-year range is 3% to 4.5% a year, about 34% to 55% in dollars, roughly flat to slightly up in real terms.
Our advice: buy for use or for rent, not for a quick gain. Buying and selling costs eat about 13% to 15% of the price, so plan to hold at least 5 years, and offer around 10% below asking on anything that has sat on the market.


How fast are property prices rising in Uruguay right now?
Slowly, and mostly in dollars. The only official price series, the ANV report on promoted new-build flats, shows +6.3% in US dollars over the 12 months to April 2026, but −1.3% in UI, the inflation-linked unit.
Almost everything is priced in US dollars, while most local salaries are paid in pesos. That makes Uruguay feel stable for foreign buyers, but expensive for local households, which caps how fast prices can climb in the middle of the market.
What is the average house price?
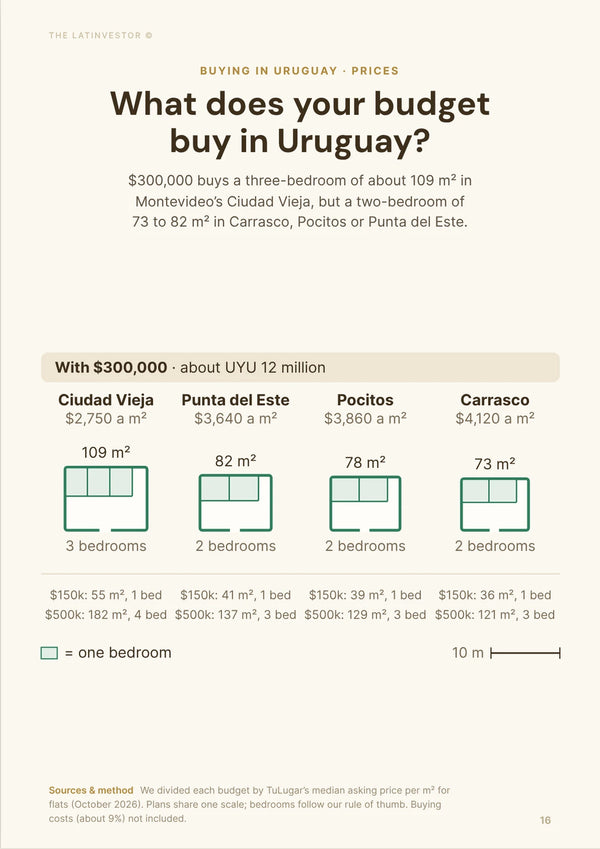
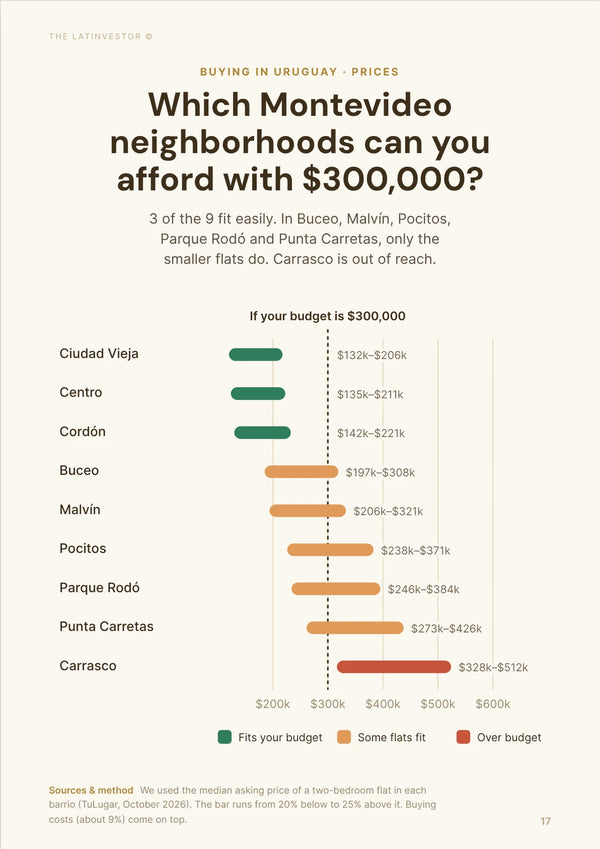
Nobody publishes an official average, and an average would be pulled up by a few Carrasco houses and Punta del Este villas anyway. Medians tell you more. In October 2026, a 1-bedroom apartment listed at a median of about USD 158,000 (about UYU 6.34 million, EUR 141,000), a 2-bedroom at USD 260,000 (about UYU 10.4 million, EUR 232,000) and a 3-bedroom house at USD 345,000 (about UYU 13.8 million, EUR 307,000) (TuLugar).
Per m², apartments list at a median of USD 3,436 (about UYU 138,000, EUR 3,060) and houses at USD 2,177 (about UYU 87,300, EUR 1,940). The official median of all registered deeds is much lower, USD 90,000 (about UYU 3.61 million, EUR 80,200) in July 2026, because it includes land, garages and homes in interior towns.
By our estimate, about 80% of normal homes in Uruguay sell between USD 80,000 and USD 800,000 (about UYU 3.21 million to 32.1 million, EUR 71,300 to 713,000).
How much have property prices increased in Uruguay over the past 12 months?
About 6% in dollars. Promoted new-build flats sold at an average of USD 2,450 per built m² over the 12 months to April 2026, up 6.3% in US dollars on a year earlier (ANV). Montevideo rose 5.1% and Maldonado 9.3%.
In UI, the national figure fell 1.3%, Montevideo fell 2.2% and Maldonado was flat. So the dollar gains mostly track peso inflation (4.68% over 12 months in September 2026, INE): prices are holding their real value, not racing ahead.
| Area | Average price, promoted housing | 12-month change in USD | 12-month change in UI |
|---|---|---|---|
| Uruguay | USD 2,450/m² built | +6.3% | −1.3% |
| Montevideo | USD 2,411/m² built | +5.1% | −2.2% |
| Maldonado (incl. Punta del Este) | USD 2,173/m² built | +9.3% | Roughly flat |
INE's median deed rose faster, 12.5% between July 2025 and July 2026, but it moves with the mix of what sells, so read it as a sign of an active market, not as a price index. Uruguay has no official house price index.
Which neighborhoods have the fastest rising property prices?
There's no official price series by neighborhood, so nobody can rank them precisely. The clearest signals point to central Montevideo barrios such as Cordón, La Blanqueada and Aguada, where new projects, students and young renters keep demand up. We estimate they gained roughly 10% to 15% in dollars over the last three years.
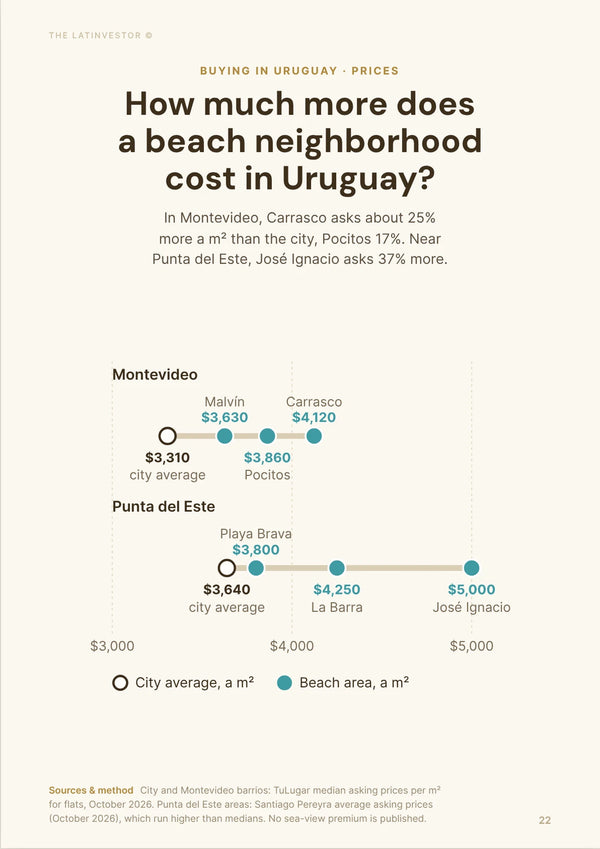
They still have room: Cordón asks USD 3,228/m², 18% less than Pocitos (USD 3,956/m²) and 26% less than Carrasco (USD 4,370/m²) (INGAR, September 2026).
On the coast, Maldonado as a whole rose 9.3% in dollars (ANV), and Playa Brava apartments list at about USD 3,800/m² (Santiago Pereyra, October 2026). There is no reliable growth figure for Playa Brava itself.
Which property types are increasing faster in value?
The only type with measured prices is the new promoted apartment, up 6.3% in dollars in a year. For the rest, we rely on asking prices and how fast things sell.
Our ranking: well-located apartments in Montevideo first, because they are the easiest to rent and resell; prime coastal apartments in Punta del Este second; family houses third. Houses list much cheaper per m² (USD 2,177 against USD 3,436 for apartments) and sell more slowly.
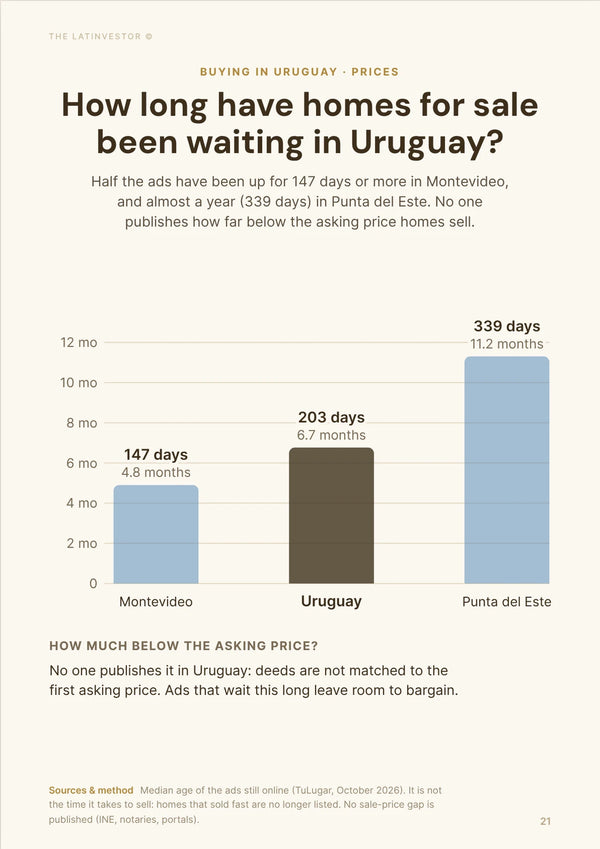
Coastal villas in La Barra, Manantiales and José Ignacio are the most expensive per m², but there is no data showing they gain faster, and they often take nine months or more to sell (our estimate). Scarce beachfront homes hold value; generic big villas don't.
What is driving property prices up or down?
Three things: foreign demand for a stable dollar asset, limited supply in the best urban and coastal spots, and how much local buyers can borrow.
Foreign and cash-rich buyers push hardest. Argentines alone make up 50% to 55% of buyers in Maldonado's resort market (broker estimate, June 2026), so the coast moves with Argentina's economy.
New supply pulls the other way: the vivienda promovida scheme has recorded 26,242 sales since it began, and declared sales were up 12.7% in January to April 2026 (ANV). Credit helps at the margin: bank housing loans were 8.8% higher in March 2026 than a year earlier (BCU).
 Uruguay Property Market

This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
What is the property price forecast for Uruguay over the next 12 months?
Positive but modest. With 2026 almost over, the useful question is the next 12 months: we expect dollar prices to keep rising slowly, while local incomes limit how far the middle of the market can go.
How much could property prices rise in Uruguay over the next 12 months?
Our base case is +3% to +6% in US dollars nationally, close to the 6.3% ANV measured over the last year. In real terms, that is about flat: inflation runs at 4.68% and the BCU's October 2026 survey expects the peso to drift from 40.1 to 40.5 per dollar by the end of 2026 and 41.4 by the end of 2027.
No institution publishes a price forecast for Uruguay, so treat every figure below as our estimate, not a promise.
| Horizon | Our estimate, in US dollars | What it rests on |
|---|---|---|
| Next 12 months, Uruguay | +3% to +6% | ANV +6.3% in the year to April 2026, inflation 4.68% |
| Next 12 months, Montevideo | +3% to +6% | ANV Montevideo +5.1% |
| Next 12 months, Punta del Este | +1% to +4% (normal flats), +3% to +6% (prime) | ANV Maldonado +9.3% in USD, flat in UI; long listing times |
| Bad year (weak Argentine demand, soft summer, tighter credit) | −3% to −7% nationally | Past slowdowns since 2002 |
| Next 5 years | +3% to +5% a year, about +16% to +28% | Montevideo +4.8% a year in 2021-2026 (ANV) |
| Next 10 years | +3% to +4.5% a year, about +34% to +55% | Montevideo +3.1% a year in 2017-2026 (ANV) |
Which neighborhoods will see the highest price growth in Uruguay over the next year?
Nobody publishes a credible forecast by neighborhood, so we don't give one. Our best bets in Montevideo are Cordón, Tres Cruces, La Blanqueada, Ciudad Vieja and the Buceo waterfront: cheaper than Pocitos, close to services and easy to rent.
On the coast, we'd look at year-round areas rather than summer-only ones: in Punta del Este, Manantiales for new luxury projects and Roosevelt and Aidy Grill, where more people now live all year; and Ciudad de la Costa for commuters to Montevideo.
One area that could surprise is Pinares in Punta del Este: apartments list at about USD 3,400/m², about 10% less than Playa Brava (USD 3,800/m²), while it still benefits from the wider Maldonado demand (Santiago Pereyra, October 2026).
What property types will appreciate the most in Uruguay over the next year?
Small and mid-sized apartments in liquid areas: we expect them to track or slightly beat the national +3% to +6%. Prime coastal apartments in Punta del Este should do about +3% to +6%, normal ones +1% to +4% (our estimates).
The demand is clear: smaller households, renters near universities and hospitals, and Argentines or Brazilians who want a second base that also works outside January.
The type most likely to lag is the big older house that needs work, inland or on the coast: flat to slightly up in dollars at best, because renovation costs scare buyers and few locals can finance it.
How will interest rates affect property prices in Uruguay over the next year?
They will cap the upside for local buyers, not stop it. The central bank raised its policy rate by 0.25 points, from 5.75% to 6.00%, on 8 October 2026, with inflation at 4.68%, inside its 3% to 6% target range.
Mortgages are not cheap for foreigners: Santander charges non-residents 6.75% in dollars for a main home and 6.95% for an investment (tariff of 7 August 2026). On a 25-year loan, each extra point of interest cuts what you can borrow for the same payment by about 9%.
The price effect is smaller than it sounds, because most foreign buyers in Montevideo and Punta del Este pay cash. If you borrow, compare a UI loan with a dollar loan over five years, not only on the first payment.
What are the biggest risks for property prices in Uruguay over the next year?
Weaker demand from Argentina or Brazil, local affordability, and too many similar small new apartments in some Montevideo promoted-housing corridors.
The most likely is affordability: prices are in dollars, salaries in pesos. The most damaging would be all three at once, plus a soft summer: in that case we'd expect a 3% to 7% national drop in dollars, and 8% to 15% for older coastal homes (our estimate).
One practical change: Decree 238/026, published in October 2026, caps the cash part of a property payment at UI 200,000 (about USD 33,000). Closing in dollar bills, common on the coast, is over, so plan a bank transfer and proof of funds early.
Is it a good time to buy a rental property in Uruguay?
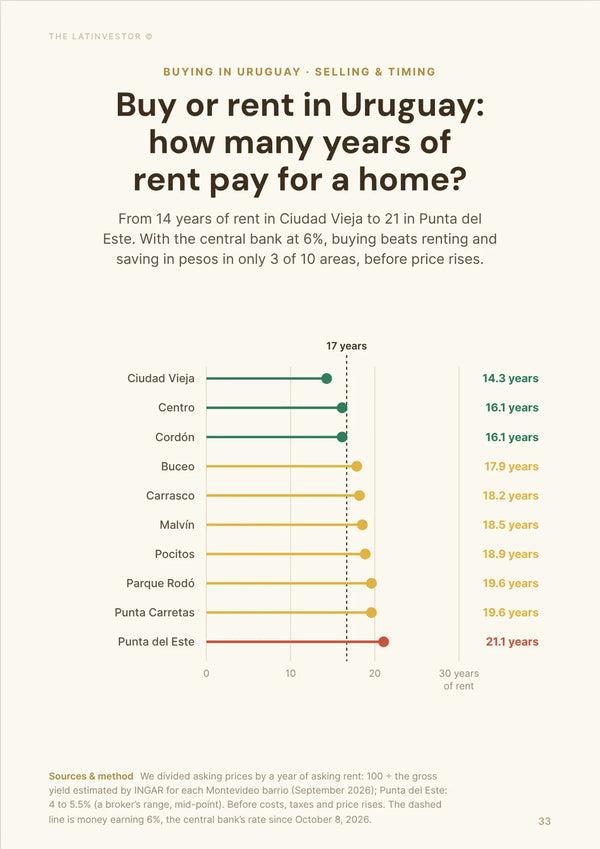
Yes, if you stay picky: a 1- or 2-bedroom apartment in a year-round area, bought at a fair price. Montevideo's median gross yield is 6.1% (INGAR, September 2026), or about 4% net after costs and the 10.5% rental tax advance (IRPF or IRNR).
The case for waiting: asking rents in Montevideo fell 3.9% over the year to August 2026 (El País / Inmuebles Data), and many listings are still priced too high, especially older flats with heavy gastos comunes (building fees).
On the coast, long leases in Punta del Este yield about 2.5% to 3.6% net after tax (4% to 5.5% gross, Caetano), so a coastal flat bought only for rent rarely pays.
 70+pages
Will a weaker peso make Uruguay property cheaper in 2027?
Not really. The peso has held between 40.1 and 40.3 per US dollar since August 2026, after a 2026 range of 37.4 (27 January) to 40.8 (24 March).
Forecasters see only a small slide. The BCU's October 2026 survey expects 40.5 pesos per dollar at the end of 2026 and 41.4 at the end of 2027; Itaú (September 2026) says 40.5 and 41.0, and BBVA Research (June 2026) 41.0 and 42.9. That's a peso 1% to 7% weaker than today by the end of 2027.
Since homes are priced and paid in dollars, a weaker peso doesn't lower the price. It makes local costs a little cheaper for you (gastos comunes, property tax, renovation labor) but it makes dollar prices harder to reach for locals paid in pesos. If you hold euros, the bigger swing is the euro against the dollar: it has lost about 3% since early September.
Where will property prices be in 5 years in Uruguay?
Higher in dollars, but the gains will come from location and liquidity, not from a national boom.
Two flats in the same city can do very differently if one is easy to rent and resell and the other is old, expensive to run or badly placed.
What is the 5-year property price forecast for Uruguay?
Start with what happened: in Montevideo, promoted new flats went from USD 1,955 per built m² in the first half of 2021 to USD 2,477 in January to April 2026, +26.7% in dollars, or about 4.8% a year (ANV). In UI, they went from 17,448 to 15,073, about 14% lower: the gains were all in dollars, not in real terms.
Our estimate for the next five years is +3% to +5% a year in dollars, or about 16% to 28% in total. A cautious case (2% a year) gives about 10%; a strong one (6% a year) about 34%.
This assumes Uruguay keeps its reputation as a stable, safe market in South America, with inflation inside the 3% to 6% target band. It's an estimate built on one official series, not an institutional forecast.
Which areas in Uruguay will have the best price growth over the next 5 years?
The three areas we'd expect to beat the national range are central Montevideo (Cordón, Tres Cruces, La Blanqueada), the year-round parts of the Maldonado coast (Punta del Este, La Barra, Manantiales) and the Ciudad de la Costa commuter belt (Solymar, Lagomar, El Pinar).
We don't put numbers on single areas: there is no price series by barrio or zone, so any figure would be a guess. The logic is daily life: services, jobs, transport and people who live there all year, not just January.
The cheaper area with the most room is Pinares, about 10% below Playa Brava per m² for apartments, as long as you pick a building that rents outside summer.
What property type will give the best return in Uruguay over 5 years?
A well-located compact apartment in Montevideo: Cordón, Tres Cruces, La Blanqueada, Parque Rodó, Pocitos or Buceo.
Rough math, by our estimate: 16% to 28% price growth plus about 4% a year of net rent (about 20% over five years) gives 36% to 48% before transaction costs. Take off about 13% to 15% for buying with an agency and selling later, and you're at roughly 20% to 35% over five years, before capital gains tax.
That's why a 1- or 2-bedroom in a liquid barrio beats a luxury villa or an inland house on risk: more people can buy it from you later.
How will new infrastructure projects affect property prices in Uruguay over 5 years?
The projects that matter are the Central Railway (Ferrocarril Central) corridor, port and logistics work around Montevideo, Montevideo's bus corridor works planned through 2029, and road improvements in Canelones and Maldonado.
We found no reliable figure tying a specific project to a price jump in Uruguay, so don't pay a premium for a promised project. Prices follow only once daily life actually gets easier: shorter commutes, new jobs, better services.
The places most likely to feel it are Ciudad de la Costa, Solymar, Lagomar, El Pinar, parts of Montevideo near job corridors, and towns along the railway such as Durazno and Florida.
How will population growth and other factors impact property values in Uruguay in 5 years?
Barely at the national level. Uruguay had about 3.4 million people at the 2023 census and grows very slowly, so population alone won't lift prices.
What matters more is how people live: smaller households and an older population want low-maintenance apartments in walkable areas. That supports compact flats in Montevideo.
Moves within the country count too: toward Canelones, Maldonado and Colonia, plus Argentines, Brazilians and retirees looking for a second base. Maldonado had about 213,000 residents at the 2023 census and keeps attracting people.
 70+pages
What is the 10-year property price outlook in Uruguay?
Positive in dollars, calm in real terms. Uruguay is a market for stability, not for fast gains.
The best long-term results should come from scarce coastal spots, liquid Montevideo barrios and commuter towns with services, not from generic inland housing.
What is the 10-year property price prediction for Uruguay?
The longest official series helps here. From the first half of 2017 to January-April 2026, Montevideo promoted flats went from USD 1,884 to USD 2,477 per built m², about +31% in dollars, or 3.1% a year. In UI they rose only about 1% (14,879 to 15,073): over nine years, prices barely beat inflation (ANV).
Our 10-year estimate is +3% to +4.5% a year in dollars, about 34% to 55% in total. A cautious case (2% a year) gives about 22%; a strong one (5% a year) about 63%. In real terms, expect roughly flat to slightly up.
The big unknown is whether local wages, credit and building costs can keep up with dollar prices while foreign buyers stay confident. If they can’t, expect long stalls and slow sales rather than a crash, as in the slowdowns since 2002.
What long-term economic factors will shape property prices?
Political stability, foreign-buyer demand, and the gap between dollar prices and peso wages.
The biggest plus is trust: Uruguay is stable and legally predictable, and buyers from Argentina and Brazil pay for that. The biggest risk is affordability: if dollar prices keep outpacing wages, fewer locals can buy in the prime areas.
Watch three numbers each year: inflation against the 3% to 6% target, the policy rate (6.00% in October 2026), and the ANV price change in UI. If the UI figure stays near zero, prices are only keeping pace with inflation.
Our methodology
This article estimates where property prices in Uruguay are heading: the recent trend, the next 12 months by area and property type, the effect of interest rates, the peso and the 2026-27 summer, and the outlook over 5 and 10 years.
We start with official data: ANV's price report No. 50 on promoted housing (the only official price series, with Montevideo semesters back to 2017), INE for registered sales, deed values and inflation, and the BCU for the policy rate, credit and the October 2026 exchange-rate survey. We then use portals and brokers for asking prices: TuLugar (October 2026), INGAR (September 2026) for Montevideo barrios and Santiago Pereyra (October 2026) for Punta del Este zones.
Rules come from IMPO (Decree 238/026 on cash payments) and the DGI (rental tax), with mortgage rates from Santander's published tariff of 7 August 2026.
We checked these figures in October 2026. Peso amounts are converted at about 40.1 pesos per US dollar and 45 pesos per euro (BCU, October 2026). Property in Uruguay is priced and paid in US dollars, so our forecasts are in dollars; the UI figures show what the same change means after Uruguayan inflation.
Limits: no institution publishes a property price forecast or a national price index for Uruguay. Every forecast here (12 months, 5 and 10 years, scenarios, area picks) is our own estimate, built mainly on the ANV series, which covers promoted new builds only. Portal figures are asking prices, not sale prices.
Key sources used for this analysis include ANV price report No. 50, INE IAI Compraventa (August 2026), INE CPI (September 2026), BCU COPOM, BCU expectations survey (October 2026), TuLugar Datos, INGAR (September 2026), Santiago Pereyra, Santander mortgage tariff, IMPO (Decree 238/026), El Cronista and Forbes Argentina.