


Summary
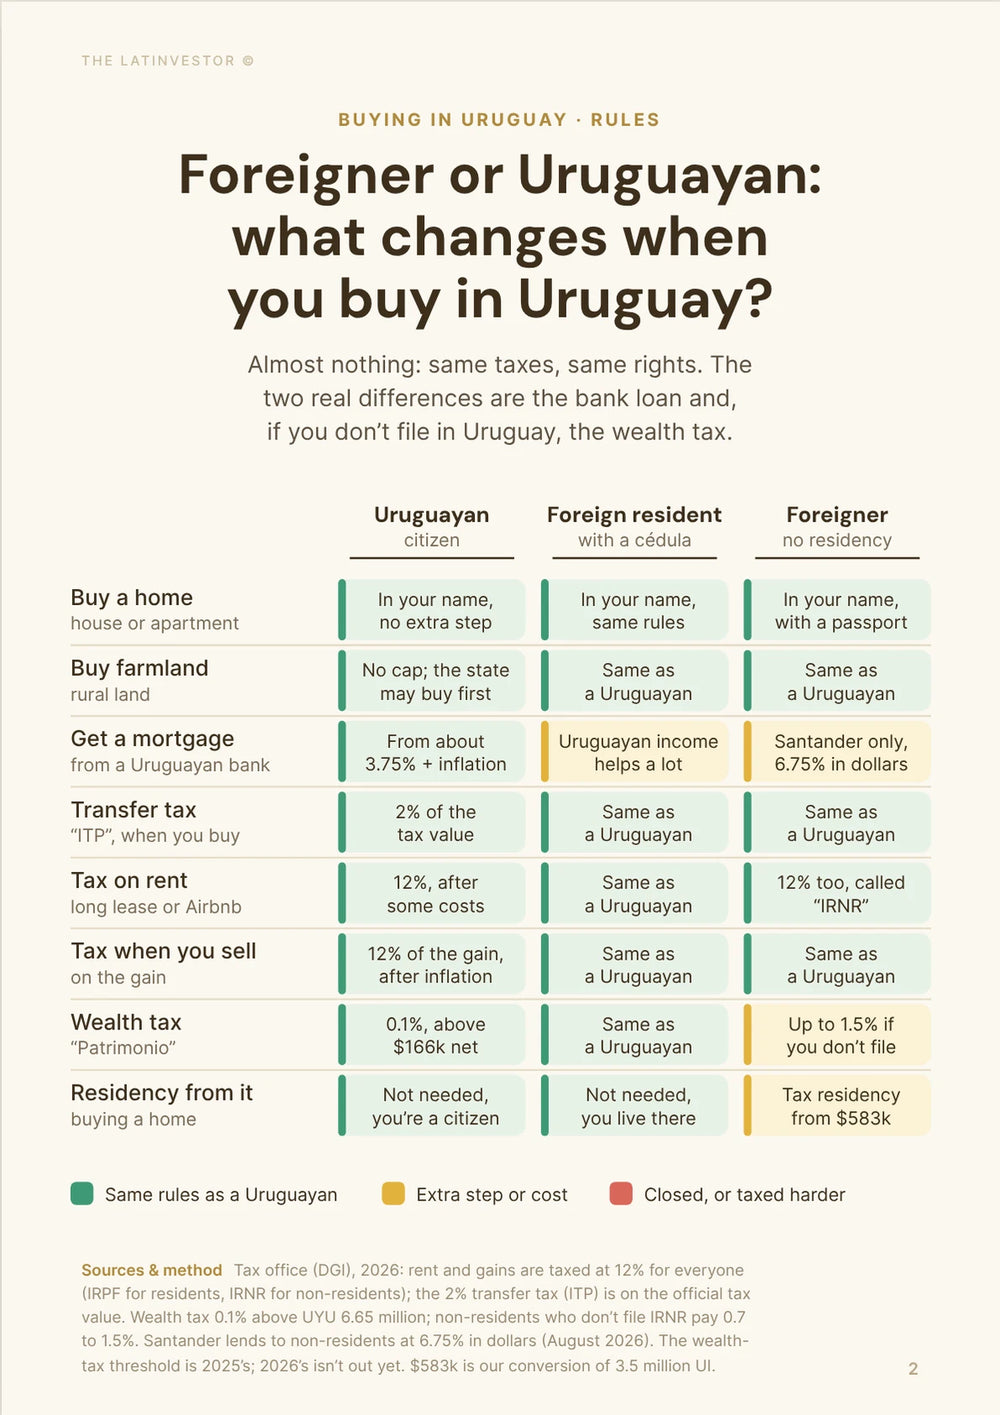
Yes: a foreigner can buy property in Uruguay on the same terms as a local, in their own name and with 100% ownership, but should budget about 6% of the price in buying costs (about 9.5% with an agent).
Apartments, houses, condos and residential land are all open to foreign buyers, with no quota and no special approval; the only nationality-based limit we found is on rural land, where foreign states cannot buy and the land-reform institute (INC) can have a first-refusal right on sales of 500 hectares or more.
The real risks are practical, not legal: title, debts, zoning and building rules. Before you pay a deposit, your escribano checks about 30 years of title history and gets the registry certificates (mortgages, embargoes), proof that municipal taxes and gastos comunes are paid, and the zoning of the padrón.
You don't need a visa, a residence card or a local tax number to buy one home, and you can sign remotely with a power of attorney. But buying does not give you residence: legal residence is a separate Migración procedure (Argentines and other MERCOSUR nationals have a simpler route, with a fee of UI 557.30 in 2026).
Property above UI 3.5 million (about USD 580,000) plus 60 days a year still makes you a tax resident, but since 1 January 2026, under Law 20.446, it no longer opens the 11-year tax holiday for newcomers. The holiday now needs more than 183 days in Uruguay, or a much bigger investment: above UI 12.5 million (about USD 2.1 million) in property.
A normal purchase takes about 30 to 90 days from accepted offer to registered deed, and the escribano (notary) is the key professional, at about 3% of the price plus 22% VAT.
Cash is capped: under Decree 238/026, only UI 200,000 (about USD 33,000) of the price can be paid in cash, or 5% of the deal up to UI 450,000 (about USD 75,000); the rest must go through a bank.
Foreigners can get a mortgage, but it's harder: Santander publishes non-resident rates of 6.75% in dollars for a main home and 6.95% for an investment (August 2026), and you should plan on putting down about 40%: BTG Pactual (formerly HSBC Uruguay) finances up to 60% for non-residents.
Buying costs are 2% transfer tax (ITP) on the cadastral value, about 3% plus VAT for the notary and about 3% plus VAT for the agent, so roughly 6% without an agent, 9.5% with one and 10% to 13% with a mortgage.
Owning costs are modest: our estimate is UYU 15,000 to UYU 80,000 a year in property taxes for a standard home, plus UYU 3,600 to UYU 30,000 for insurance. If you rent out as a non-resident, you pay IRNR at 12% of taxable rent, usually collected as a 10.5% withholding on the gross rent.
Our advice: hire your own escribano before signing anything, send the money by bank transfer from an account you can document, and if residency or tax status is part of your plan, check the post-2026 rules with a tax adviser before you buy, not after.


What can a foreigner own in Uruguay, and what are the limits?
What property types can foreigners legally buy in Uruguay?
Foreigners can buy every main type of residential property in Uruguay: apartments in Montevideo, houses in Punta del Este, units in buildings under propiedad horizontal, villas, townhouses, beachfront homes, building lots and small residential parcels.
The rule is simple: Uruguay treats foreign buyers like local buyers. Article 22 of the Civil Code gives foreigners the same civil rights as citizens, and Investment Law 16.906 gives foreign investors the same treatment as locals.
So you can own a home directly, in your own name, without a trust, a nominee, a local partner or any special structure.
The real limits are practical: building rules in Montevideo, coastal planning rules in Maldonado and Rocha, and short-term rental rules in tourist areas.
Can I own land in my own name?
Yes. A foreign individual can own land in their own name in Uruguay, whether it's the land under a house, a residential lot or the co-ownership share that comes with an apartment.
That doesn't mean every plot is safe, buildable or correctly zoned.
If you look at land in Rocha, Maldonado, Canelones or Colonia, confirm the registered padrón, access, services, coastal rules, building rights and any easements before you pay a deposit.
Rural land is the one area with extra rules: there is no quota for foreign individuals, but foreign states cannot buy farmland, companies that own rural land must have identified owners, and the Instituto Nacional de Colonización can have a right of first refusal on sales of 500 hectares or more.
What other foreign-ownership rules or limits should I know?
There is no extra national foreign-ownership rule for a standard home in Uruguay. The limits that matter are title, zoning, building rules, tax compliance and source-of-funds checks.
There is no foreign quota for apartments or condos, so a foreigner can buy 100% of a unit in Montevideo, Punta del Este, Colonia or anywhere else.
The only registration you need is not a foreigner approval: it's the normal registration of the deed with the Dirección General de Registros once the escribano has signed it.
If you buy through a company, a foreign company that only holds property in Uruguay has to register with the authorities, and Uruguayan companies must declare their real owners. For one home, buying in your own name is usually simpler.
What has changed recently is not ownership but use: Law 20.352 regulates tourist rentals, and the Ministry of Tourism presented a draft registration rule in November 2025 whose entry into force we could not confirm in October 2026.
What's the biggest ownership mistake foreigners make?
The biggest mistake is assuming that a friendly legal system means a property is automatically safe to buy.
Skip the checks and you can end up with a resale that's blocked, debts you didn't know about, a flat you can't rent the way you planned, or a dispute over title or building rules.
Other classic pitfalls: not checking gastos comunes (and arrears) in Montevideo buildings, not reading the co-ownership rules in Punta del Este towers, and not confirming coastal or rural-edge zoning in Rocha and Maldonado.
 Buying in Uruguay as a Foreigner

Which visa or residency status changes what I can do in Uruguay?
Do I need a specific visa to buy property?
No. You don't need a specific visa, a residence card or citizenship to buy a home in Uruguay, and you can buy while visiting as a tourist.
The usual blocker is not the visa but the money: opening or using a bank account that accepts your funds, and proving where the money comes from. The escribano is legally required to check your identity, the real owner and the source of funds.
You don't need a local tax number (RUT) just to buy one home for your own use. Tax registration becomes relevant if you rent out without an agent, run a business or buy through a company.
The usual document set is a passport, marital status information, proof of funds, bank compliance documents, tax information from your home country, and a power of attorney (apostilled) if you sign remotely.
Does buying property help me get residency and citizenship?
Buying property in Uruguay can show ties to the country, but it does not give you legal residence, permanent residence, citizenship or a passport.
Uruguay has no golden visa: one property purchase doesn't get you a residence card.
Legal residence goes through Migración. Argentines, Brazilians and other MERCOSUR nationals have a simpler permanent-residence route (fee of UI 557.30 in 2026, about USD 90); others use the general route and must show means of support.
Property matters more for tax residence, and those rules changed in 2026 (see the next section).
Can I legally rent out property on my visa?
Yes. Your visa status doesn't stop you from renting out a home in Uruguay, but rental tax, registration and building rules still apply.
You don't need to live in Uruguay to rent out: a local inmobiliaria or administrator can manage the lease and collect the rent.
Watch the IRNR tax, the seasonal lease rules (a tourist lease under Law 20.352 lasts up to 120 days), building rules on short stays, and platform rules in places such as Montevideo, Punta del Este, José Ignacio, La Paloma and Punta del Diablo.
 70+pages
Did Law 20.446 close Uruguay's residency-through-property route?
No, but it took away what made it popular. Property worth more than UI 3.5 million (about USD 580,000) plus 60 days a year in the country still makes you a tax resident (DGI; RSM Uruguay, 2026). Since 1 January 2026, though, Law 20.446 (the budget law) no longer gives that route the 11-year tax holiday that drew foreign buyers to Uruguay.
New residents who want the holiday now have two realistic paths: spend more than 183 days a year in Uruguay, or make a much bigger investment.
The 11-year tax holiday (the year you become resident plus 10 years) now asks for property above UI 12.5 million (about USD 2.1 million) bought since 1 September 2025, or a yearly UI 625,000 (about USD 104,000) into approved funds, and you must not have been a Uruguayan tax resident in the 2 previous years.
Foreign investment income of residents outside that regime is now taxed at 12%. People who entered the old regime before the end of 2025 keep their conditions.
What to do: if tax residence is the reason you buy, get the plan checked by a Uruguayan tax adviser before you sign, and keep in mind that none of this gives you a residence card, which is still a separate Migración procedure.
How does the buying process actually work step-by-step in Uruguay?
What are the exact steps to buy property?
The usual steps: choose the property, negotiate, hire your own escribano, sign a reservation (boleto de reserva), complete title and debt checks, sign the promise to sell (promesa de compraventa) or go straight to the deed, transfer the funds, pay the costs and register the deed.
You don't have to be in Uruguay to sign: a properly drafted and apostilled power of attorney lets a representative sign for you, although most foreign buyers still visit for the inspection and the bank.
The deal becomes serious with the signed reservation or promesa and the deposit. Neither has a deposit fixed by law, so what you lose if you walk away depends on the wording: read it before you pay.
A normal purchase takes about 30 to 90 days from accepted offer to deed and registration, longer when banking, an inheritance, developer paperwork or the title history is complicated.
Is it mandatory to get a lawyer or a notary to buy a property?
For a normal registered purchase, an escribano público is essential: the deed, the title review, the taxes and the registry filing all go through them. The usual fee is about 3% of the price, plus 22% VAT on that fee.
The escribano checks and formalizes the transfer. A separate lawyer is useful for disputes, complex contracts, company structures, inheritance issues or unusual developer deals.
Make sure the engagement covers title history, liens, tax debts, municipal debts, building documents, co-ownership rules, rental limits and registration of the final deed.
 70+pages
What checks should I run so I don't buy a problem property in Uruguay?
How do I verify title and ownership history?
The official place is the Dirección General de Registros, usually through your escribano.
The key document is the registry information certificate for the padrón: it shows what the registry holds, which no seller statement can replace.
A standard title study goes back about 30 years and covers the chain of owners, mortgages, liens, inheritances and embargoes.
Pause the purchase if the seller, the registered padrón, the physical unit or the co-ownership plan don't match, or if there's an open promise to sell, mortgage, embargo or succession.
How do I confirm there are no liens?
Have the escribano request the registry certificates and check mortgages, embargoes, easements, promises to sell, usufruct rights and other encumbrances.
Ask specifically about a registered mortgage or embargo: it blocks a clean transfer unless it's cancelled before or at closing.
The best written proof is the official registry certificate, plus written confirmation that municipal taxes, gastos comunes and other property debts are paid.
How do I check zoning and permitted use?
Start with the department's planning office: Montevideo, Maldonado, Canelones, Rocha and Colonia each apply their own plans under the national framework (Law 18.308).
Check the padrón against the local land-use plan, the zoning map, the régimen de suelo or the planning certificate that department issues.
The common trap is buying a beach house or a plot for short-term rental or expansion without checking coastal limits, heritage rules, density limits, parking rules or tourist housing rules.
How much cash can you still use to buy property in Uruguay?
Not much. Uruguay already pushed property payments through banks, and Decree 238/026 sets the cash part of a property deal at UI 200,000 (about USD 33,000), or 5% of the total price with a ceiling of UI 450,000 (about USD 75,000). You can't add the two together.
The rest has to be paid by bank transfer, bank cheque or another traceable means, and the escribano records how it was paid.
This matters most for Argentine buyers used to closing in dollar bills in Punta del Este: plan the transfer weeks ahead, because your Uruguayan bank will ask where the money comes from before it accepts it.
What to check: ask your escribano which limit applies to your deal (contracts signed before the new rules may be treated differently), and keep the paper trail of the funds from your home bank to the seller.
 70+pages
Can I get a mortgage as a foreigner in Uruguay, and on what terms?
Do banks lend to foreigners for homes in Uruguay?
Yes, banks in Uruguay can lend to foreigners for a home, but it's much easier with local residence, local income, a Uruguayan bank account and clean tax documents.
Plan on putting down about 40%. BTG Pactual's non-resident line finances up to 60% of the price, and Santander doesn't publish a higher figure for non-residents. The 80% or more you see in bank ads is for residents with local income.
What decides it is income the bank can verify: foreign income without a local tax history is harder to approve.
Which banks are most foreigner-friendly?
Start with Santander: it's the only bank we found that publishes mortgage rates for non-residents (tariff of 7 August 2026).
Then BTG Pactual (formerly HSBC Uruguay): it has a non-resident line for its Excellence clients, up to 60% financed, but it doesn't allow the mortgaged home to be rented out while the loan runs. Itaú, BBVA, Scotiabank, BROU and Banco Hipotecario del Uruguay (BHU) are worth asking case by case, but none publishes a non-resident rate, so don't take their resident ads as an offer to you.
Without local residence, expect more documents, a smaller loan, a slower answer and a real chance of refusal if your income file is thin.
What mortgage rates are foreigners offered?
Santander's non-resident rates (7 August 2026) are 6.75% a year in US dollars for a main home and 6.95% for an investment property, or 4.75% and 5.72% in UI, before fees and insurance.
A UI loan looks cheaper, but the balance rises with inflation (4.68% over 12 months in September 2026), so compare it with a dollar loan only after adding that. If you earn in dollars or euros, a dollar loan avoids the currency risk.
What will taxes, fees, and ongoing costs look like in Uruguay?
What are the total closing costs as a percent?
Budget about 6% of the price without an agent, about 9.5% with an agent, and 10% to 13% if you take a mortgage.
The main items are the 2% transfer tax (ITP) for the buyer, the escribano at about 3% plus VAT, the agent at about 3% plus VAT when there is one, plus certificates, registry costs and bank charges if you borrow. The seller pays its own 2% ITP.
ITP is charged on the cadastral value, not on the price you pay, and the cadastral value is usually lower, so the tax often ends up under 2% of the price.
The biggest single cost is usually the agent's commission when you pay one; ITP and the notary are the core items you can't avoid.
What annual property tax should I budget?
Our estimate for a standard home is about UYU 15,000 to UYU 80,000 a year in property taxes, roughly USD 375 to USD 2,000 or EUR 335 to EUR 1,780.
The bill has two parts: the contribución inmobiliaria, set by each department (Montevideo, Maldonado…), and the national Impuesto de Primaria, at 0.15% to 0.30% of the cadastral value. Both are based on the cadastral value, not the market price.
The wealth tax (Impuesto al Patrimonio) is 0.10% above a threshold of UYU 6,653,000 (about USD 166,000) for the 2025 tax year. Higher rates of 0.7% to 1.5% apply only to non-residents who don't pay IRNR, so a foreigner who rents out and pays IRNR is not in that bracket.
How is rental income taxed for foreigners?
A non-resident owner pays IRNR at 12% of taxable rental income, computed like the resident IRPF. In practice it's collected as a 10.5% withholding or advance on the gross rent.
If an inmobiliaria manages the rental, it withholds and pays the tax. If you rent out directly, you register with the DGI for a tax number and pay the monthly advances yourself. The small-landlord exemption that some residents get is not open to non-residents.
What insurance is common and how much?
A standard home policy in Uruguay costs about UYU 3,600 to UYU 30,000 a year, roughly USD 90 to USD 750 or EUR 80 to EUR 665.
The usual cover is fire and home, often combined with contents, theft, civil liability, glass breakage, weather damage and home assistance. In apartment buildings, part of the building cover is often paid through the gastos comunes.
What moves the premium most is risk: house or apartment, floor, security, location and exposure to the coast.
Our methodology
This article explains what a foreigner can buy and own in Uruguay, what residency and visa status change, how a purchase works, which checks to run, how much cash you can use, how mortgages work for foreigners, and what buying and owning costs.
Ownership rules come from the legal texts themselves (Civil Code, Investment Law 16.906, Law 18.308, Law 20.352) and from the official registry (Dirección General de Registros). Cost figures combine official rates (ITP, IRNR, Primaria, wealth tax) with market references: INGAR's 2026 cost guides, the Cámara Inmobiliaria Uruguaya for commissions, Santander's published tariff for mortgages, and BSE and BBVA for insurance.
Tax and residency rules come from the DGI (tax residence, the 2026 regime for new residents, rental tax), from IMPO (laws and Decree 238/026 on cash payments), from Migración for legal residence, and from SENACLAFT for the notary's anti-money-laundering checks.
We checked these figures in October 2026. Peso amounts are converted at about 40.1 pesos per US dollar and 45 pesos per euro (BCU, October 2026). Property is priced in US dollars in Uruguay, while taxes and insurance are billed in pesos; amounts in UI (Unidad Indexada) are converted at UYU 6.65 per UI (INE, 1 October 2026).
Limits: the annual property-tax and insurance ranges are our estimates, because the real bill depends on each property's cadastral value and cover; the 40% down payment is a working figure, since only BTG Pactual publishes a non-resident maximum (60%). Closing-cost totals are scenarios, not a government tariff. Rules change: check the latest version with your escribano before you sign.
Key sources used for this analysis include IMPO, Civil Code Article 22, IMPO, Investment Law 16.906, Dirección General de Registros, DGI, ITP transfer tax, DGI, annual and seasonal rents, DGI, regime for new tax residents from 2026, Migración, legal residence, IMPO, Decree 238/026, Santander Uruguay, mortgage tariff, INGAR, notary cost guide, RSM Uruguay, tax residence 2026 and Forvis Mazars, tax residence.


