Summary
Yes, for a well-located, fairly priced apartment you plan to hold for 5 years or more: in October 2026 prices in Uruguay are rising slowly in dollars (+6.3% over 12 months on official promoted-housing sales), but they are flat in real terms and the market is not overheating.
Prices are high, not crazy. Asking prices average USD 3,436/m² for apartments nationwide (TuLugar, October 2026) and USD 2,841/m² across Montevideo's barrios (INGAR, September 2026); we think the most demanded parts of Montevideo and Maldonado sit about 5% to 12% above fair value.
A crash looks unlikely. Inflation was 4.68% in September 2026 and the central bank rate is 6.00%, and nobody is being forced to sell. Our estimate for the next 12 months is +3% to +6% in dollars nationally, about +1% to +4% for ordinary flats in Punta del Este, and a 3% to 7% drop only in a bad year.
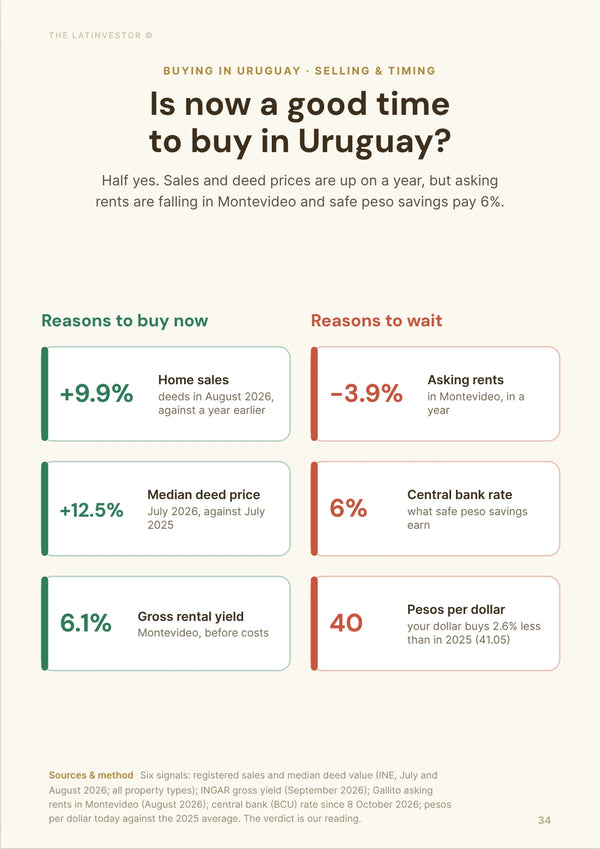
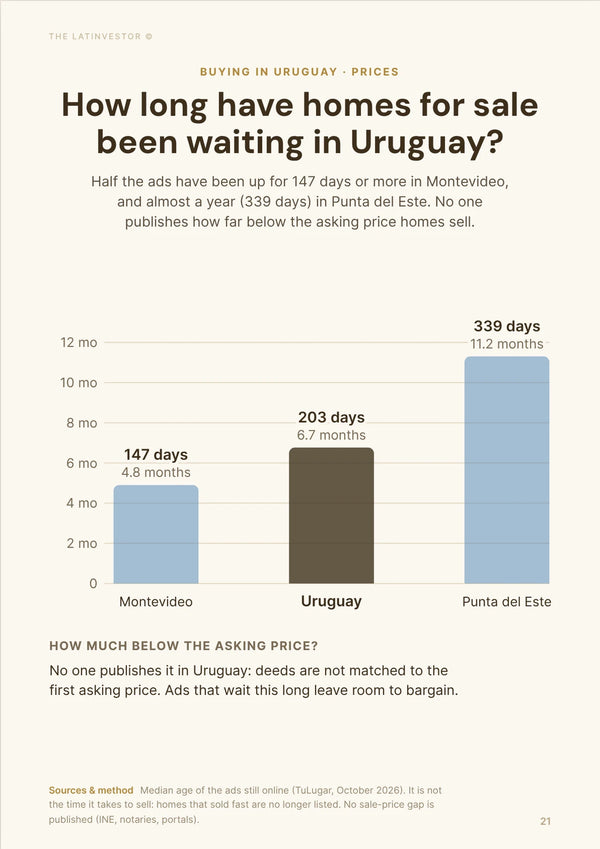
Activity is up: 4,838 property deeds were signed in August 2026, 9.85% more than a year earlier. But listings sit a long time (median active listing age of 203 days nationally, 339 days in Punta del Este), so overpriced homes give you room to negotiate.
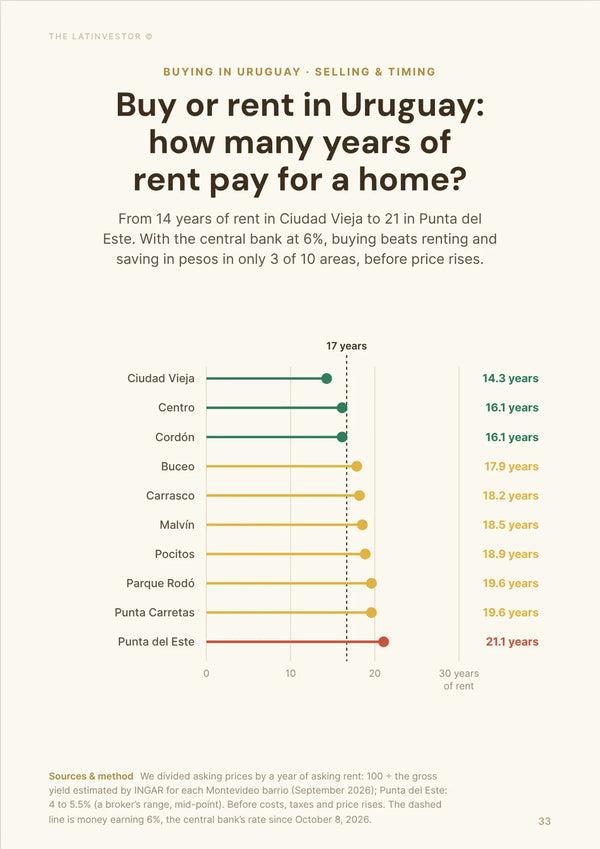
Against rents, Montevideo is fairly priced: a median gross yield of 6.1% means about 16 years of rent to pay back the price. Punta del Este is more stretched, at 4% to 5.5% gross on long leases.
In real terms prices are not running away: promoted-housing prices fell 1.3% over 12 months when measured in UI, Uruguay's inflation-indexed unit, even as they rose 6.3% in dollars.
New supply keeps coming through vivienda promovida (26,242 units sold since the scheme started), and Santander lends to non-residents at 6.75% in dollars, so rules and financing are helping supply more than they push prices up.
Finding tenants is fine, but landlords have lost a bit of power: Montevideo asking rents fell 3.9% over the year to August 2026 (2-bedrooms around UYU 40,065), and INE counted 150,909 active leases, 1.33% fewer than in July.
The for-sale market is not tight overall. Good apartments sell in about 3 to 6 months by our estimate, houses in 6 to 12 months, and high-end villas on the coast often take 9 months or more.
A home above UI 3.5 million (about USD 580,000) plus 60 days a year still makes you a tax resident, but since 1 January 2026 the 11-year tax holiday for new residents needs over UI 12.5 million (about USD 2.1 million) in property, or more than 183 days a year in the country. Buying a home was never a residence permit anyway.
The 2026-27 summer could help coastal owners a little: El Cronista expects Punta del Este summer rents 10% to 20% higher in dollars, Forbes Argentina a season similar to the last one with a shorter peak, and Argentines make up about 50% to 55% of buyers in Maldonado's resort market.
The peso has been stable around 40.1 to 40.3 per dollar since August, and forecasters see 40.5 by the end of 2026, so waiting for a much cheaper Uruguay in dollar terms is not a strong plan.
Count on about 13% to 15% in round-trip costs (buying with an agency, then selling), before capital gains tax. That is why a quick flip rarely works and 5 years is the minimum hold we would plan for. Buy a practical apartment in a liquid area, negotiate hard on stale listings, and rent it long term.


Are Uruguay prices too high, and are they more likely to fall or rise?
Do real estate prices look too high in Uruguay?
Residential prices in Uruguay look about 5% to 12% above fair value in the most demanded parts of Montevideo and Maldonado (our estimate), but closer to fair value in inland cities and less fashionable family areas.
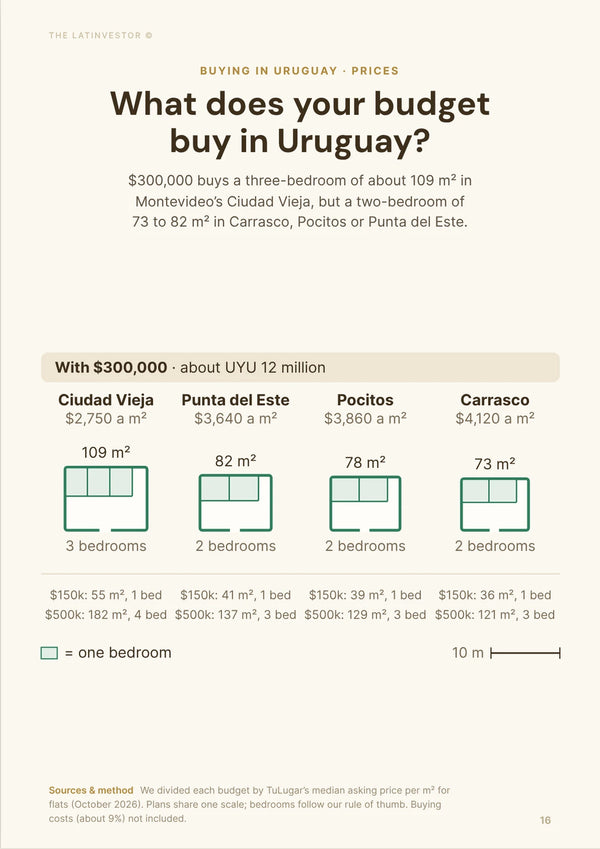
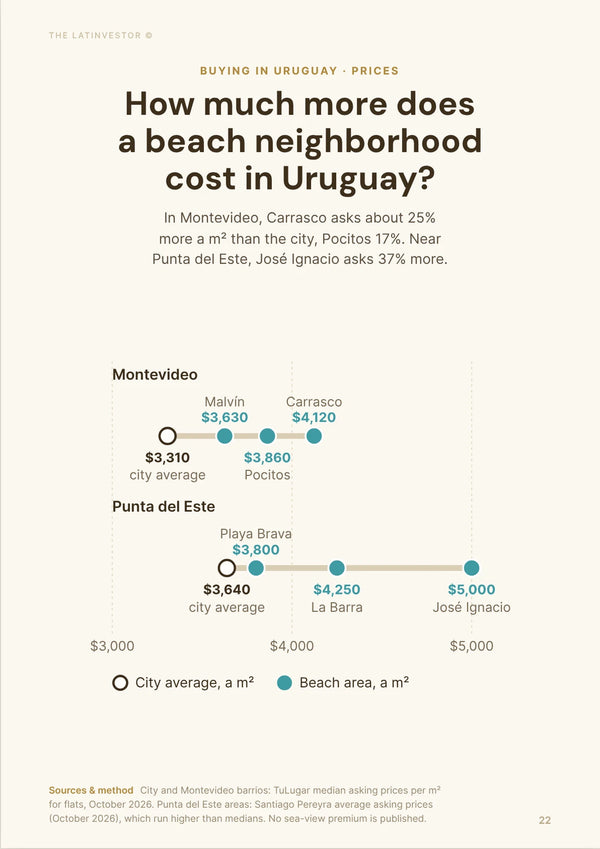
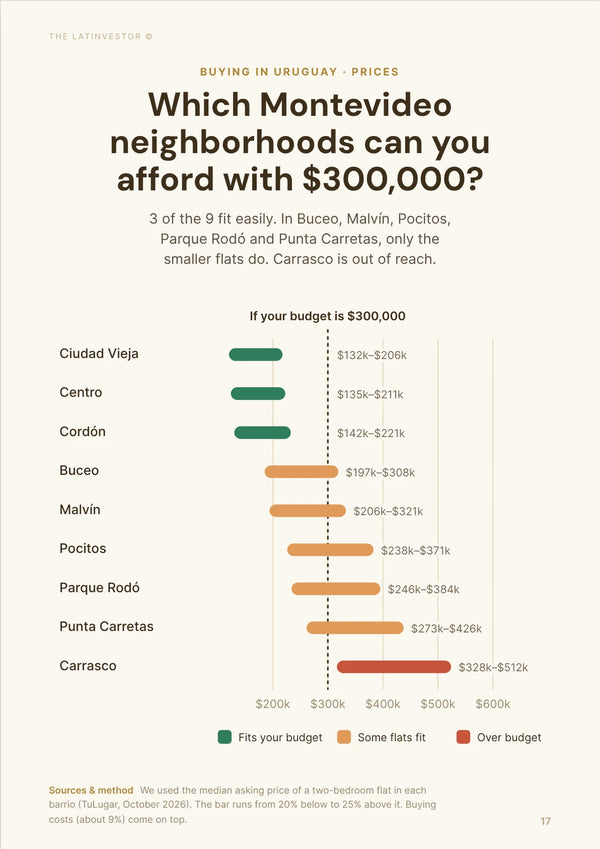
Asking prices are high for the region: apartments average USD 3,436/m² nationally and USD 3,638/m² in Punta del Este (TuLugar, October 2026), and the median across Montevideo's barrios is USD 2,841/m², with Pocitos at USD 3,956 and Carrasco at USD 4,370 (INGAR, September 2026). These are listing prices, not sale prices.
Official data shows prices still rising, but slowly. Promoted-housing sales (vivienda promovida, ANV) rose 6.3% per m² in dollars over the 12 months to April 2026, while the INE median deed was USD 90,000 in July 2026. That median is up 12.5% on a year earlier, but it mixes all property types, so it tells you more about what sold than about price growth.
Does a property price drop look likely?
The chance of a meaningful price fall in Uruguay over the next 12 months looks low to medium, not zero: the market is expensive, but we see no forced selling.
Our base case for the next 12 months is +3% to +6% in US dollars nationally, with better results for liquid apartments and weaker ones for overpriced luxury homes. A bad year (weak Argentine demand, a soft summer, tighter credit) could mean 3% to 7% down (our estimate).
What would most raise the odds of a drop is a sharp jump in local interest rates or inflation, because it would hurt mortgage affordability and local buyer confidence.
That risk looks limited in October 2026: inflation was 4.68% over the 12 months to September (INE), inside the central bank's 3% to 6% target range, and the BCU policy rate was 6.00% from 8 October 2026. Shocks from Argentina, Brazil or global markets can still matter.
Could property prices jump again?
A new national price surge within 12 months looks unlikely for the country as a whole, but possible in the best pockets.
The realistic upside is the top of our +3% to +6% range, a little more for scarce, well-priced apartments in Montevideo and Ciudad de la Costa. In Punta del Este we expect +1% to +4% for ordinary flats and +3% to +6% for prime ones (our estimates); weaker or seasonal stock will likely do less.
The trigger would be stronger Argentine and foreign demand. Argentines already make up about 50% to 55% of buyers in Maldonado's resort market (broker estimate, June 2026), so their mood matters more than anything else on the coast.
Are we in a buyer or a seller market?
Uruguay leans slightly towards sellers for good apartments and correctly priced family homes, but towards buyers for stale luxury listings, oversized houses and seasonal coastal property.
Activity is picking up: INE registered 4,838 sale deeds in August 2026, 9.85% more than in August 2025. But unsold stock ages slowly: the median active listing has been online 147 days in Montevideo, 203 days nationally and 339 days in Punta del Este (TuLugar, October 2026). Those are listing ages, not selling times, yet they show where buyers have room.
We estimate that 15% to 25% of visible listings need a discount to close. Sellers only keep the upper hand when the price is realistic from day one.
 Uruguay Property Market

This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
Are homes overpriced compared with rents and incomes in Uruguay?
Are homes overpriced versus rents or versus incomes?
Homes in Uruguay look moderately expensive versus local incomes but roughly fair versus rents in Montevideo, where gross yields still sit around 6%.
INGAR's September 2026 data puts Montevideo's median gross yield at 6.1%, or about 16 years of rent to pay back the price, against a balanced range of about 14 to 18 years. In Punta del Este, long-term gross yields of 4% to 5.5% (Caetano, July 2026) mean 18 to 25 years, so prime coastal stock is stretched.
Gross is not what you keep. On a 6.1% gross yield, the 10.5% rental tax withholding (IRPF or IRNR) brings you to about 5.5%, and property taxes, empty months, gastos comunes and management take you to roughly 4% to 4.5% net (our estimate).
Against incomes it is harder: a Montevideo or Maldonado home can cost 7 to 10 times a middle-income household's yearly income (our estimate), which is above what many local buyers can comfortably afford.
Are home prices above the long-term average?
Home prices in Uruguay are probably about 5% to 8% above their long-term national trend, and about 8% to 15% above it in desirable Montevideo and Maldonado neighborhoods (our estimate).
The official promoted-housing series rose 6.3% in dollars over the 12 months to April 2026, faster than a calm long-run pace but nowhere near bubble speed. In Montevideo, the same series is up about 26.7% in dollars since the first half of 2021.
In real terms prices are flat: measured in UI, the inflation-indexed unit, promoted-housing prices fell 1.3% nationally over the same 12 months. High construction costs and dollar pricing keep nominal values firm, but this is not a market racing ahead of inflation.
What local changes could move prices in Uruguay?
Are big infrastructure projects coming to Uruguay?
The biggest infrastructure effect on housing is the wider logistics and transport upgrade around Montevideo, Canelones and the Central Railway corridor, and its impact on prices is supportive rather than explosive.
The effect shows up slowly, through jobs and commuting, in places such as Montevideo, Las Piedras, La Paz, Pando, Ciudad de la Costa, Maldonado and Paso de los Toros. We found no reliable figure that ties a specific project to a price jump, so do not pay a premium for a promised project.
Are zoning or building rules changing?
There is no dramatic rezoning. The real driver is vivienda promovida (Law 18.795), which gives tax breaks to investors in approved projects, plus Montevideo's effort to speed up planning and building permits.
The scheme keeps adding supply: ANV counts 26,242 promoted units sold since it began, and 1,073 sales were declared in January to April 2026, 12.7% more than a year earlier. Promoted units sold at an average of USD 2,450 per built m² over the 12 months to April 2026.
The net effect is more supply and a mild cooling of prices over time, not a quick drop, because land, financing and building costs still slow delivery. The areas most affected are Montevideo neighborhoods with services and room to redevelop, such as Cordón, Centro, Aguada, La Blanqueada, Tres Cruces, Parque Batlle and parts of Buceo.
Are foreign-buyer or mortgage rules changing?
Foreigners can still buy homes in Uruguay on the same terms as locals, and we see no ban, quota or special foreign-buyer tax coming. The 2026 change that matters is on tax residency, not on the right to buy (see below).
Mortgages exist for foreigners but are not cheap: Santander's tariff of 7 August 2026 shows 6.75% in dollars for a non-resident's main home and 6.95% for an investment property. BHU, BROU and Itaú publish no non-resident rates.
Lending is growing gradually: bank housing credit was 8.8% higher in March 2026 than a year earlier (BCU). Expect careful lenders, UI-linked loans and strict checks rather than a sudden loosening.
 70+pages
Will it be easy to find tenants in Uruguay?
Is the renter pool growing faster than new supply?
Not right now. In 2026 rental supply has caught up with demand in much of Montevideo: asking rents across the city fell 3.9% over the year to August 2026, with 1-bedrooms listed around UYU 29,368 (about USD 730) and 2-bedrooms around UYU 40,065 (about USD 1,000) a month.
INE counted 150,909 active leases in August 2026, 1.33% fewer than in July, at an average rent of UYU 22,413 (about USD 560) across all types. Demand is steady, not booming: it comes from household formation and people moving to the cities, not from population growth.
New supply comes from vivienda promovida and private projects, but simple units at tenant budgets in Cordón, Tres Cruces, Pocitos, Buceo, La Blanqueada and Parque Rodó are still the easiest to let.
Are days-on-market for rentals falling?
There is no official series, but by our estimate a good, realistically priced Montevideo apartment rents in about 20 to 45 days, and that has not improved now that asking rents are falling.
The gap between areas is large: a good apartment in Cordón, Parque Rodó, Pocitos or Tres Cruces lets far faster than an overpriced house or a seasonal coastal unit, which can need 60 to 120 days outside summer.
What makes a unit rent fast in Uruguay is simple: well-located homes near jobs, universities, hospitals, transport and shops, at a price in line with the market.
Are vacancies dropping in the best areas of Uruguay?
Vacancies are low in the best rental areas, such as Cordón, Pocitos, Parque Rodó, Tres Cruces, Buceo, La Blanqueada, Centro, Aguada and central Maldonado, but with asking rents down they are not falling further.
Our vacancy estimate is about 3% to 5% for well-priced apartments in those areas, about 5% to 8% in weaker urban areas, and much higher off-season in Punta del Este.
Tenants react fastest to clean, modest units with low gastos comunes. Larger or high-expense homes need a sharper price to get the same attention.
Is Uruguay's for-sale market getting tighter?
Is for-sale inventory shrinking in Uruguay?
No source tracks total for-sale inventory in Uruguay with the same method year after year, so nobody can honestly say it is shrinking. What we can see is that good, correctly priced apartments in prime Montevideo go fast, while the rest sits.
By our estimate, good Montevideo apartments have about 4 to 6 months of supply, close to a balanced market, while luxury houses and seasonal coastal homes have more. The long median listing ages (147 days in Montevideo, 339 in Punta del Este) back this up.
Sellers of good property in Uruguay tend to wait rather than cut sharply, because inflation is under control and few are forced to sell.
Are homes selling faster?
Well-priced homes in Uruguay sell at a steady pace: by our estimate about 3 to 6 months for practical, well-located apartments and 6 to 12 months for family houses.
More deals are closing (deeds up 9.85% over the year to August 2026), but we see selling times as broadly flat for good apartments and slightly longer for expensive houses and seasonal coastal property, because buyers are picky, not absent.
Are new listings slowing down?
There is no reliable national figure for new listings. Our reading is that fewer prime apartments are coming to market than other stock, while luxury and coastal listings stay plentiful.
Season matters: the coastal market wakes up around the southern summer (December to February), so mid-year listings can look quiet without the market being frozen.
Owners of good apartments in Montevideo and Maldonado feel little pressure to discount or sell quickly, which keeps that segment thin.
Is new construction failing to keep up?
Not everywhere. Promoted-housing sales were up 12.7% in January to April 2026, but new building still lags in the exact neighborhoods where tenants and buyers want simple, walkable apartments.
Vivienda promovida and faster permits help, while construction costs, scarce central land and financing still limit how fast new units arrive.
The main bottleneck is well-located land at a viable price, especially in Montevideo: developers can plan more easily than they can deliver affordable units on the most wanted streets.
 70+pages
Did Law 20.446 kill the cheap tax-residency route through property?
It killed the tax perk, not the residency. Owning property worth more than UI 3.5 million (about USD 580,000) and spending 60 days a year in Uruguay still makes you a tax resident (DGI; RSM Uruguay, 2026). But since 1 January 2026, under budget Law 20.446, it no longer gets new residents the tax holiday: that now needs more than UI 12.5 million (about USD 2.1 million) in property, or more than 183 days a year in the country.
The tax holiday for new residents now lasts 11 years (the year you qualify plus 10), but foreign capital income of residents outside that regime is now taxed at 12%. People who entered the old regime before the end of 2025 keep their conditions.
Buying a home in Uruguay does not give you a residence permit: there is no golden visa, and legal residence is a separate process with Migración. What this means for timing: if residency was your main reason to buy a USD 600,000 home in 2026, that reason is gone. Buy for the property itself, and check your own tax position with an accountant before signing.
Will the 2026-27 summer and Argentine buyers push coastal prices up?
Summer rents may rise: El Cronista reported on 11 October 2026 that Punta del Este summer rents are expected 10% to 20% higher in dollars, based on early bookings. Forbes Argentina (3 October 2026) is more cautious: the real estate chamber expects a season "similar" to last summer, high-end prices in José Ignacio at last season's level, and a shorter peak, from Christmas to about 10 January. Premium new builds there are listed at USD 6,000 to 9,000/m².
Short stays work only in season. On AirROI, Punta del Este listings averaged 34.6% occupancy at USD 192 a night over August 2025 to July 2026, about USD 11,445 a year in revenue, with a December to February peak of 50.6% at USD 221.
Argentines are the swing buyers: about 50% to 55% of buyers in Maldonado's resort market (broker estimate, June 2026). But iProfesional reported in July 2026 that fewer Argentines are choosing Uruguay to invest, so do not count on a new wave of them pushing prices up. Our advice: a better summer helps rental income more than resale prices, so judge a coastal unit on its year-round numbers.
 70+pages
Should you wait for the peso to weaken before buying in Uruguay?
Probably not. The peso has held between 40.1 and 40.3 per US dollar since August 2026, after a 2026 range of 37.4 (27 January) to 40.8 (24 March). Uruguay has been expensive in dollar terms since 2023, and that has not changed.
The BCU's October 2026 survey of economists expects 40.5 pesos per dollar at the end of 2026 and 41.4 at the end of 2027, a move of about 3% over a year. Since property is priced in dollars, a weaker peso mainly makes local costs (rents, gastos comunes, taxes) cheaper for you; it does not cut the purchase price.
If you hold euros, the bigger swing is euro versus dollar: the euro has lost about 3% against the dollar since early September. Watch that rate, not the peso.
Will it be easy to sell later in Uruguay?
Is resale liquidity strong enough?
Resale is easy enough for well-located apartments and practical homes, and much harder for oversized houses, remote beach homes and units with high monthly building costs.
We estimate about 3 to 6 months to sell a good, well-priced apartment, while luxury or seasonal property often takes 9 months or more.
What sells fastest in Uruguay is boring practicality: a good floor plan, moderate gastos comunes, a well-run building and a location near real daily demand.
Is selling time getting longer?
Not for the best-priced apartments, but yes for expensive or poorly positioned property, where the buyer pool is thin.
Our realistic ranges are about 3 to 6 months for liquid apartments, 6 to 12 months for family homes and 9 months or more for high-end coastal villas or luxury property.
The main reason selling time stretches is affordability: most local buyers earn in pesos, while prices are negotiated in US dollars.
Is it realistic to exit with profit?
Selling at a profit is likely for a well-bought property held several years, and unlikely for a quick flip once taxes, commissions and fees are paid.
Five years is the minimum hold that usually makes a profit realistic, giving rent and gradual price growth time to cover the transaction costs.
Those costs are heavy. As a buyer you pay about 6% without an agency and about 9.5% with one (transfer tax of 2% of the cadastral value, notary about 3% plus VAT, agency about 3% plus VAT), and 10% to 13% with a mortgage. As a seller you pay the agency again (about 3.7% with VAT) plus your own 2% transfer tax on the cadastral value. The round trip comes to about 13% to 15% of the price (our estimate): on a USD 200,000 home, about USD 26,000 to 30,000, or EUR 23,200 to 26,700. Capital gains tax of 12% of the taxable gain comes on top.
The best way to improve your odds is to buy a liquid home below the local market price, especially a small or mid-sized apartment in Cordón, Pocitos, Parque Rodó, Tres Cruces, Buceo, La Blanqueada or central Maldonado.
Our methodology
This article judges whether buying a home in Uruguay makes sense in October 2026. It covers price levels and direction, prices against rents and incomes, rule changes, rental demand, how fast homes sell, the 2026 tax-residency change, the coastal summer season, the peso and the cost of selling later. It focuses on Montevideo, Maldonado and Punta del Este, where most foreign buyers look.
We built the figures from official data first: INE (sale deeds, rental contracts, inflation), ANV (promoted-housing sale prices), and the BCU (policy rate, credit, exchange-rate expectations). We then used portals and market reports for what official data does not cover: TuLugar and INGAR for asking prices, listing ages and gross yields, El País / Inmuebles Data (Gallito) for Montevideo asking rents, Caetano for Punta del Este yields, and AirROI as the only short-stay data source.
For rules, we used the DGI (tax residency, rental tax, transfer tax, capital gains), IMPO for laws such as Law 20.446 and Law 18.795, and Migración for legal residence. Buying costs follow INGAR's October 2026 breakdown.
We checked these figures in October 2026. Peso amounts are converted at about 40.1 pesos per US dollar and 45 pesos per euro (BCU, October 2026). Property in Uruguay is priced in US dollars, while rents and running costs are mostly paid in pesos.
Limits: TuLugar and INGAR show asking prices, not sale prices, and listing age is not the time it takes to sell. The INE median deed mixes all property types, and the ANV series covers promoted housing only. Uruguay publishes no national price index, inventory, vacancy or days-on-market series, so the ranges we label "our estimate" are our own judgment and should be read as orders of magnitude.
Key sources used for this analysis include INE sales indicators (August 2026), INE rental indicators (August 2026), ANV price report No. 50, BCU monetary policy, BCU expectations survey, TuLugar, INGAR, AirROI, DGI new-residents regime and MVOT Law 18.795.