Summary
Yes. Home prices in Mexico rose 7.9% in the first half of 2026, according to SHF, and all 32 states are still in positive territory.
Growth is cooling, not reversing. It peaked at 10.9% in 2023, then eased to 9.2% in 2024, 8.7% in 2025 and 7.3% a year in the second quarter of 2026.
Homes are still beating inflation by a wide margin: 7.9% price growth against 3.45% consumer inflation in September 2026.
The bill keeps getting bigger. SHF's median mortgaged home went from about MXN 631,000 in 2019 to roughly MXN 1.30 million in mid-2026, about double.
In dollars, the rise is steeper still. At about 18.6 pesos per dollar, against a 19.20 average in 2025, a home bought in pesos costs a dollar buyer roughly 11% more than a year ago.
Demand isn't the problem: about 8.33 million households, around 21% of the total, still live in inadequate housing. Turning that need into purchases is the problem.
Formal construction is well below 2018, with new-home registrations down 32% by 2024. But registered new-housing inventory jumped 34.6% in 2025, so stock is starting to build up in places.
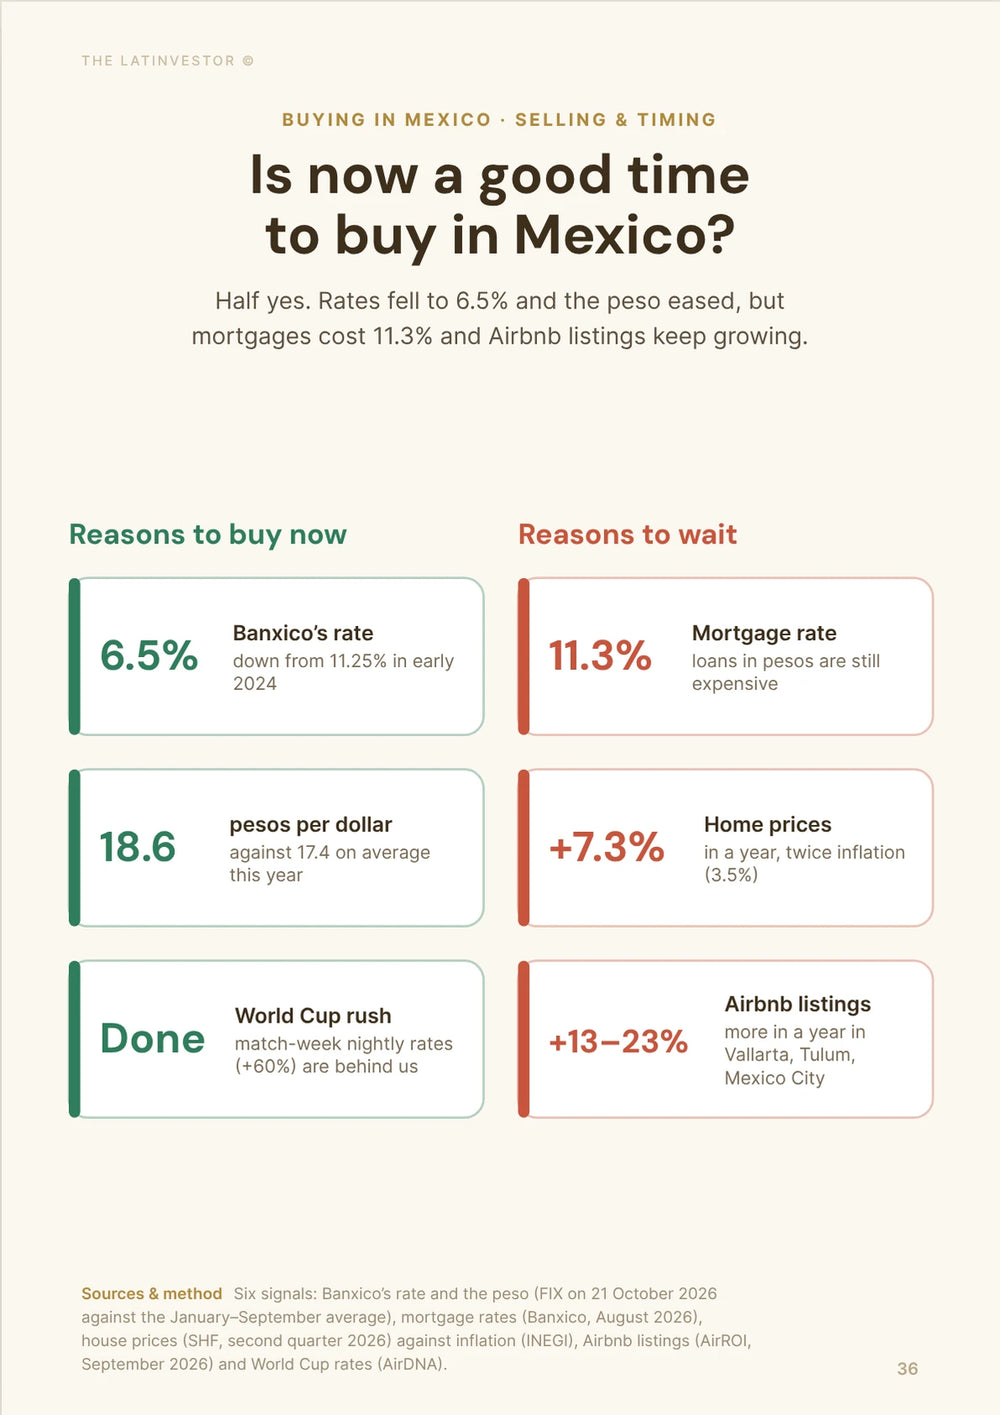
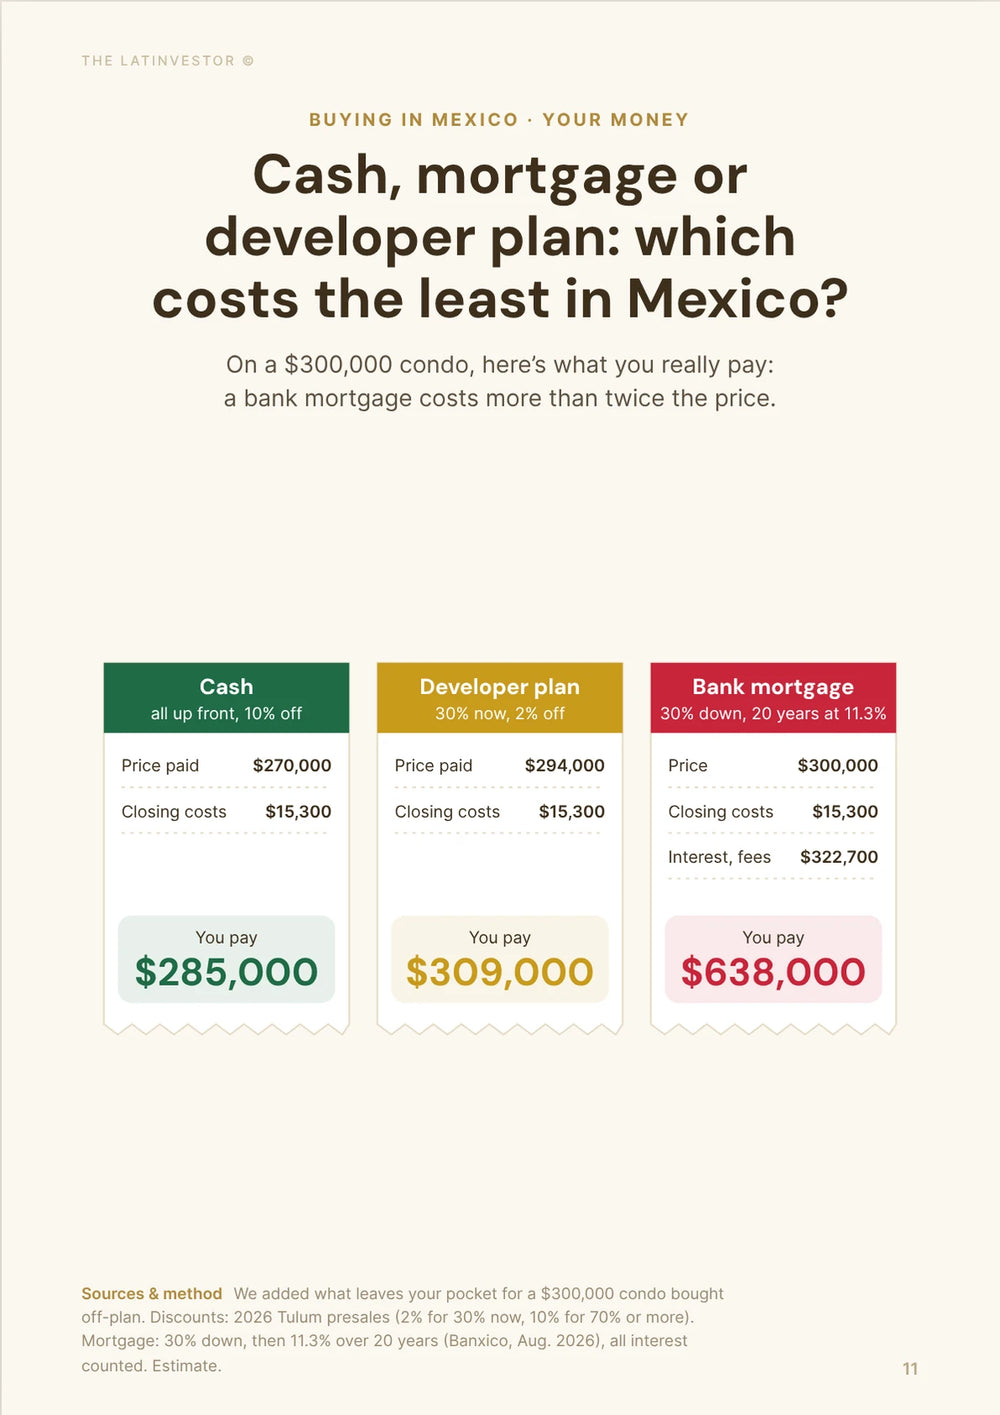
Banxico has cut its policy rate from 11.25% to 6.50%, yet the average mortgage quote was still 11.31% in August 2026. Don't wait for cheaper loans: analysts expect no further cut in 2026.
Growth is spread out but uneven. Guadalajara rose 11.1% and Tijuana 9.7% in the first half of 2026, while the Mexico City area managed 4.6%.
Coastal states are still above average (Quintana Roo +11.5%), but Tulum shows the other side: property sales roughly halved between 2023 and 2025.
Nearshoring helps in the north and in factory hubs: foreign investment hit a first-half record of about $35 billion in 2026, and Jalisco, Baja California and Nuevo León are all above the national rate.
The cheap end is the tightest. Economic and social housing rose 10.0% in the first half of 2026, against 6.7% for middle and residential homes.
The federal housing program has 667,000 homes contracted and 277,000 under construction, but it targets low-income families, not the areas foreigners buy in.
Prices are rising on a market that isn't borrowing more: BBVA counted only 0.3% more mortgages in the first half of 2026 than a year earlier.
The bottom line: no national bubble, but a mature, uneven market. The risk now is overpaying for one condo in one oversupplied resort, not a countrywide crash.

How fast are Mexican home prices rising in 2026?
Fast, but less than before: home prices were up 7.9% in the first half of 2026 and every state still recorded an increase.
The SHF housing-price index is the clearest national measure. Homes bought with a mortgage gained 7.3% year over year in the second quarter, after 8.6% in the first, which puts the first half at 7.9%.
The growth is broad. About 17 of the 32 states beat the national rate, and the other 15 still went up. Guadalajara rose 11.1%, Tijuana 9.7%, Puebla-Tlaxcala 8.5% and Monterrey 8.3%.
The catch: prices look much stronger than activity. SHF's appraisals fell 1.1% in 2025, the number of new mortgages barely moved in the first half of 2026 and mortgages are still expensive. Prices are being pushed up by scarce supply, not by a rush of buyers.
| Measure | Latest reading | What it shows |
|---|---|---|
| Mexico home prices, first half of 2026 | +7.9% | Still strong national growth |
| Second-quarter growth | +7.3% | Growth continues, but more slowly |
| Consumer inflation (September 2026) | 3.45% | Homes still gaining in real terms |
| Guadalajara | +11.1% | One of the strongest large markets |
| Tijuana | +9.7% | Border demand still strong |
| States with positive growth | 32 of 32 | No region going backwards |
Is Mexico's housing boom slowing down?
Yes, slowly. Prices are still rising, but the pace has come down from the post-pandemic peak.
SHF recorded national growth of 10.9% in 2023, 9.2% in 2024 and 8.7% in 2025. It was 8.6% in the first quarter of 2026, then 7.3% in the second.
That's a gradual cooling, not a turn. Prices have risen every year since the pandemic, including 5.8% in 2020, 7.9% in 2021 and 8.9% in 2022.
Compounding SHF's annual increases from 2019 through 2025 gives roughly 78% in nominal terms. So today's 7% to 8% comes on top of a very large run-up.
| Period | SHF national home-price growth |
|---|---|
| 2019 | 8.6% |
| 2020 | 5.8% |
| 2021 | 7.9% |
| 2022 | 8.9% |
| 2023 | 10.9% |
| 2024 | 9.2% |
| 2025 | 8.7% |
| First half of 2026 | 7.9% |
Are Mexican property prices still beating inflation?
Yes. Home prices are rising more than twice as fast as consumer prices.
SHF measured 7.9% growth in the first half of 2026, while INEGI put annual inflation at 3.45% in September 2026. That's a real gain of roughly four and a half points.
Good news for owners, bad news for buyers: unless incomes catch up, every year like this makes a home harder to afford.
How much more expensive is Mexican property than before the pandemic?
About twice as expensive: the typical mortgaged home costs roughly double what it did in 2019.
According to SHF, the median value of a mortgaged home was about 631,000 pesos in 2019. By 2025, it had climbed to about 1.21 million pesos, an increase of around 92%.
The average went from roughly 1.09 million pesos to 1.86 million pesos over the same period, about 70% more. In the second quarter of 2026, SHF put the national median near 1.30 million pesos and the average close to 1.96 million pesos (about US$105,000).
That's why the market feels much less affordable even as the growth rate cools: 8% on today's prices adds far more pesos than 8% did six years ago.
| SHF measure | 2019 | 2025 | Approx. increase |
|---|---|---|---|
| Average mortgaged-home value | MXN 1.09m | MXN 1.86m | +70% |
| Median mortgaged-home value | MXN 631k | MXN 1.21m | +92% |
| Annual home-price growth | 8.6% | 8.7% | Similar rate, much higher base |
Is Mexican property getting more expensive in dollars?
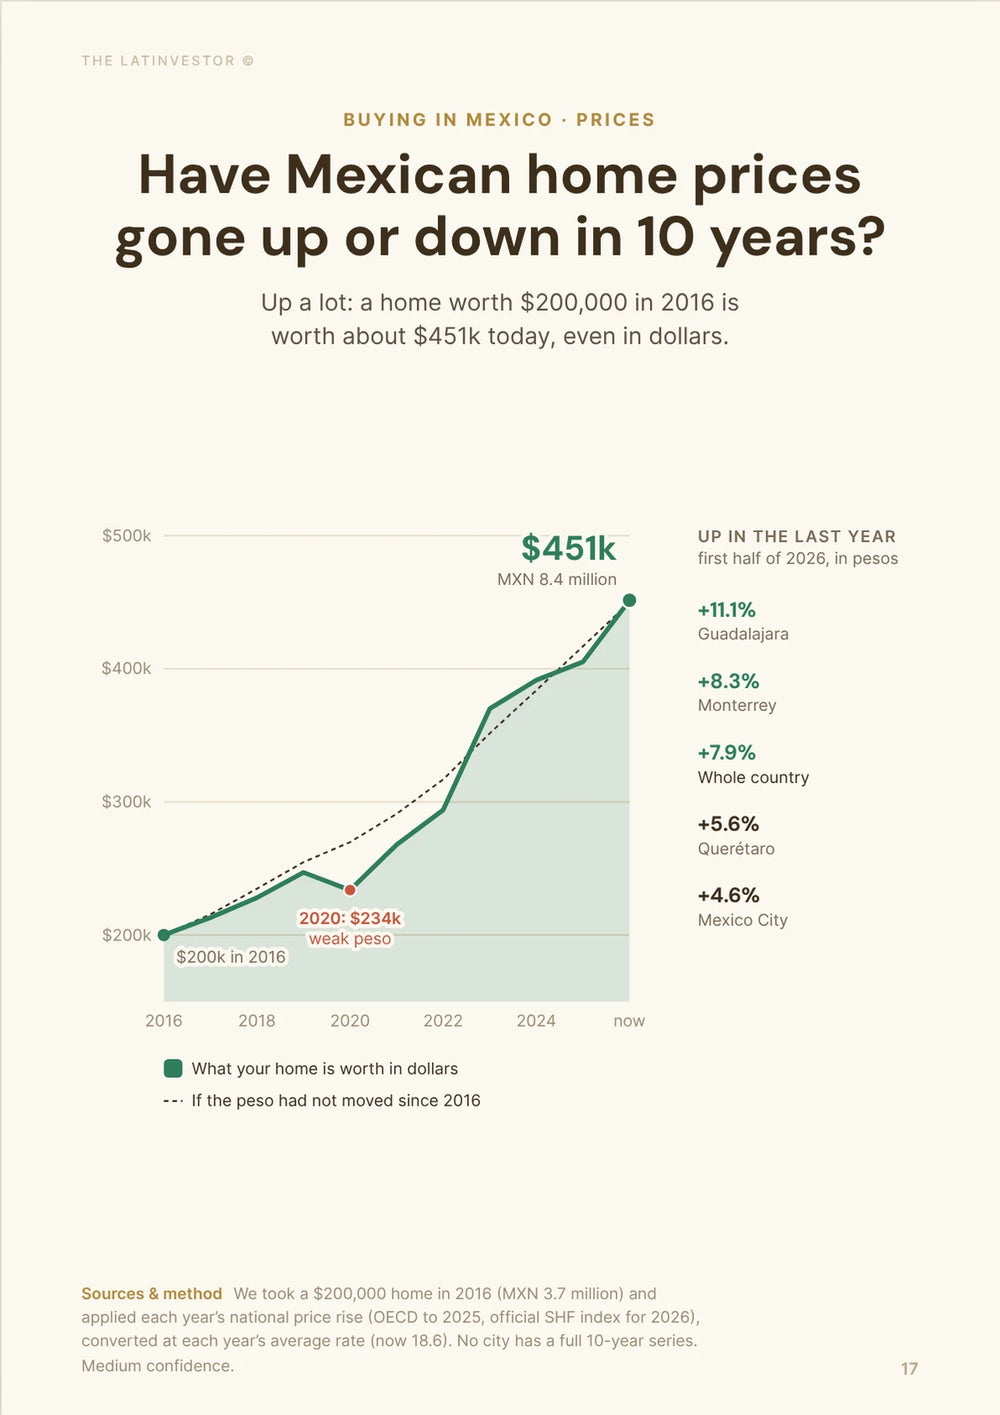
Yes. For someone paying in dollars, a Mexican home costs roughly 11% more than a year ago, more than the 7.9% rise in pesos.
The reason is the peso. The dollar averaged 19.20 pesos in 2025 and buys about 18.6 today, around 3% fewer pesos. Put that on top of 7.9% price growth and you get roughly 11%.
It could have been worse. The peso was below 17 per dollar in early September 2026 and has weakened since, crossing 18 on October 1. At 17, the increase in dollars would have been more than 20%.
What to do: negotiate the price in pesos if you can, so you control when you convert, and don't count on a weaker peso to save you money. Most end-2026 forecasts sit between 17.3 and 18.2 pesos per dollar, all stronger than today's rate.
Does Mexico still have enough housing demand to keep prices rising?
Yes. The need is huge, but many households can't turn it into a purchase.
SEDATU and CONAVI's 2025 update counted about 8.33 million households, around 21% of the total, living in inadequate housing. Government projections also point to roughly 500,000 new households a year that need a home.
The complication is affordability. A household that needs a better home doesn't automatically become a buyer. High prices, mortgage rates above 10% and limited access to formal credit keep much of that demand in rentals, informal housing or overcrowded homes.
So Mexico doesn't lack demand. It lacks homes at prices people can pay.
Is Mexico building enough homes, or is new stock starting to pile up?
Both, depending on the segment. Formal construction is still far below its pre-pandemic level, but unsold new stock grew sharply in 2025.
Registro Único de Vivienda data analyzed by SHF show 262,977 new-home registrations in 2018 and 178,599 in 2024, a drop of 32%. First-half registrations fell another 3.9% in 2025, to 91,581.
Against roughly half a million new households a year, that's not much. The two numbers aren't perfectly comparable, since many homes are built outside the formal developer system, but the gap explains why supply stays tight.
The twist: BBVA Research found registered new-housing inventory up 34.6% in 2025. Developers are building fewer homes, yet more of them are sitting unsold, which points to homes built at prices or in places that don't match what buyers can pay.
Buyers have turned to existing homes. Used homes were 53.4% of SHF-financed purchases in 2019 and 63.1% in 2025, almost two out of three.
| Indicator | Earlier level | Recent level | Change |
|---|---|---|---|
| New-home registrations | 262,977 in 2018 | 178,599 in 2024 | -32% |
| First-half registrations | — | 91,581 in 2025 | -3.9% YoY |
| Registered new-housing inventory | 2024 | 2025 | +34.6% |
| Used-home share of financed purchases | 53.4% in 2019 | 63.1% in 2025 | +9.7 pts |
| Approx. annual new household need | — | ~500,000 | Far above formal registrations |
Why haven't Banxico's rate cuts made mortgages cheaper?
Because banks price mortgages on long-term funding costs and risk, not on the overnight rate, so Banxico's cuts have barely reached borrowers.
Banco de México has cut its policy rate from 11.25% to 6.50%. Yet the weighted rate on new bank mortgages was 10.13% in March 2026, against 10.29% in October 2024 and 10.15% in October 2025. Banxico's average fixed-rate mortgage quote, a different series, was 11.31% in August 2026, while the rate banks actually granted averaged 9.99% in June, according to the banking association ABM.
And more cuts aren't coming soon. A Citi survey published in October 2026 found most analysts expect no change in the policy rate for the rest of 2026 or in 2027.
Expensive credit has slowed buyers more than prices: lending is flat, yet prices are still up 7.9%. What to do: don't delay a purchase waiting for cheaper loans, compare fixed-rate offers from several banks, and if you pay cash, use it to negotiate, since most local buyers depend on a mortgage at 10% or more.
Where are property prices rising fastest in Mexico now?
In a mix of border, tourism and industrial states, not in one region.
SHF puts Tamaulipas at about 11.8% in the first half of 2026, followed by Quintana Roo at 11.5%, Jalisco at 11.2%, Aguascalientes at 10.7% and Nayarit at 10.6%. Baja California rose 9.9%, Baja California Sur 9.8%, Yucatán 9.6%, Sinaloa 9.5% and Sonora 9.4%.
The reasons differ. Quintana Roo, Nayarit and Baja California Sur run on tourism, second homes and migration. Baja California and Sonora live off the border and factories. Jalisco has both Guadalajara's job market and a popular coast.
Keep in mind that Tamaulipas starts from the lowest average price of any state, about 1.15 million pesos, so a big percentage there is a small amount in pesos.
| State | First-half price growth | Main demand exposure |
|---|---|---|
| Tamaulipas | 11.8% | Border / industrial |
| Quintana Roo | 11.5% | Tourism / migration |
| Jalisco | 11.2% | Guadalajara / industry / tourism |
| Aguascalientes | 10.7% | Manufacturing / urban growth |
| Nayarit | 10.6% | Tourism / second homes |
| Baja California | 9.9% | Border / manufacturing |
| Baja California Sur | 9.8% | Tourism / foreign demand |
| Yucatán | 9.6% | Migration / tourism |
Is Guadalajara really growing faster than Mexico City?
Yes. Guadalajara rose 11.1% in the first half of 2026, against 4.6% for the Valle de México metro area.
At state level, Jalisco gained about 11.2%, while Mexico City recorded 3.9%, the weakest of the 32 states.
Mexico City is still by far the most expensive: SHF put its average mortgaged-home value near 4.29 million pesos (about US$230,000) in the second quarter of 2026, more than twice the national 1.96 million.
That high base makes double-digit growth harder. Guadalajara has a big job market, tech and manufacturing, and lower prices, so it has more room to move. For a buyer, Mexico City is the steadier long-term bet; Guadalajara is where momentum is.
| Metropolitan area | First-half home-price growth |
|---|---|
| Guadalajara | 11.1% |
| Tijuana | 9.7% |
| Puebla-Tlaxcala | 8.5% |
| Monterrey | 8.3% |
| León | 7.9% |
| Querétaro | 5.6% |
| Toluca | 5.1% |
| Valle de México | 4.6% |
Are Mexico's coastal markets still booming, or is Tulum a warning?
The state numbers say yes, but the ground looks mixed: the indexes keep rising while some resort towns are clearly struggling to sell.
Quintana Roo rose about 11.5% in the first half of 2026, Nayarit 10.6%, Baja California Sur 9.8% and Yucatán 9.6%, all above the 7.9% national rate. Baja California Sur's average SHF value reached about 2.62 million pesos, second only to Mexico City.
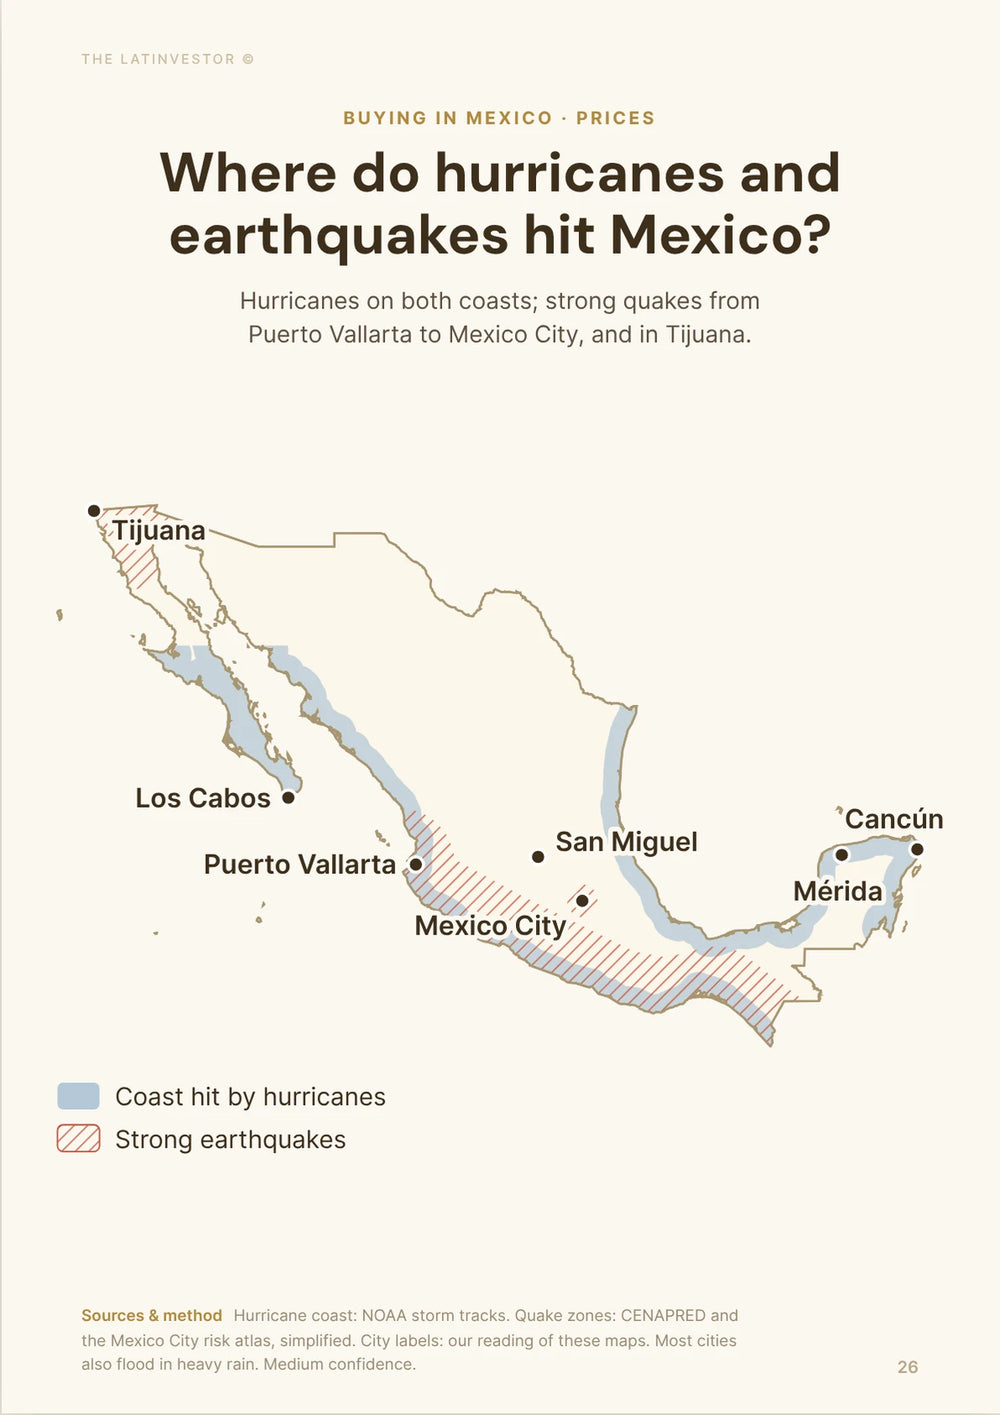
Tulum is the counter-example. Property sales fell from 3,487 in 2023 to 1,711 in 2025, according to El Economista, and AirDNA shows nightly rates down 23.6% in a year. A rising state index tells you little about one condo in an oversupplied town.
Keep in mind that SHF's index tracks homes bought with a mortgage, mostly by locals, while many resort condos are bought in cash or in dollars. Check local sales and rental data, not just the state number.
Is nearshoring still pushing up property prices in Mexico?
Yes, in the cities where factories keep coming, mainly in the north and in big manufacturing hubs.
Mexico attracted about $35 billion of foreign direct investment in the first half of 2026, a record for a first half, according to the Economy Ministry. Nuevo León received roughly $3.7 billion and Monterrey's housing prices rose 8.3%, Baja California around $1.7 billion with prices up 9.9%, and Jalisco about $1.4 billion with prices up 11.2%.
The link takes time. A factory announcement does little on its own; years of investment bring workers, suppliers and infrastructure, and that has now built up in places like Monterrey and Tijuana.
It's only part of the story, though. Tourism-driven Quintana Roo and Nayarit are growing just as fast without it.
Are cheaper homes rising faster than expensive homes in Mexico?
Yes. Cheaper housing is rising faster than middle and upper-end housing, which shows where the shortage hurts most.
SHF reported 10.0% growth for economic and social housing in the first half of 2026, against 6.7% for middle and residential housing.
That 3.3-point gap matters because lower-income buyers are the least able to absorb higher payments. It's not a sign of rising purchasing power; it's too many households chasing too few affordable homes.
The rest of the breakdown fits: detached houses gained 8.4%, new homes 8.3%, used homes 7.5%, and apartments and condos 7.4%.
| Housing type | First-half price growth |
|---|---|
| Economic / social housing | 10.0% |
| Detached houses | 8.4% |
| New housing | 8.3% |
| All housing | 7.9% |
| Used housing | 7.5% |
| Condos and apartments | 7.4% |
| Middle / residential housing | 6.7% |
Can Mexico's government housing program cool property prices?
Eventually, at the low end. The Vivienda para el Bienestar program is now big, but it targets low-income families and few homes have been handed over so far.
SEDATU reported 667,000 homes contracted by September 2026, 277,000 under construction and 89,000 assigned to families. The target is 1.8 million homes over the presidential term, with most houses priced around 600,000 pesos for eligible workers; Infonavit raised the ceiling from 630,000 to 862,000 pesos on September 29, 2026.
Against a private market that struggles to build affordable homes, that's significant. Against 8.33 million households in inadequate housing and about half a million new ones each year, it's not enough to end the shortage.
For foreign buyers, the effect is close to zero: these homes go to qualifying low-income Mexican households, far from the condos and resort areas foreigners look at.
Are homes selling as fast as prices are rising in Mexico?
No. Prices are rising much faster than sales or lending.
SHF reported that appraisals fell 1.1% in 2025, while prices rose 8.7%. In the first half of 2026, BBVA Research counted only 0.3% more mortgages than a year earlier, and the amount lent was down 0.1% after inflation.
Appraisals and mortgages don't capture cash sales, but the gap is hard to ignore. Buyers aren't rushing in; limited supply is letting sellers ask more while expensive credit keeps volumes flat.
That kind of gap usually closes through slower sales, longer listings and discounts, starting with new developments. It's already visible in Tulum.
Is Mexico's property market in a bubble?
Not nationally. Mexico lacks the usual ingredients of a broad housing bubble.
Credit isn't cheap: mortgages cost 10% to 11%. Lending isn't growing. Formal construction is well below 2018. And there's a large structural housing shortage.
That makes today's price growth easier to explain by scarcity than by speculation.
Local markets are another matter. Resort towns with heavy investor buying, short-term rentals and foreign demand can drift away from local incomes, and some neighborhoods can end up with too many condos even while the country lacks homes. Tulum is the obvious example.
Where are buyers most likely to overpay right now?
In resort condos sold on rental promises, where prices kept rising while rents and sales weakened.
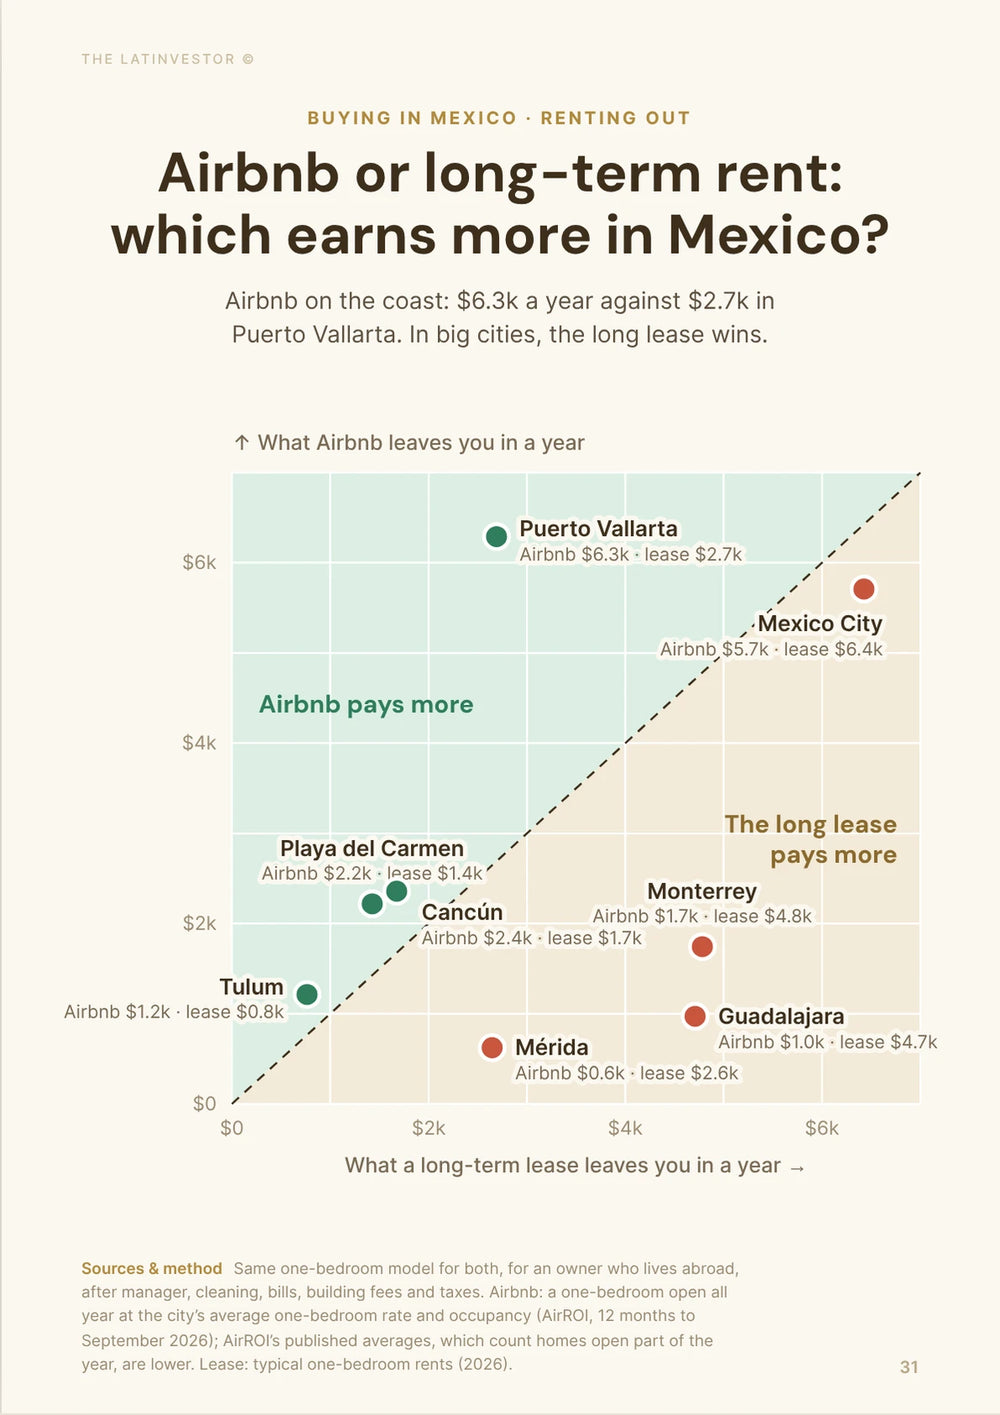
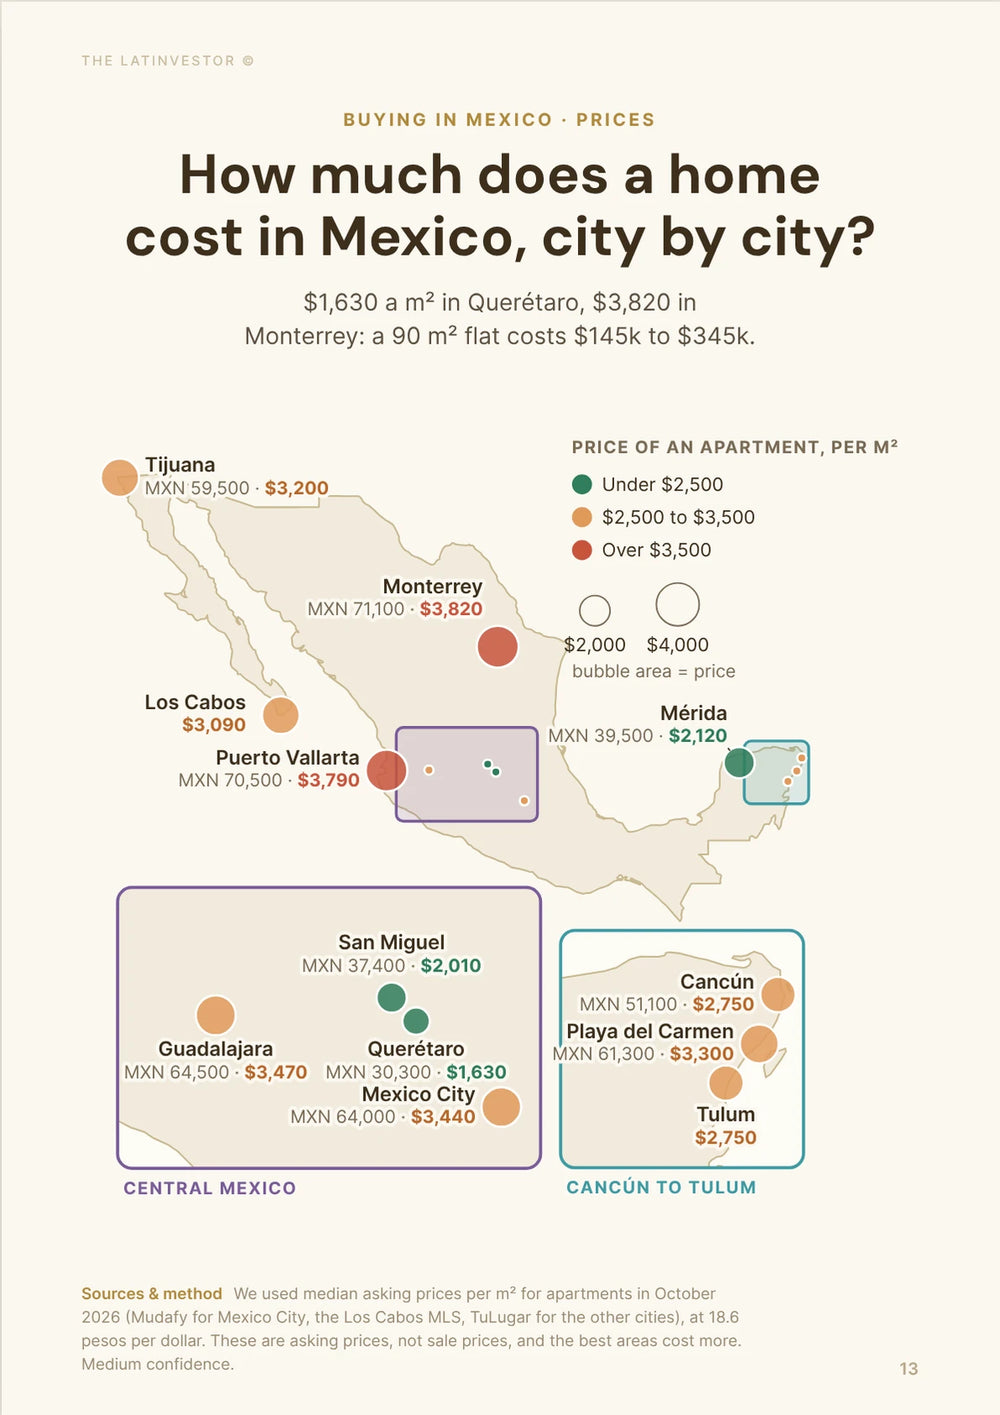
Tulum is the clearest case: sales roughly halved between 2023 and 2025 and nightly rates fell 23.6% in a year. Benito Juárez (Cancún), Solidaridad (Playa del Carmen) and Los Cabos almost doubled in value in the five years to the end of 2025, and Cancún's average gross rental yield is only 4.6%, against 5.79% nationally.
Rules are tightening too. Mexico City has written a 50% cap on short-term rental nights into law, even if most of it was still blocked in court in October 2026. A property that only works as an Airbnb is a riskier bet than it was.
What to check before signing: recent sale prices of similar units (not asking prices), how many units in the same building are for sale or rent, the rent you'd get on a 12-month lease, and whether the deal still works if prices stop rising. Buying finished rather than off-plan in a resort town also cuts the risk.
What could make Mexican property prices stop rising?
A national downturn would probably need weaker jobs and investment at the same time as affordability gets worse.
Affordability is already the main limit. Prices rising 7% to 8% a year with mortgages above 10% can't last forever unless incomes rise too.
The economy could add the second hit. GDP grew just 1.9% year over year in the second quarter of 2026. Monterrey, Tijuana and Guadalajara depend on factory jobs and investment, and a long industrial slowdown would eventually reach housing.
More supply could cool prices for a healthier reason. Hundreds of thousands of public homes are under construction and new-home inventory is already rising, which could slow growth without a crash.
None of these has turned the trend yet: the latest SHF data still show all 32 states rising.
So, is Mexico's property market still growing?
Yes, but the boom has matured, and buyers shouldn't assume every part of the country will keep rising at the same pace.
The national SHF index is up 7.9%, well ahead of 3.45% inflation. Guadalajara, Tijuana and several coastal, border and manufacturing states are still posting strong gains, and even the weakest states are positive.
At the same time, growth has cooled from 10.9% in 2023, mortgages still cost above 10%, lending is flat and new-home inventory is building up.
The shortage explains the contradiction: millions of households need homes the market can't build at prices they can pay, so prices rise without a lending boom.
In short: a growing but fragmented market, where the city, the price segment and the building matter much more than the national headline.
Our methodology
This article checks whether Mexico's property market is still growing by looking at more than prices: inflation, sales and lending activity, new supply, mortgage costs, housing need, regional differences and price segments.
For prices, we use the Sociedad Hipotecaria Federal (SHF) index, the official benchmark. It covers homes bought with a mortgage, so it gives one consistent view by state, metro area and housing type, but it doesn't capture cash purchases, which are common in resort areas. State and metro growth figures are first-half 2026 averages; average and median values are from the second quarter of 2026.
For activity and supply, we use SHF appraisal counts, BBVA Research data on mortgage lending and new-housing inventory, and Registro Único de Vivienda registrations. For costs and context, we use INEGI inflation, Banco de México mortgage rates and policy decisions, SEDATU and CONAVI housing-need figures, SEDATU's Vivienda para el Bienestar reports, Economy Ministry investment data, and El Economista and AirDNA for Tulum.
We checked these figures in October 2026. Conversions use about 18.6 pesos per US dollar and 20.9 pesos per euro.
Limits: a state index doesn't tell you how one city, neighborhood or building is doing, appraisals and mortgages are only a proxy for sales, and listing prices are not sale prices.
Key sources used for this analysis include SHF housing price index, Q2 2026, SHF housing price index, Q1 2026, SHF housing price index, 2025, IIEG summary of the SHF Q2 2026 index, Milenio on 2025 prices and appraisals, INEGI consumer prices, September 2026, BBVA Research, Situación Inmobiliaria H2 2026, BBVA Research, Situación Inmobiliaria H1 2026, Banco de México quarterly report Q1 2026, Banco de México mortgage rate quotes, Banco de México monetary-policy decisions, Crónica on ABM mortgage rates, El Financiero on the Citi expectations survey, Calcu.mx historical exchange rates, UnoTV on the peso's October fall, BBVA Research, Situación México September 2026, Registro Único de Vivienda, SNIIV housing registrations, SEDATU/CONAVI housing deficit 2025, SEDATU Programa Nacional de Vivienda 2026–2030, SEDATU on Vivienda para el Bienestar, Diario Oficial on Bienestar home prices, Economy Ministry on H1 2026 foreign investment, México, ¿cómo vamos? on Q2 2026 GDP, El Economista on Tulum oversupply, AirDNA Tulum, Global Property Guide price history, Global Property Guide rental yields and Excélsior on Mexico City's 50% limit.