
Summary
Yes. Prices in Mexico are still more likely to rise than fall: the official SHF index was up 7.3% a year in the second quarter of 2026. But the next phase looks slower and much more uneven than the boom years.
The cooling is real. National growth dropped from 8.6% in the first quarter of 2026 to 7.3% in the second, and Guadalajara, Monterrey and the Valley of Mexico all slowed too.
The rise has lasted a long time. Prices grew 8.9% in 2022, 10.9% in 2023, 9.2% in 2024 and 8.7% in 2025, about 43% in four years before counting 2026.
The typical financed home went from MXN 893,000 in 2022 to about MXN 1.30 million (about US$69,900) in 2026, a 46% jump.
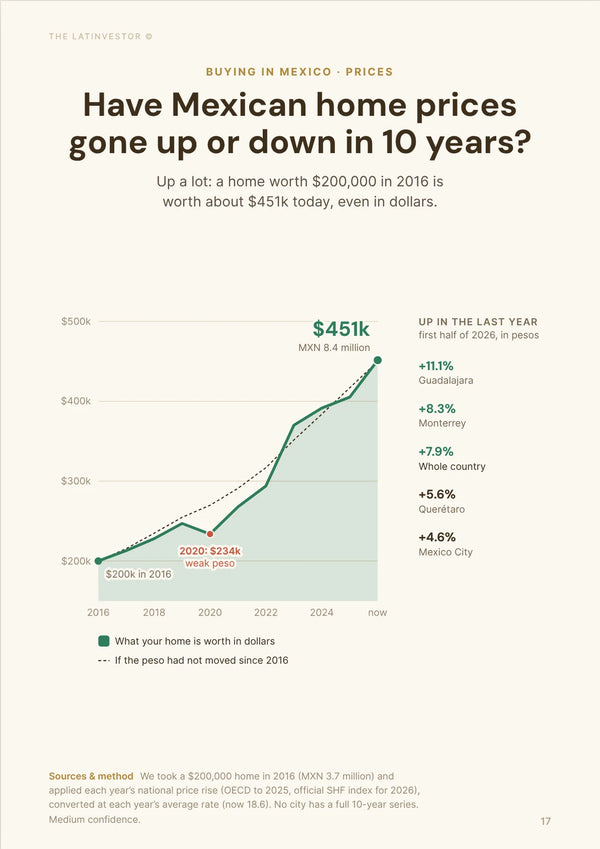
One national number hides a lot. Guadalajara rose 11.1% in the first half of 2026, the Valley of Mexico only 4.6%.
Nearshoring helps Monterrey and Tijuana, but it doesn't explain everything: Guadalajara and Puebla-Tlaxcala are rising just as fast without the same factory story.
Supply isn't catching up where people want to live. Building costs rose 5.79% a year by July 2026, and resale homes keep getting pricier too.
Credit is the brake that never came off. New mortgages still cost around 10% to 11%, and BBVA counted only 0.3% more home loans in the first half of 2026 than a year earlier.
Don't count on cheaper loans soon. Banxico's rate is at 6.50%, and a Citi survey from October 2026 expects no change in 2026 or 2027.
Affordability is the main reason to expect slower growth. A mortgage on the median home would eat roughly 42% of an average household's income.
Cheaper homes are rising fastest: 10% in the first half of 2026, against 6.7% for middle and upper-end homes.
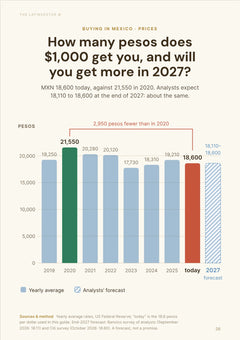
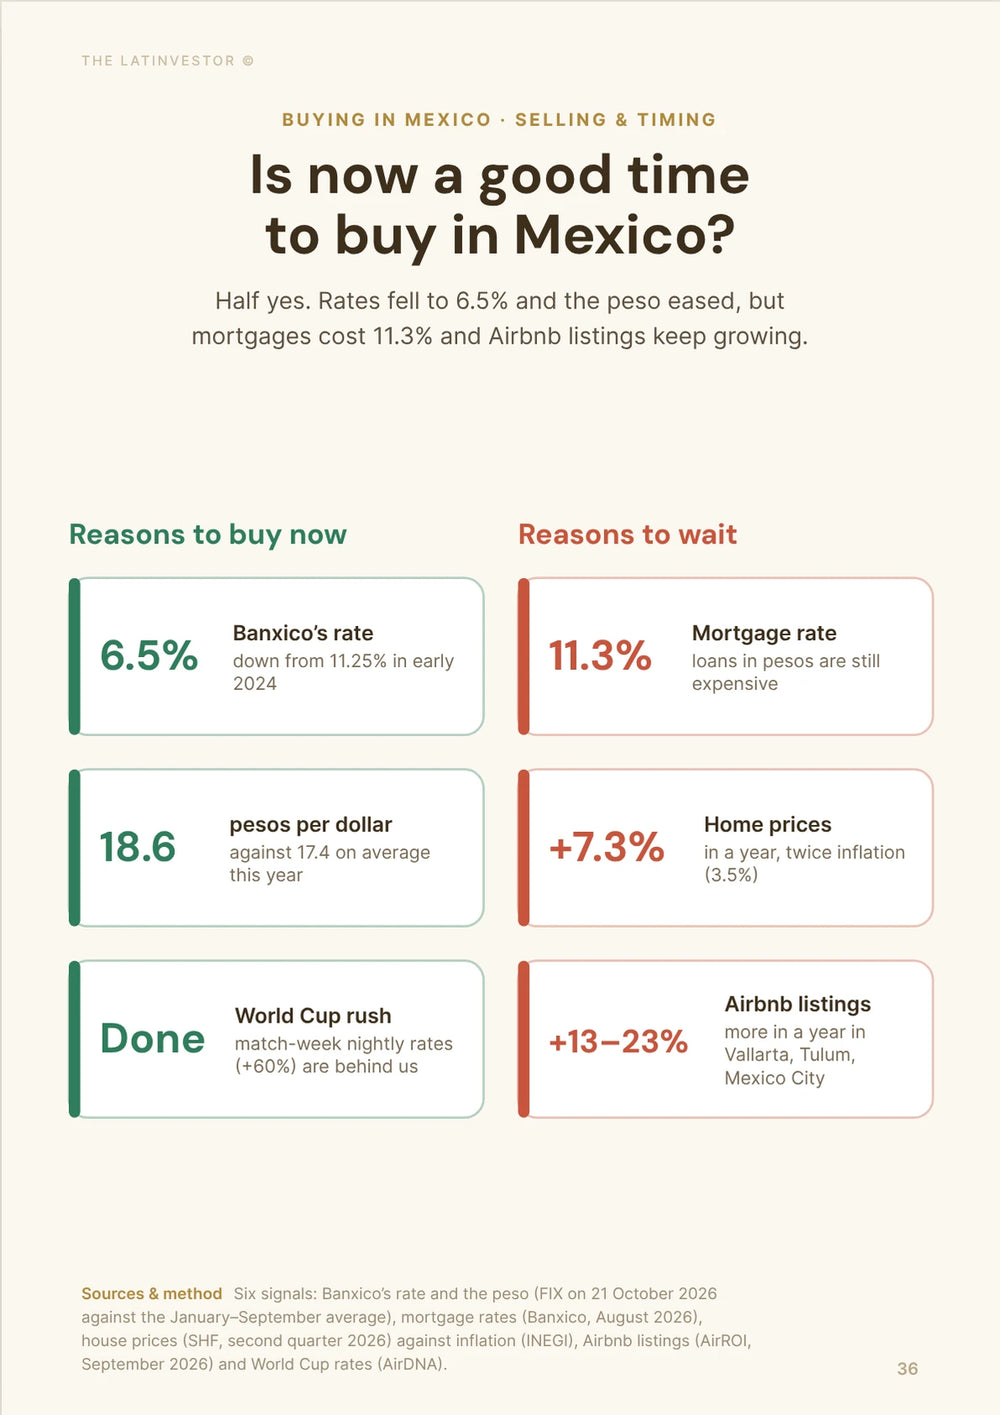
For dollar buyers, the exchange rate matters as much as the price trend. The peso went from just under 17 per dollar in early September to about 18.6 in late October, and most forecasts see it a bit stronger by the end of 2026.
Our base case is 5% to 8% a year nationally, with the strong cities staying ahead. A national price drop would need job losses, credit stress and forced sales that Mexico isn't showing right now.

Is Mexico’s housing market still rising today?
Yes. Prices in Mexico are still clearly rising, but the latest SHF data show the pace is cooling.
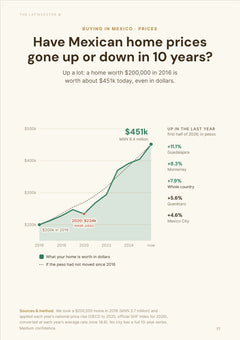
The national housing-price index rose 7.3% year over year in the second quarter of 2026, and 7.9% over the first half. That's slower than the 8.6% of the first quarter, but still a strong increase for a whole country.
Look at the previous four years. SHF recorded national price growth of 8.9% in 2022, 10.9% in 2023, 9.2% in 2024 and 8.7% in 2025. Compounded, that's roughly 43% before counting the rise in 2026.
Homes are also still beating consumer prices by a wide margin. Inflation was about 3.5% in September 2026, less than half the rate of home-price growth.
So far, Mexico looks like a market coming down from unusually fast growth, not one heading for a price drop.
| Period | SHF housing-price growth | Broad reading |
|---|---|---|
| 2022 | 8.9% | Strong rise |
| 2023 | 10.9% | Peak recent growth |
| 2024 | 9.2% | Still very strong |
| 2025 | 8.7% | Moderate slowdown |
| H1 2026 | 7.9% | Cooling, but still high |
| Q2 2026 (year over year) | 7.3% | Slowest pace in years |
Are Mexican property prices starting to slow down?
Yes. Prices are slowing now, and it shows in the big cities too, not only in the national number.
National growth fell from 8.6% in the first quarter of 2026 to 7.3% in the second. Over the same months, Guadalajara went from 12.3% to about 10.0%, Monterrey slowed to 7.6% in the second quarter after 8.3% over the half year, and the Valley of Mexico dropped to 4.2%.
Even Guadalajara, the hottest big market, is cooling. It's still rising faster than everyone else, just not at the same speed as a year ago.
The difference that matters is slowing versus stalling. A market moving from around 9% a year toward 7% is slowing. We'd need to see growth heading toward zero, or negative for several quarters, before calling it weak.
Has Mexico’s property boom lasted long enough to be more than a temporary spike?
Yes. The boom has lasted long enough that it looks like a lasting repricing, not a short post-pandemic jump.
National prices rose close to or above 9% in every full year from 2022 through 2025. One temporary factor can't explain that.
The mix of sales makes it even clearer. Used homes were roughly 60% of mortgage-backed transactions in 2022, 60.5% in 2023, 62.8% in 2024 and 63.8% in the first nine months of 2025. Resale prices still rose almost as fast as new-build prices.
The cheap end is under the most pressure. In the first half of 2026, SHF’s economic-social category rose 10%, against 6.7% for middle and residential housing. So this isn't mainly a story of wealthy foreigners buying premium homes.
It's mostly domestic: not enough suitable housing where people need to live, while building costs, land and expensive credit keep supply from catching up.
 Mexico Property Market
This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
How expensive has the typical Mexican home become?
Much more expensive in a short time: the median home financed through a mortgage went from MXN 893,000 in 2022 to about MXN 1.30 million (about US$69,900) in the second quarter of 2026.
That's a rise of roughly 46% in less than four and a half years.
The median reached MXN 951,000 in 2023, MXN 1.07 million in 2024 and MXN 1.21 million in 2025 before getting close to MXN 1.30 million in 2026.
The average is much higher because expensive homes pull it up: about MXN 1.54 million in 2022, 1.62 million in 2023, 1.74 million in 2024, 1.86 million in 2025 and MXN 1.96 million (about US$105,000) in 2026.
That gap is a reminder that one national “average home price” can mislead. A small number of expensive homes skews it, and Mexico has very different markets inside one index.
| Period | Average home value | Median home value | Median change from 2022 |
|---|---|---|---|
| 2022 | MXN 1.535m | MXN 893k | — |
| 2023 | MXN 1.617m | MXN 951k | +6.5% |
| 2024 | MXN 1.736m | MXN 1.070m | +19.8% |
| 2025 | MXN 1.864m | MXN 1.209m | +35.4% |
| Q2 2026 | MXN 1.960m | MXN 1.300m | +45.5% |
Are property prices rising everywhere in Mexico?
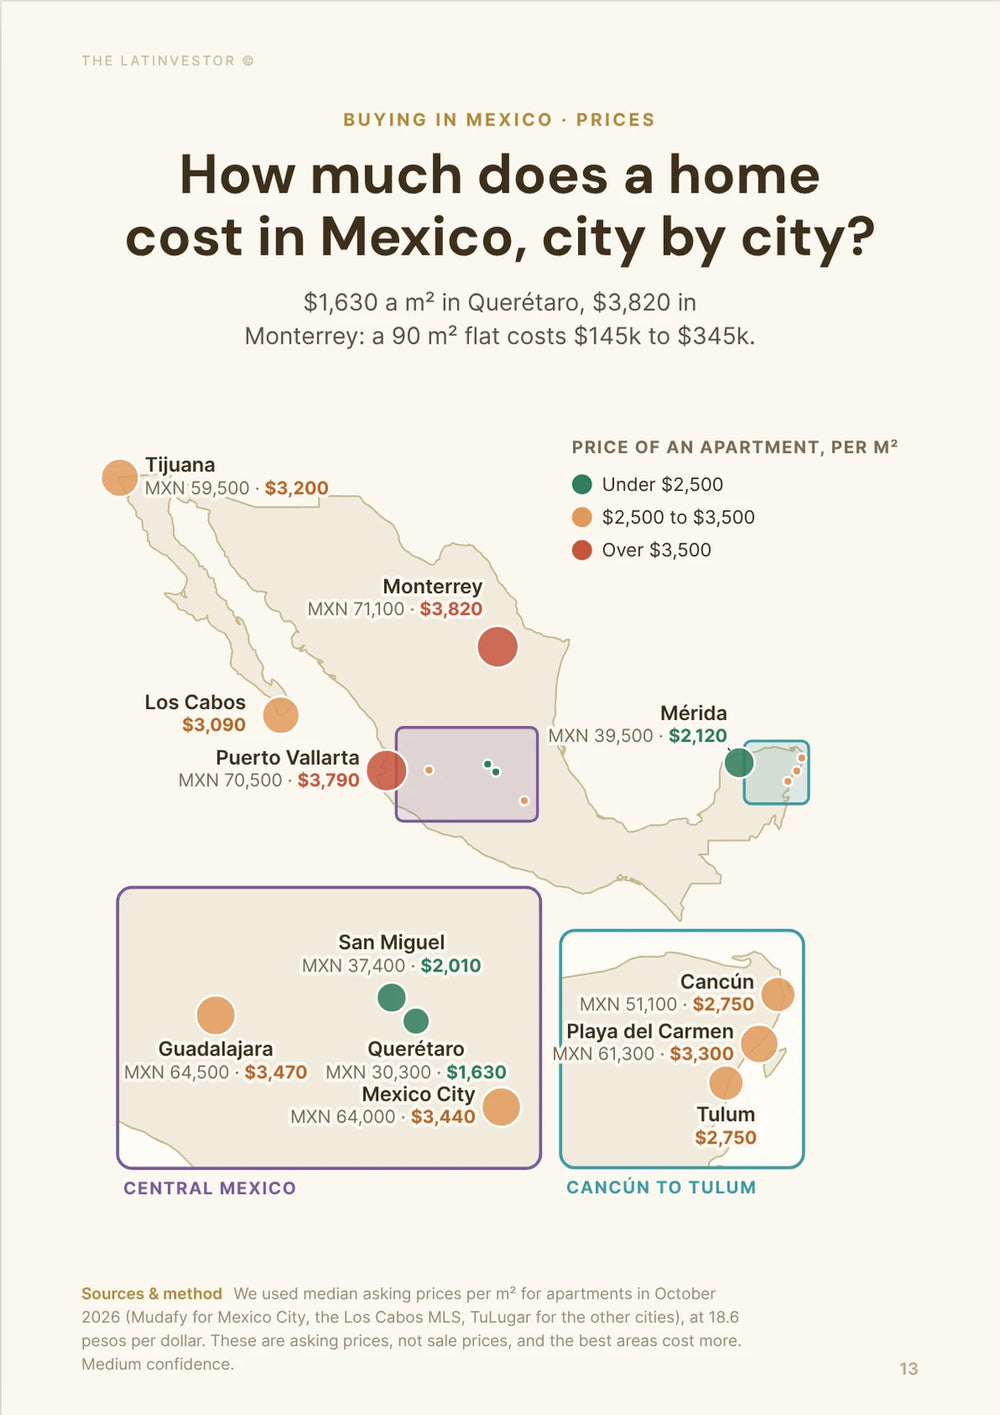
No. Prices are rising in most of Mexico, but the gap between the fastest and slowest big cities is now huge.
In the first half of 2026, Guadalajara led with 11.1%. Tijuana reached 9.7%, Puebla-Tlaxcala 8.5% and Monterrey 8.3%.
Querétaro was much slower at 5.6%, Toluca at 5.1% and the Valley of Mexico at only 4.6%. Guadalajara was rising more than twice as fast as the Mexico City area.
This split has been building for years. Tijuana rose 12.8% in 2022, 14% in 2023 and 12.7% in 2024 before slowing. Monterrey did 9.1%, 11.3% and 10.9% over the same three years.
The Valley of Mexico was much softer: 7.2% in 2022, 9.6% in 2023, 6.6% in 2024, 5.1% in 2025 and 4.6% in the first half of 2026.
So one national forecast is less and less useful. Mexico behaves like several markets moving at different speeds.
| Metropolitan area | 2023 | 2024 | 2025 | H1 2026 |
|---|---|---|---|---|
| Guadalajara | 11.5% | 9.4% | 11.3% | 11.1% |
| Tijuana | 14.0% | 12.7% | 10.6% | 9.7% |
| Monterrey | 11.3% | 10.9% | 9.4% | 8.3% |
| Puebla–Tlaxcala | 7.1% | 11.7% | 8.7% | 8.5% |
| León | 9.2% | 11.1% | 10.1% | 7.9% |
| Querétaro | 13.6% | 9.0% | 7.2% | 5.6% |
| Toluca | 6.9% | 7.7% | 4.6% | 5.1% |
| Valley of Mexico | 9.6% | 6.6% | 5.1% | 4.6% |
 70+pages
Is Guadalajara’s price boom finally cooling?
A little, but it's still the fastest big market in Mexico. SHF had Guadalajara at 12.3% in the first quarter of 2026 and about 10.0% in the second, for 11.1% over the half year.
The streak is what stands out: 11.5% in 2023, 9.4% in 2024, 11.3% in 2025. Several years around double digits means buyers keep competing for a limited amount of good housing.
The city has a broad job base (tech, electronics, manufacturing, services), so demand doesn't depend on tourists or second-home buyers.
Guadalajara keeps growing outward, but new homes on the edge don't fix the shortage in established neighborhoods or near the main job areas. That's why lots of construction hasn't flattened prices.
If you're buying there now, don't price in another 11% a year. A slower pace closer to the national trend is the safer assumption.
Can Monterrey’s nearshoring boom keep pushing property prices higher?
Yes, but more slowly. Monterrey still has some of the strongest reasons for prices to rise, even though growth eased to about 7.6% a year in the second quarter of 2026.
Nuevo León received about $3.63 billion in foreign direct investment in 2025, according to Mexico’s Economy Ministry, up roughly 73% from the year before. Only Mexico City got more.
The Nuevo León government also reported around $5.63 billion of announced investment projects in the first seven months of 2026, with about 7,620 expected jobs.
Prices followed that cycle: 9.1% in 2022, 11.3% in 2023, 10.9% in 2024, 9.4% in 2025 and 8.3% in the first half of 2026.
New supply is also hard to add quickly. Long commutes, water problems, infrastructure bottlenecks and few neighborhoods close to the industrial corridors all push up the price of well-located homes.
Nearshoring should keep supporting prices as long as announced factories turn into real jobs. Watch jobs created and plants opened, not headline investment announcements.
Is nearshoring really driving property prices across Mexico?
Only partly. It helps several cities, but it can't explain the national boom on its own.
The link is strongest in Monterrey and Tijuana, where industrial investment and job growth meet tight housing supply. Both have posted above-average price growth for years.
Investment is still flowing in. Foreign direct investment hit a record $40.87 billion in 2025, up 10.8%, and the first half of 2026 set another record for a first half at about $34.97 billion.
But the housing map doesn't follow the investment map. Guadalajara is rising faster than Monterrey, and Puebla-Tlaxcala is also strong. Neither fits the usual nearshoring story.
And much of the FDI is booked in Mexico City because companies have their headquarters there, even when the factories and jobs are elsewhere. Raw FDI totals say less about local housing demand than they seem to.
Nearshoring is one force pushing some markets up. It's part of the explanation, not the whole of it.
Is Mexico building enough homes to slow property prices?
Probably not. Mexico is building more than it did recently, but it's still too little, and too often in the wrong places, to take the pressure off prices.
According to Infonavit data based on the Single Housing Registry, around 138,600 new homes were produced in 2025, about 8.2% more than in 2024.
The underlying need is far larger. SEDATU’s 2025 update puts about 8.33 million households, around 21%, in housing-deficit conditions. That includes overcrowding and poor-quality homes, so it doesn't mean Mexico is short 8.33 million houses for sale. It does show how big the problem is.
Building costs are moving the wrong way. INEGI’s producer-price data showed construction costs up 5.79% a year by July 2026, faster than general inflation.
New homes rose 8.3% and used homes 7.5% in the first half of 2026. Used homes still made up almost two-thirds of mortgage-backed sales in the first nine months of 2025.
So buyers aren't only squeezed by pricey new developments. Resale homes are getting more expensive too, which points to a shortage across the existing stock.
Location is the hardest part. Homes on cheap land far from jobs do little for buyers competing in central Guadalajara, Monterrey, Tijuana or Mexico City.
| Period | New housing price growth | Used housing price growth | Used share of transactions |
|---|---|---|---|
| 2022 | 9.9% | 8.1% | 60.0% |
| 2023 | 11.9% | 10.1% | 60.5% |
| 2024 | 9.6% | 8.9% | 62.8% |
| Jan–Sep 2025 | 8.4% | 8.7% | 63.8% |
| H1 2026 | 8.3% | 7.5% | Majority used |
 70+pages
Will high mortgage rates finally stop Mexico’s property market?
No, not so far. Expensive credit is the biggest brake on the market, but rates have been high for years and prices kept rising.
Banxico’s data show the average rate on new mortgages at 10.29% in October 2024, 10.15% in October 2025 and 10.13% in March 2026. Its average fixed-rate mortgage quote was 11.31% in August 2026, while the rate banks actually granted averaged 9.99% in June, according to the banking association ABM. In other words, flat for two years.
Meanwhile prices rose 9.2% in 2024, 8.7% in 2025 and 7.9% in the first half of 2026.
The market adjusted in other ways. Households bought smaller homes, put down bigger deposits, used Infonavit credit, pooled incomes or stayed out. Activity weakened before prices did.
That's what the mortgage numbers show now. BBVA counted only 0.3% more home loans in the first half of 2026 than a year earlier, and the amount lent fell 0.1% in real terms. Prices are rising on a market that isn't borrowing more.
Will Banxico rate cuts bring cheaper mortgages in 2027?
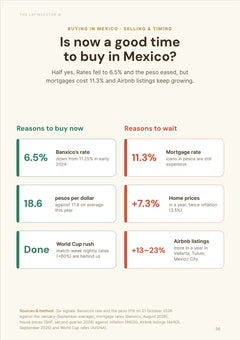
Probably not much. Banxico’s policy rate is at 6.50% in October 2026, far below its peak, yet mortgage rates barely moved. And a Citi survey of analysts published on October 20, 2026 expects no further change to that rate in 2026 or 2027.
Mortgage rates in Mexico depend on bank funding, long-term rates and credit risk, not only on Banxico. That's why the big cuts in the policy rate since 2024 left new mortgages stuck around 10%.
What to do with that: don't wait for cheap credit before buying. Run your numbers at today's rates, and if you take a loan, compare the total annual cost (CAT) across several banks rather than the headline rate. Foreign buyers who aren't resident usually go through cross-border lenders, which ask for bigger deposits, for example at least 35% down at MoXi/Global Mortgage.
The flip side is useful. When few people can borrow, cash buyers have more weight in a negotiation, especially on resale homes that have been listed for a while.
Can ordinary Mexican households still afford to buy property?
It's getting hard, and that's the clearest reason to expect slower price growth.
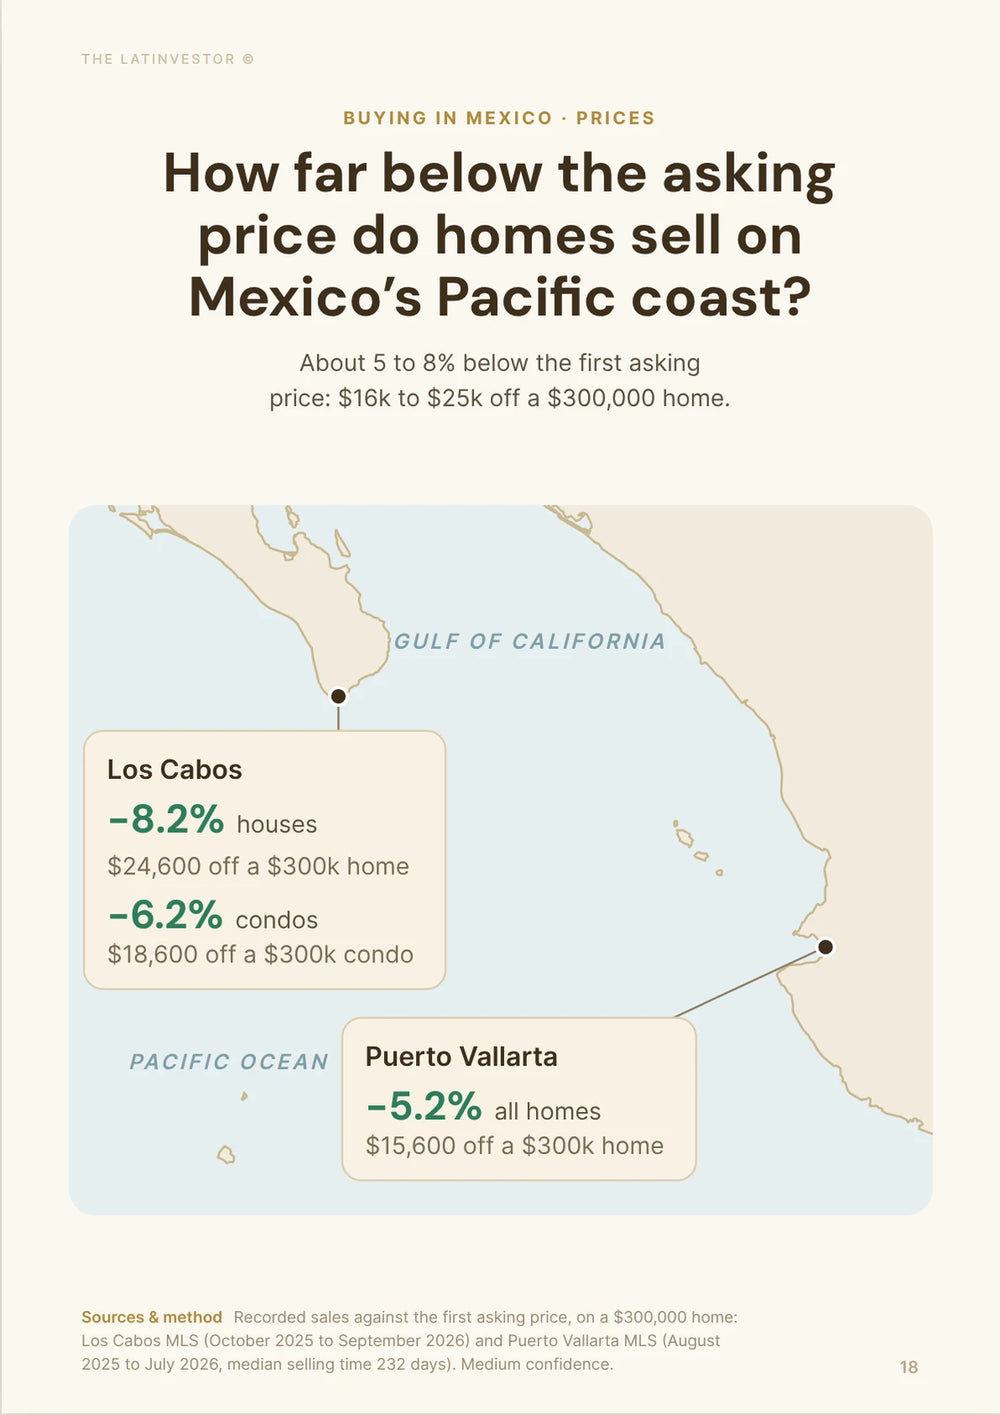
INEGI’s latest household survey put average current household income at MXN 25,955 a month in 2024. The median mortgage-backed home was already about MXN 1.30 million in 2026.
A simple example: buy that MXN 1.30 million home with 20% down and you borrow about MXN 1.04 million.
At 11.31%, Banxico’s recent average mortgage quote, over 20 years, the monthly payment is about MXN 11,000 (about US$591). That's roughly 42% of the average household’s income, before insurance, maintenance and taxes.
The comparison isn't perfect: average households and mortgage buyers aren't the same people, and incomes have moved since 2024. But the order of magnitude is hard to ignore.
The pressure shows at the cheap end. Economic-social housing rose 10% in the first half of 2026, against 6.7% for middle and residential homes. When people are priced out of bigger homes, they all compete for the few they can still afford.
| Illustrative affordability test | Approximate amount |
|---|---|
| Median home valuation (Q2 2026) | MXN 1.300m |
| 20% down payment | MXN 260k |
| Mortgage principal | MXN 1.040m |
| Illustrative mortgage rate | 11.31% |
| 20-year monthly payment | ≈ MXN 11,000 |
| 2024 average current household income | MXN 25,955/month |
| Mortgage payment / average income | ≈ 42% |
 70+pages
Could bad affordability actually make Mexican property prices fall?
In some places, maybe. But it's much more likely to slow prices than to push the whole country into a decline.
Housing markets can absorb weaker demand for a long time without big price cuts. Owners wait instead of selling. Developers delay projects. Buyers move farther out, buy smaller or keep renting.
Mexico is already doing exactly that. Mortgage lending was flat in the first half of 2026 (BBVA counted 0.3% more loans and 0.1% less money lent in real terms), while prices still rose 7.9%.
That's a market where affordability pushes buyers out before sellers are forced to slash prices.
For a national decline, several things would have to go wrong together: jobs, mortgage defaults, forced sales and unsold inventory. That isn't happening on a big enough scale to make a national fall our base case.
Are cheaper Mexican homes rising faster than expensive ones?
Yes. Cheaper homes are rising faster than middle and upper-end ones, which makes the affordability problem worse.
SHF’s economic-social index rose 10% in the first half of 2026, against 6.7% for middle and residential housing.
The gap was even wider in 2025, at about 11% versus 7.4%.
It has been building for a while. Economic-social housing rose 10.7% in 2024, against 8.4% for middle-residential. In 2023 the two were close, at 10.7% and 11%.
Pressure is moving down the ladder. Households squeezed by high rates and past price rises compete for cheaper homes, while developers struggle to build low-cost housing profitably as serviced land, materials and labor get more expensive.
The cheap end of the market may now have the worst shortage of all.
Can government housing construction bring Mexican property prices down?
It can ease pressure at the cheap end, but not bring national prices down.
The program is big on paper. By September 2026, SEDATU reported about 667,000 homes contracted under Vivienda para el Bienestar, 277,000 under construction and 89,000 assigned to families. Most homes sell for around MXN 600,000, and Infonavit raised the price ceiling from MXN 630,000 to MXN 862,000 (about US$46,300) on September 29, 2026, so even the top of the range sits about a third below the national median.
The hard part is building the right homes in the right places. A project on cheap land at the edge of town doesn't compete with an apartment near central Guadalajara or a house near a Monterrey industrial corridor. Buyers care about commute, water, power, schools and transport.
That's why national housing production can rise while the neighborhoods people want keep getting more expensive.
These homes could still make a real difference for economic-social housing, where prices are rising fastest, especially if they're close to jobs. But turning the whole national index around would need much more supply in many cities at once, and the program isn't there yet.
What would actually make property prices fall across Mexico?
A national price fall would probably need a serious economic or credit shock.
Jobs come first. Markets weaken when households lose income and owners have to sell. Formal job growth has slowed, but IMSS-registered permanent jobs were still growing around 1.4% a year in mid-2026.
Credit stress is the second warning sign. BBVA has flagged rising Infonavit arrears, especially among lower-income borrowers. If that turned into a wave of forced sales, prices would feel it.
Oversupply is the third route, and nationally Mexico still has the opposite problem: millions of households in poor housing, high building costs and the cheapest homes rising fastest.
A sharp drop in industrial investment could hurt Monterrey or Tijuana. But FDI set a record in 2025 and another first-half record in 2026, so that's a risk, not what's happening today.
 70+pages
Do rising prices in pesos mean you pay more in dollars?
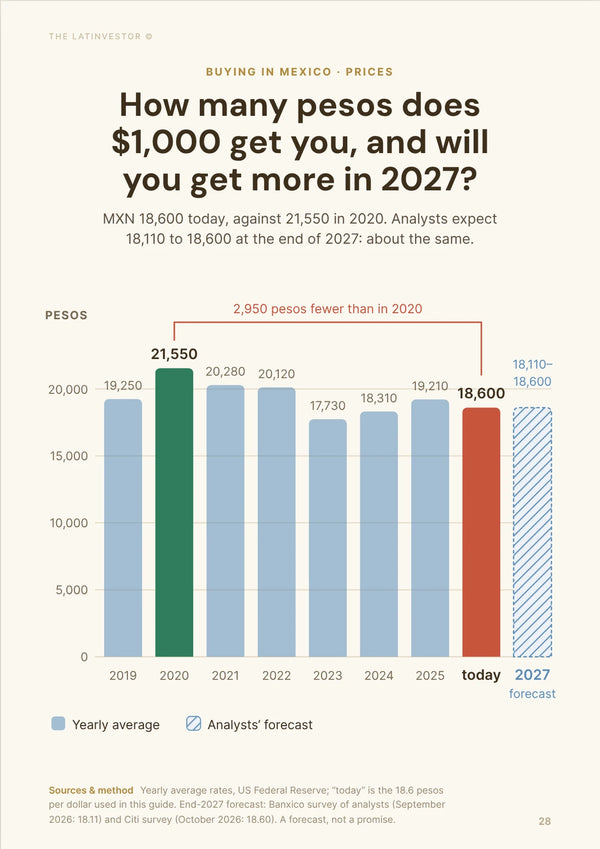
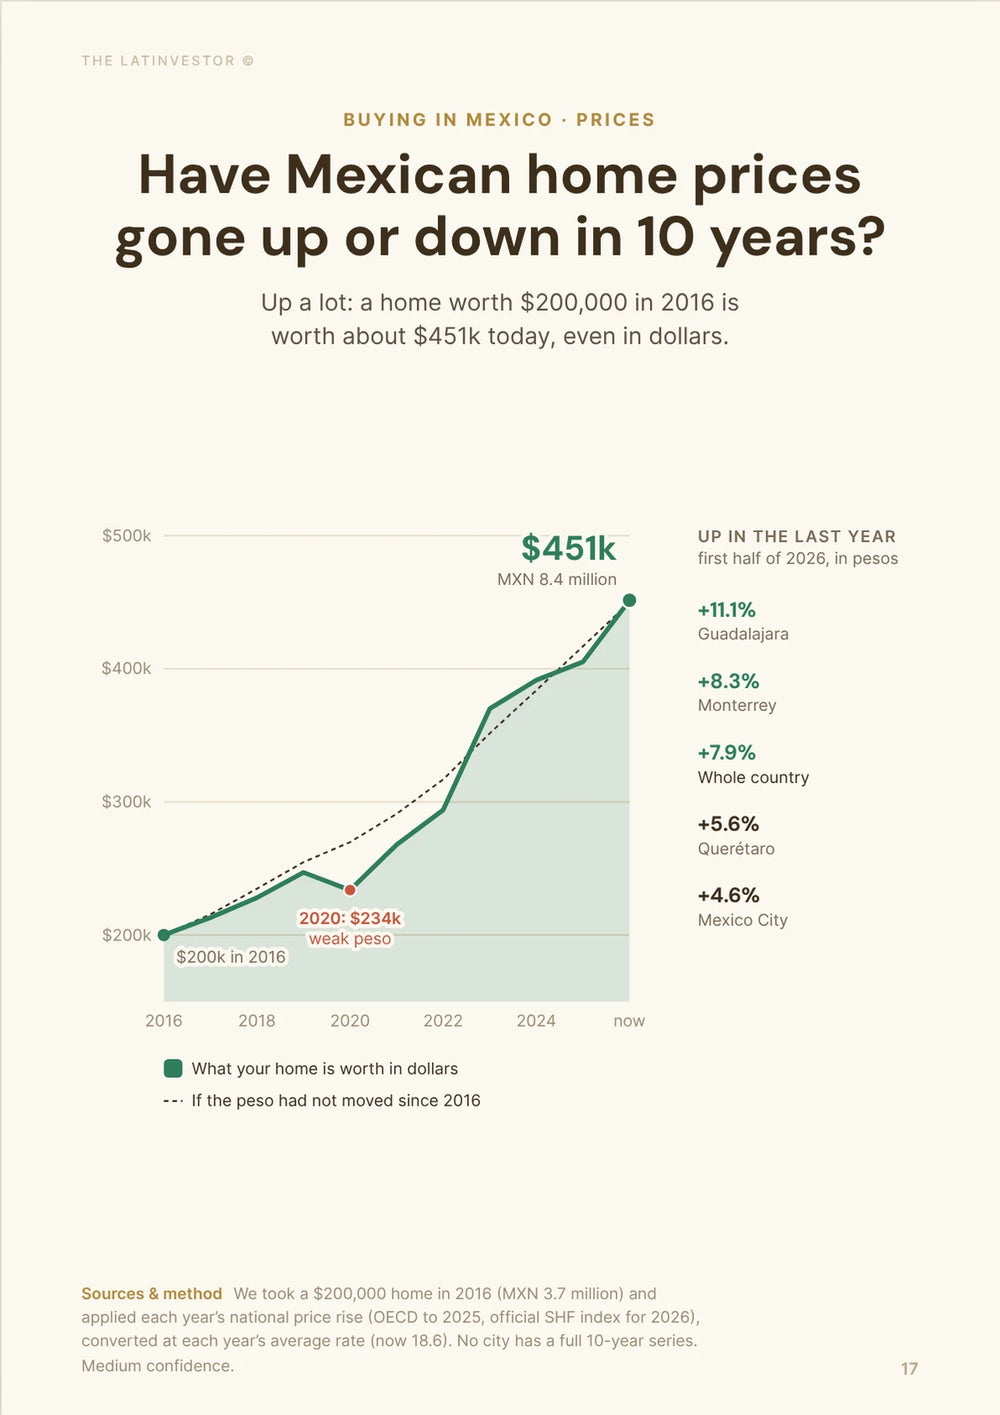
Yes, and over the past year the exchange rate made it worse, not better. The peso averaged about 19.2 per dollar in 2025. Today it's about 18.6. Add the 7.3% price rise in pesos and the same type of home costs roughly 11% more in dollars than a year ago.
The recent move went the other way, though. The peso was just under 17 per dollar in early September 2026 and weakened to about 18.6 by late October, so a dollar buyer gets more pesos now than two months ago.
Forecasts don't promise that lasts. BBVA sees about 17.3 pesos per dollar at the end of 2026 and 17.7 at the end of 2027; Banxico’s survey of private analysts says about 17.6 for end-2026, and Citi’s survey about 18.2 and 18.6. If the peso goes back to 17.3, a peso-priced home costs about 7.5% more in dollars without anyone raising the price.
What to do: set your budget in pesos, keep a 5% to 8% currency buffer, and once you've signed a promise to buy, convert the money in a few chunks rather than all at once on closing day. If you're paying a developer in installments over 12 to 24 months, ask whether the price is fixed in pesos or in dollars, and pick the one you can live with if the peso strengthens.
How fast are Mexican property prices likely to rise from here?
Prices are likely to keep rising, but a slower national pace of roughly 5% to 8% looks more realistic now than another long run above 10%.
The latest figure of 7.3% already points that way. It's below the 8.6% of the first quarter and below every full year from 2022 to 2025.
Affordability is doing the damage. Mortgage rates are stuck around 10% to 11%, the median financed home is near MXN 1.30 million and mortgage lending has stalled.
At the same time, what pushes prices up hasn't gone away. Building is expensive, affordable supply is tight, new and used homes are both gaining value, and the big job centers keep attracting investment.
The gap between cities should widen. Guadalajara, Monterrey, Tijuana and some industrial cities with tight supply can keep outperforming, while the Valley of Mexico and slower regional markets may settle into modest growth.
| Scenario | What would drive it | Approximate nominal direction | Our reading |
|---|---|---|---|
| Renewed boom | Mortgage rates fall clearly while supply stays tight | 9%+ | Possible in selected cities |
| Base case | Moderate growth, flat credit, persistent housing shortage | 5–8% | Most likely |
| Slow market | Weak growth and worsening affordability | 1–5% | Plausible in slower cities |
| National decline | Job losses, forced sales and broad credit stress | Below 0% | Unlikely for now |
 70+pages
So, are property prices in Mexico likely to rise?
Yes. Prices are still more likely to rise than fall, but growth should be slower and far more uneven than in the best recent years.
The numbers still lean up: 8.9% in 2022, 10.9% in 2023, 9.2% in 2024, 8.7% in 2025 and another 7.9% in the first half of 2026.
The shape of the market matters more than any one number. New and used homes are both getting pricier. Cheap homes are rising fastest. Building is expensive. Several industrial and supply-starved cities still post high single-digit or double-digit growth.
Affordability is what stops us from expecting another easy 10% a year. Mortgage rates around 10% to 11%, higher prices and flat lending already limit how many households can buy.
So far that pressure shows up as flat lending and slower growth, not as price cuts.
Our base case: prices keep rising, probably in the mid-to-high single digits nationally, and the gap between strong and weak cities matters more every year. For a foreign buyer, the exchange rate can move your real cost as much as the price trend.
A new national boom is getting harder to justify. A national crash is even less convincing. The likely outcome is a slower market where the housing shortage keeps pushing prices up, just not as fast or as evenly as before.
Our methodology
This article estimates whether home prices in Mexico are likely to keep rising, and how fast. We broke the question into things we can actually measure: recent price growth, how long it has lasted, gaps between cities, housing supply, building costs, mortgage rates and lending, affordability, jobs, investment, the exchange rate and what could push prices down.
The official SHF housing-price index is the backbone, because it tracks national prices, metropolitan areas, new and used homes, price segments and median and average values the same way over time. We compare the latest quarters with several past years so one strong or weak quarter isn't mistaken for a change in direction. Mortgage rates come from Banco de México (new loans and its average fixed-rate quote), lending volumes from BBVA Research, incomes from INEGI and supply figures from SEDATU, Infonavit and INEGI.
The affordability example is an illustration, not a claim about every household: the SHF median home value, 20% down, a 20-year loan at Banxico’s recent average mortgage quote, and INEGI’s latest household income figure. The 5% to 8% base case is our own judgment from all these signals; we found no 2026 or 2027 national price forecast confirmed by two independent sources.
We checked these figures in October 2026. Conversions use about 18.6 pesos per US dollar and 20.9 pesos per euro. Exchange-rate forecasts come from BBVA Research, Banxico’s survey of private analysts and Citi’s survey, and are forecasts, not promises.
Limits: the SHF index only covers homes bought with a mortgage, so cash-heavy markets such as beach towns are underrepresented; a housing-deficit estimate is not a count of homes missing from the market; and announced investment means less for housing than the jobs that actually appear.
Key sources used for this analysis include: SHF’s Q2 2026 housing-price index, IIEG Jalisco’s summary of the SHF Q2 2026 index, SHF’s Q1 2026 housing-price index, SHF’s full-year 2025 release, SHF’s Q3 2025 release, SHF’s full-year 2024 release, SHF’s full-year 2023 release, SHF’s full-year 2022 release, SHF’s historical datasets, Banco de México’s Q1 2026 report (new mortgage rates), Banco de México’s mortgage-rate quotes, Banco de México’s monetary-policy decisions, El Financiero on the October 2026 Citi survey, BBVA Research’s Mexico Real Estate Outlook, H2 2026, BBVA Research’s Mexico Outlook, September 2026, INEGI’s ENIGH 2024, INEGI’s September 2026 inflation release, INEGI’s producer price index, SEDATU/SNIIV housing-production data, SEDATU’s 2025 housing-deficit update, SEDATU on Vivienda para el Bienestar, the Economy Ministry’s 2025 FDI release, the Economy Ministry’s H1 2026 FDI release, the Nuevo León government on announced investment, IMSS formal-employment data, Calcu.mx historical peso-dollar averages, UnoTV on the peso in October 2026, Crónica on ABM mortgage rates and MoXi/Global Mortgage on cross-border loans.