


Summary
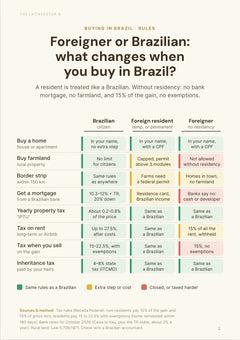
Yes. A foreigner can buy an urban apartment, house or plot in Brazil in their own name, with no visa and no approval. Budget about 4% to 6% on top of the price, so BRL 40,000 to BRL 60,000 on a BRL 1,000,000 home (about USD 7,920 to USD 11,900).
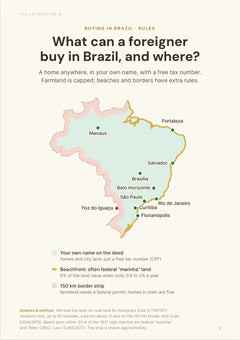
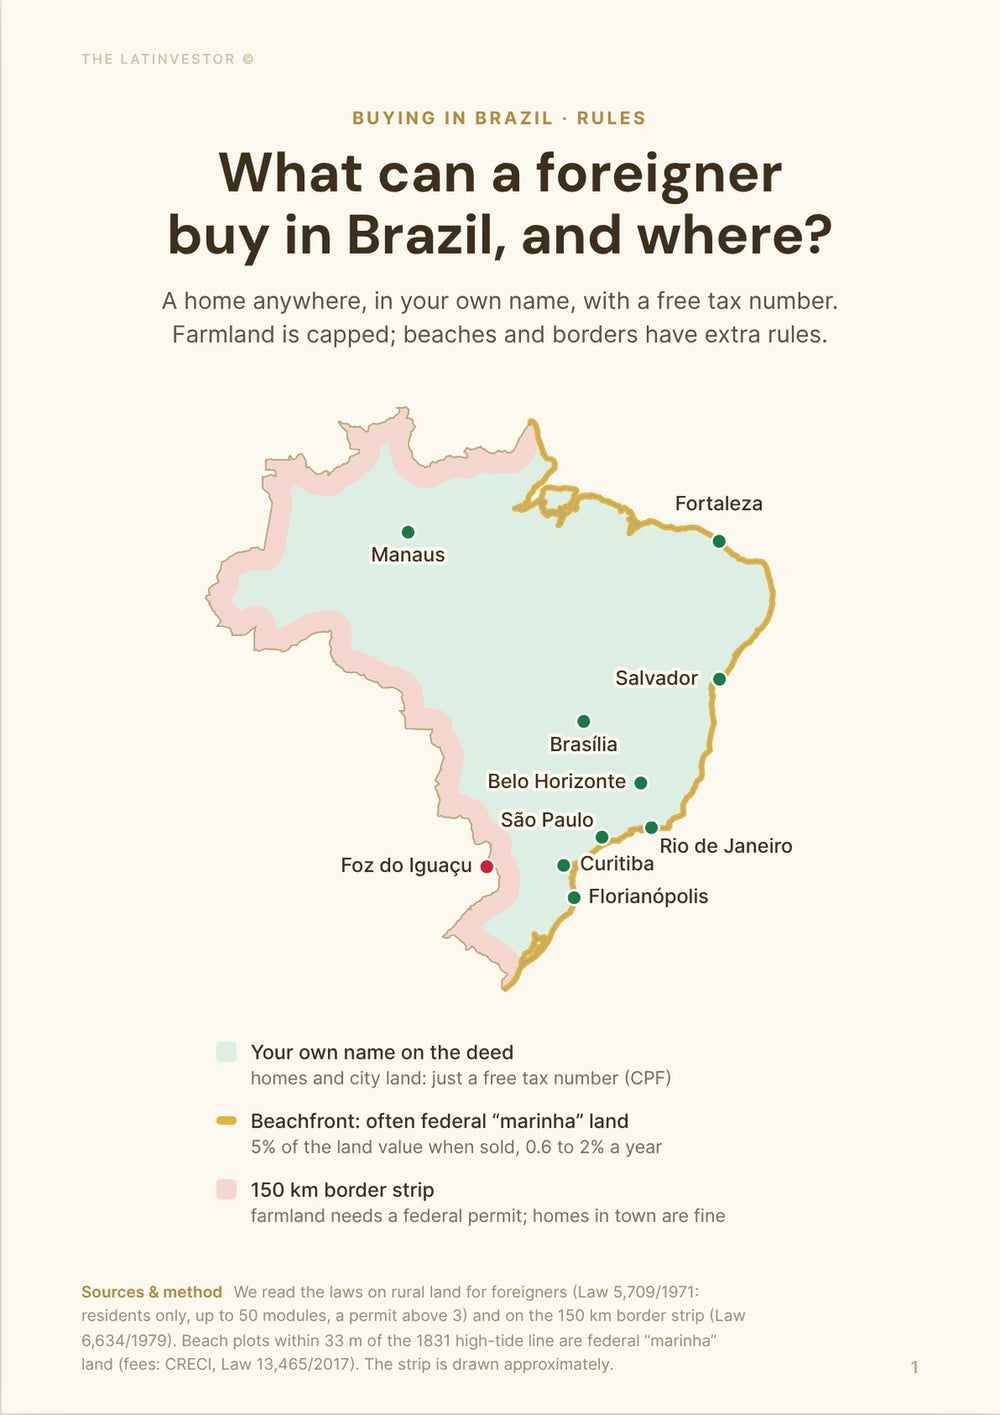
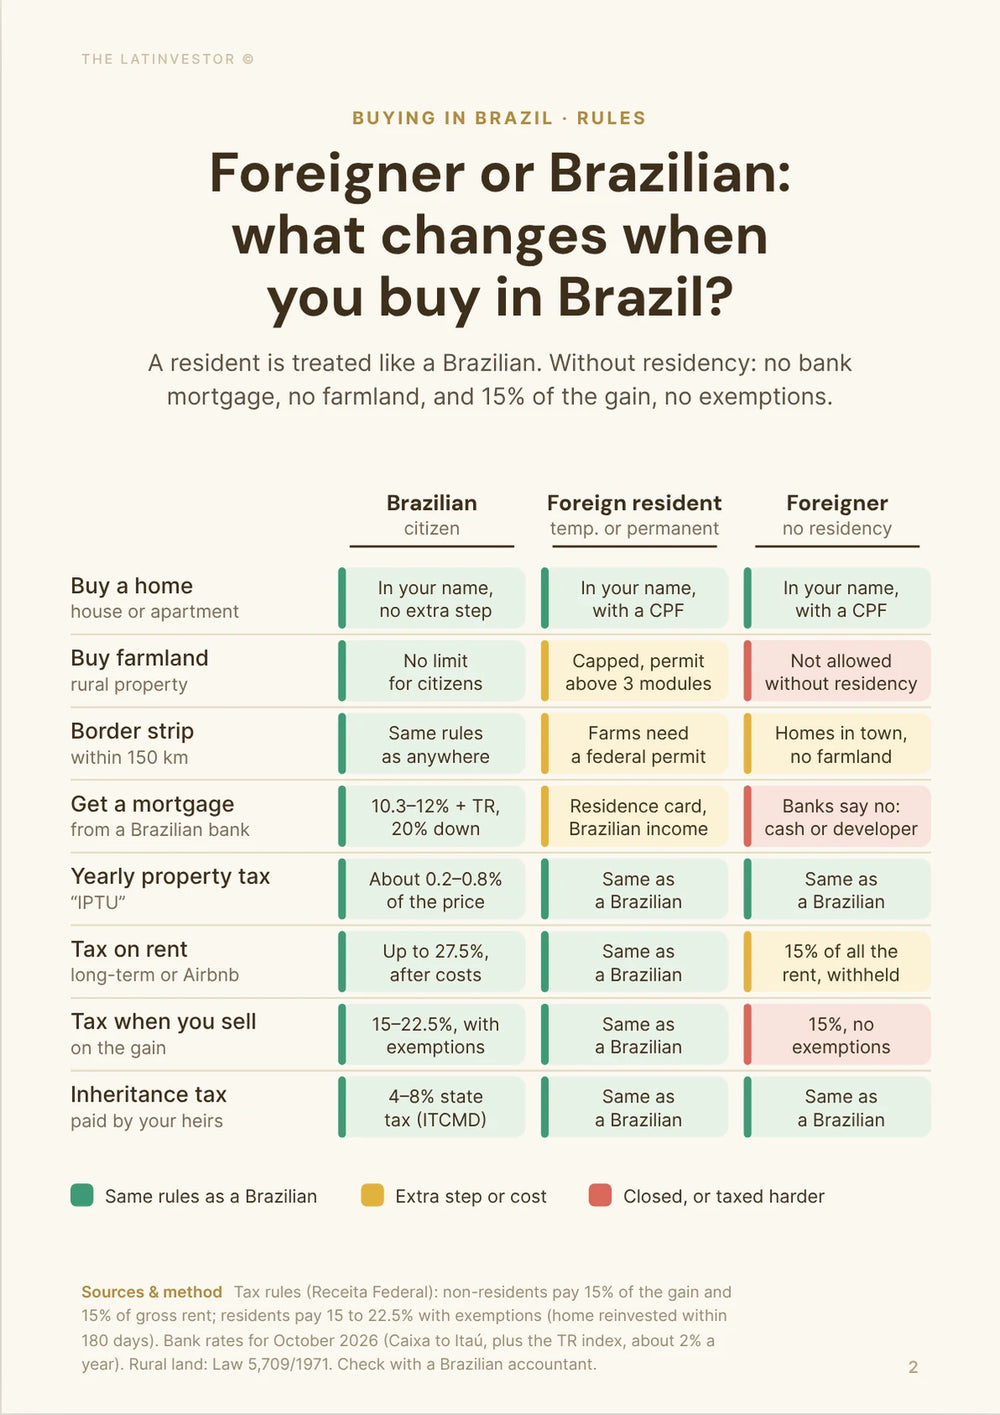
The limits are on rural land and on rural property in the 150 km border strip. A city apartment is not affected, even on the coast.
You need a CPF tax number. It's free, but from abroad a foreigner has to apply in person at a Brazilian consulate.
Buying doesn't give you residency. Investing BRL 1,000,000 (BRL 700,000 in the North and Northeast) lets you apply for a 4-year permit.
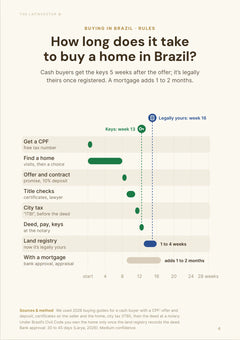
You own the property only when the deed is registered on the matrícula. Plan 30 to 90 days from accepted offer to registration; the registry itself has 5 working days for a plain purchase deed.
You can do it without flying in: the usual route is an apostilled power of attorney signed at home, because remote e-Notariado signing needs a Brazilian digital certificate. Forged powers of attorney are a live fraud: in July 2026, police investigated a BRL 4.5 million plot transferred away from a couple living in the US with a forged one.
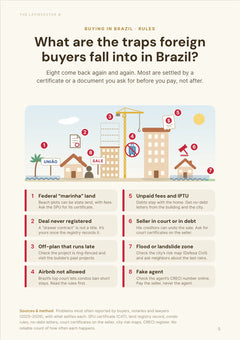
The checks are yours to do. Since 2025, registries can't refuse a deed over unpaid tax certificates, so pull the matrícula, the seller's court and tax certificates, and the condo and IPTU debt statements yourself.
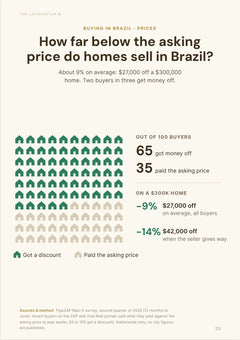
Don't pay the asking price. Sellers gave an average discount of 9% in the year to June 2026, and 14% when they gave one at all, and developers had 355,290 new units unsold in mid-2026.
Plan to pay cash. Banks usually require Brazilian nationality or permanent residency, and the Selic is at 13.75%. Those who qualify paid from 7.98% plus TR (Caixa) to about 11.9% plus TR (Itaú) in September 2026.
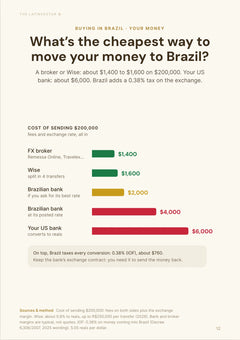
Money can come in without a Brazilian bank account, through an authorized exchange bank. Keep every exchange contract: you'll need them to send the sale money back out.
Once you own, IPTU runs from 0.3% to 1.4% of the city's assessed value, basic home insurance can cost under BRL 500 a year for an apartment, and 15% of your gross rent is withheld as a non-resident.
Bottom line: buying in Brazil is open and fairly cheap; the risk is in skipped checks and unregistered deals. Pay nothing until the matrícula has been checked, and don't stop until the deed is registered.


What can you buy, and when do you actually own it?
What property types can foreigners legally buy in Brazil right now?
Any urban home: apartments, condos, houses, townhouses, homes in gated communities, beach houses in an urban zone and urban plots. You buy them in your own name, with the same title as a Brazilian.
What matters is not the type of home but the land: urban or rural, inside the border strip or not, on federal coastal land or not, properly registered or not.
An apartment in São Paulo, Rio de Janeiro, Brasília, Belo Horizonte, Recife, Fortaleza, Florianópolis or Curitiba is the simple case. Sítios, chácaras, fazendas, island homes and countryside lots are where the rural-land, border and federal-land questions come up.
Can I own land in my own name in Brazil right now?
Urban land, yes, with a CPF and a deed registered at the local Registro de Imóveis.
Rural land is another matter: a first rural holding of up to 3 MEI (a local land unit) outside the border strip can skip INCRA approval, larger ones need it, and rural property in the 150 km border strip needs national-security clearance. We cover these limits in detail in our article on foreigners' property rights in Brazil.
The safe path for a home buyer is a registered urban property where the matrícula matches the seller, the land area and the city's IPTU record.
What other rules affect a foreign buyer in Brazil?
Fewer than people expect. There's no foreigner quota in apartment buildings, no list of banned cities and no surcharge: foreigners pay the same ITBI transfer tax as Brazilians.
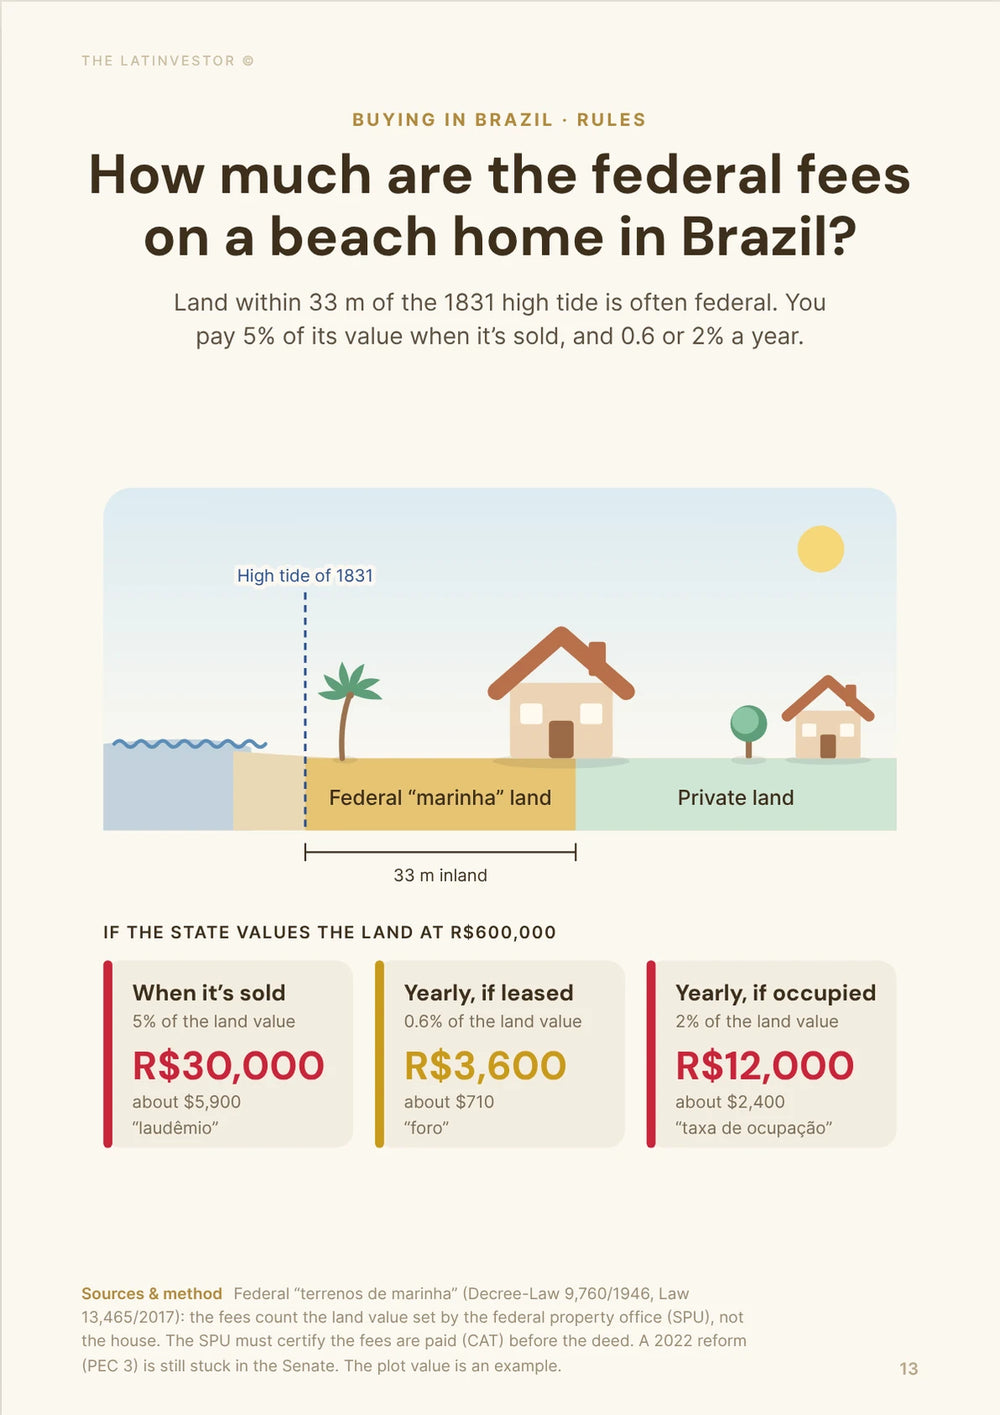
The practical rules are the CPF, a clean paper trail for the money you bring in, and, on the coast, checking whether the land is a terreno de marinha (federal coastal land), where a 5% laudêmio on the land value is due at each sale, usually paid by the seller.
Registries are more digital than before: you can order a matrícula online through the ONR system. That makes checks faster, not optional.
What's the biggest ownership mistake foreigners make in Brazil right now?
Thinking that a signed contract, a paid deposit or the keys make you the owner. Under the Civil Code, ownership passes only when the deed is registered on the matrícula.
Until then, the seller's creditors, a second buyer or someone living in the property can come before you. In April 2026 the STJ even ruled that a simple purchase receipt can support an adverse-possession claim (usucapião) by someone who has lived there for years.
The other classics: condo and IPTU debts that follow the unit, an old copy of the matrícula, a weak or forged power of attorney, and rural land sold as if it were urban.
 Buying in Brazil as a Foreigner
Do you need a visa or residency to buy?
Do I need a specific visa to buy property in Brazil right now?
No. Tourists and non-residents can buy urban property. What you need is a CPF and documents a notary will accept.
Foreigners living abroad can't use the online CPF form (it's for Brazilians). You book an appointment through the e-consular system and apply in person at the Brazilian consulate for your area. It's free, and the government gives no processing time, so start early. In Brazil, you can also get one at the Receita Federal or a partner outlet (about BRL 7).
The usual document set: passport, CPF, proof of address, marriage or divorce papers (the marriage regime matters for the deed), apostilles, sworn translations into Portuguese, and a power of attorney if you won't be there to sign.
Does buying property help me get residency and citizenship in Brazil?
It can get you residency, not citizenship. Under RN 36/2018, investing at least BRL 1,000,000 (about USD 198,000) in urban property, or BRL 700,000 (about USD 139,000) in the North and Northeast, with money brought from abroad, lets you apply for a 4-year residence permit.
Buying doesn't trigger it on its own: you apply, and the government says it decides within 180 days. The buying costs don't count toward the threshold, and the deed must show the full price, so say no to any suggestion to under-declare it.
Citizenship is a separate naturalization process, years later. Retirees have another route that has nothing to do with property: a pension of at least USD 2,000 a month.
Can I legally rent out property on my visa in Brazil right now?
Yes. Renting out is passive income, not work, so your visa doesn't matter and you don't need to live in Brazil. In practice you'll need a local property manager or someone with a power of attorney.
As a non-resident, 15% of the gross rent is withheld at source. If you become a Brazilian tax resident, rent goes into the monthly income tax system, at up to 27.5%.
For short stays, read the condo rules first. In May 2026 the STJ ruled that offering a unit on Airbnb in a purely residential condo needs a two-thirds vote of the owners, and in September 2026 it froze similar cases nationwide until it sets a binding rule.
 70+pages
How does buying in Brazil work, step by step?
What are the exact steps to buy property in Brazil right now?
1) Get your CPF. 2) Find an urban, registered property and pull a fresh matrícula. 3) Have a lawyer check the seller and the property (certificates, debts, condo). 4) Sign a purchase promise (compromisso de compra e venda), often with a deposit. 5) Send the money through an exchange bank. 6) Pay the ITBI. 7) Sign the public deed (escritura) at a notary. 8) File it at the Registro de Imóveis.
The purchase promise is what binds both sides. The registration is what makes you the owner.
From accepted offer to registration, 30 to 90 days is a realistic estimate for a cash purchase: faster when the papers are clean, slower with foreign documents, a power of attorney or a messy seller. The registry itself is quick: since Law 14,382/2022, it has 5 working days to register a plain purchase deed, or to send back a list of problems.
Don't pay the deposit (sinal) before step 3, and pay it only into an account in the name of the owner shown on the matrícula.
Is it mandatory to get a lawyer or a notary to buy a property in Brazil right now?
The notary, yes: above a low value threshold, the Civil Code requires a public deed. If you buy with a Brazilian bank loan, the bank's contract replaces it. A lawyer isn't mandatory, but a foreign buyer who skips one is taking a big risk.
The notary writes up the deed; it doesn't check whether the deal is a good one for you. That's the lawyer's job.
Ask for a fixed quote that covers: a fresh matrícula, the seller's court and tax certificates, condo and IPTU debt checks, a review of any power of attorney, the money trail, and follow-up until registration. Hire your own lawyer, not the agent's.
Can you buy without flying to Brazil?
Yes. The usual route is a public power of attorney (procuração) signed before a notary in your country, apostilled and given a sworn translation, or signed at a Brazilian consulate. Your representative then signs the deed and handles registration.
Signing the deed yourself online through e-Notariado is possible in theory, but every party needs a Brazilian digital certificate (e-Notariado or ICP-Brasil) and has to join a video call. São Paulo's 26th notary office tells foreigners abroad without a Brazilian digital ID or a signature card on file to use a public power of attorney instead.
Powers of attorney are also the favorite tool of fraudsters. In July 2026, police in Ipojuca (Pernambuco) investigated how a plot worth about BRL 4.5 million, owned by a couple living in the US, was transferred to a company with a forged one.
What to do: limit the power of attorney to one property and one deal, give it an end date, and ask the notary that issued it to confirm it before signing. Once you own, check your matrícula online from time to time.
 70+pages
What checks stop you from buying a problem property?
How do I verify title and ownership history in Brazil right now?
Order an updated matrícula (matrícula atualizada, less than 30 days old) from the registry office that covers the property, at the counter or online through the ONR system.
It shows the description of the property, the owner, past transfers, mortgages, liens, usufruct rights and court seizures. Compare the owner's name and ID with the seller's documents.
Go back at least far enough to cover the usucapião periods in the Civil Code (10 to 15 years), and further with family transfers, company sellers, powers of attorney or court cases.
Stop the deal if the matrícula, the seller, the property you visited, the parking spaces, the land area or the IPTU record don't match.
How do I confirm there are no liens in Brazil right now?
Get a fresh matrícula or a certidão de ônus reais for the property, then the seller's personal certificates (civil, labor and federal courts, tax authorities), a condo debt statement signed by the síndico and an IPTU debt certificate from the city.
Don't count on the registry to stop a bad deal. Since September 2025, the CNJ bars registries from requiring tax-debt certificates before registering a deed, so a property with debts can change hands without anyone flagging it.
Condo debts are the classic trap: in October 2025 the STJ confirmed that the buyer on the matrícula can be charged condo fees even before getting the keys. Have the deed state that the seller pays everything owed before signing, and hold money back if there's any doubt.
How do I check zoning and permitted use in Brazil right now?
At the city hall (prefeitura): the Plano Diretor, the zoning map and the building records for the address or IPTU number. Ask for a land-use certificate if you plan works or a change of use.
The trap is assuming that a beach house, hillside home, island property or informal lot can be used, rented, renovated or extended because someone already lives there. Check that the built area on the IPTU record matches what you see; extensions without permits are common and hard to regularize.
In a condo, also read the convenção: it decides whether short stays are allowed.
 70+pages
How much below the asking price should you offer right now?
Start around 10% below, and more on a resale that has been listed for months. In the FipeZAP survey for the 12 months to June 2026, sellers gave an average discount of 9%, and 14% when they gave one at all. A foreigner who pays the listed price usually overpays.
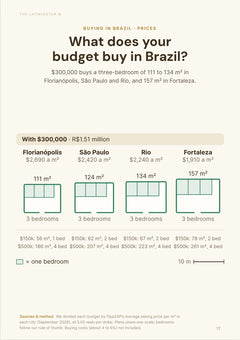
The market isn't running away from you. Asking prices rose 5.51% in the 12 months to September 2026 (FipeZAP, BRL 10,015 per m²), only 0.89% after inflation, while the Selic at 13.75% keeps many local buyers who need a loan out of the market. Cash is a real bargaining chip.
New builds have room too: developers had 355,290 new units for sale at the end of June 2026, up 8.2% in a year (CBIC). Negotiate the price, the payment plan and who pays the brokerage fee, and never pay a "SATI" or "assessoria" fee.
Before you offer, ask your lawyer or agent for recent sale prices in the same building, not just listings: FipeZAP figures are asking prices.
Can a foreigner get a mortgage in Brazil right now?
Do banks lend to foreigners for homes?
Rarely, unless you live there. The Banco Central lists Brazilian nationality, naturalization or permanent residency among the usual conditions for a housing loan. A foreigner with permanent residency, local income and a Brazilian credit history can apply like a local.
For a non-resident, we found no bank offering a standard housing loan in 2026, and no published loan-to-value. Plan to pay cash, or to borrow in your home country against assets there.
Which banks are most foreigner-friendly?
None publishes a product for non-resident foreigners. If you have residency, the big housing lenders are the place to ask: Caixa, Itaú, Santander, Bradesco and Banco do Brasil.
What helps: a CPF, a Brazilian account with some history, local income or income that's easy to verify, translated and apostilled documents, and a clean record of the money you've brought in.
Expect more questions, a lower loan amount and a longer process than a Brazilian, and start well before the deed date so the loan doesn't hold up the notary.
What mortgage rates are foreigners offered?
Those who qualify pay the same as Brazilians. In September 2026, average housing-loan rates were 7.98% plus TR at Caixa, 11.77% plus TR at Bradesco, 11.85% at Santander and 11.87% at Itaú, before insurance and fees (the total cost, or CET, is higher).
The backdrop is expensive money: the Selic was cut from 14% to 13.75% in September 2026, and the next Copom meeting is on 3 and 4 November.
 70+pages
How do you send the money, and get it back out later?
Through an authorized exchange bank, and you don't need a Brazilian bank account first: the Banco Central lists legal ways for a non-resident to pay the seller, or the seller's representative, from abroad.
The bank will ask who you are and where the money comes from, and it classifies the transfer. Ask for a written quote showing the rate, the fees and the IOF (the tax on exchange), because the IOF depends on how the operation is classified and there is no single rate for a property purchase.
Keep every exchange contract, your purchase contract and the registered deed. When you sell, you can send the net proceeds abroad after paying capital gains tax (15% on the first BRL 5 million of gain), and the bank may ask for that paper trail.
If you're counting on residency, this matters twice: the BRL 1,000,000 or BRL 700,000 has to come from abroad, so the exchange records are your proof.
How much will buying and owning cost you?
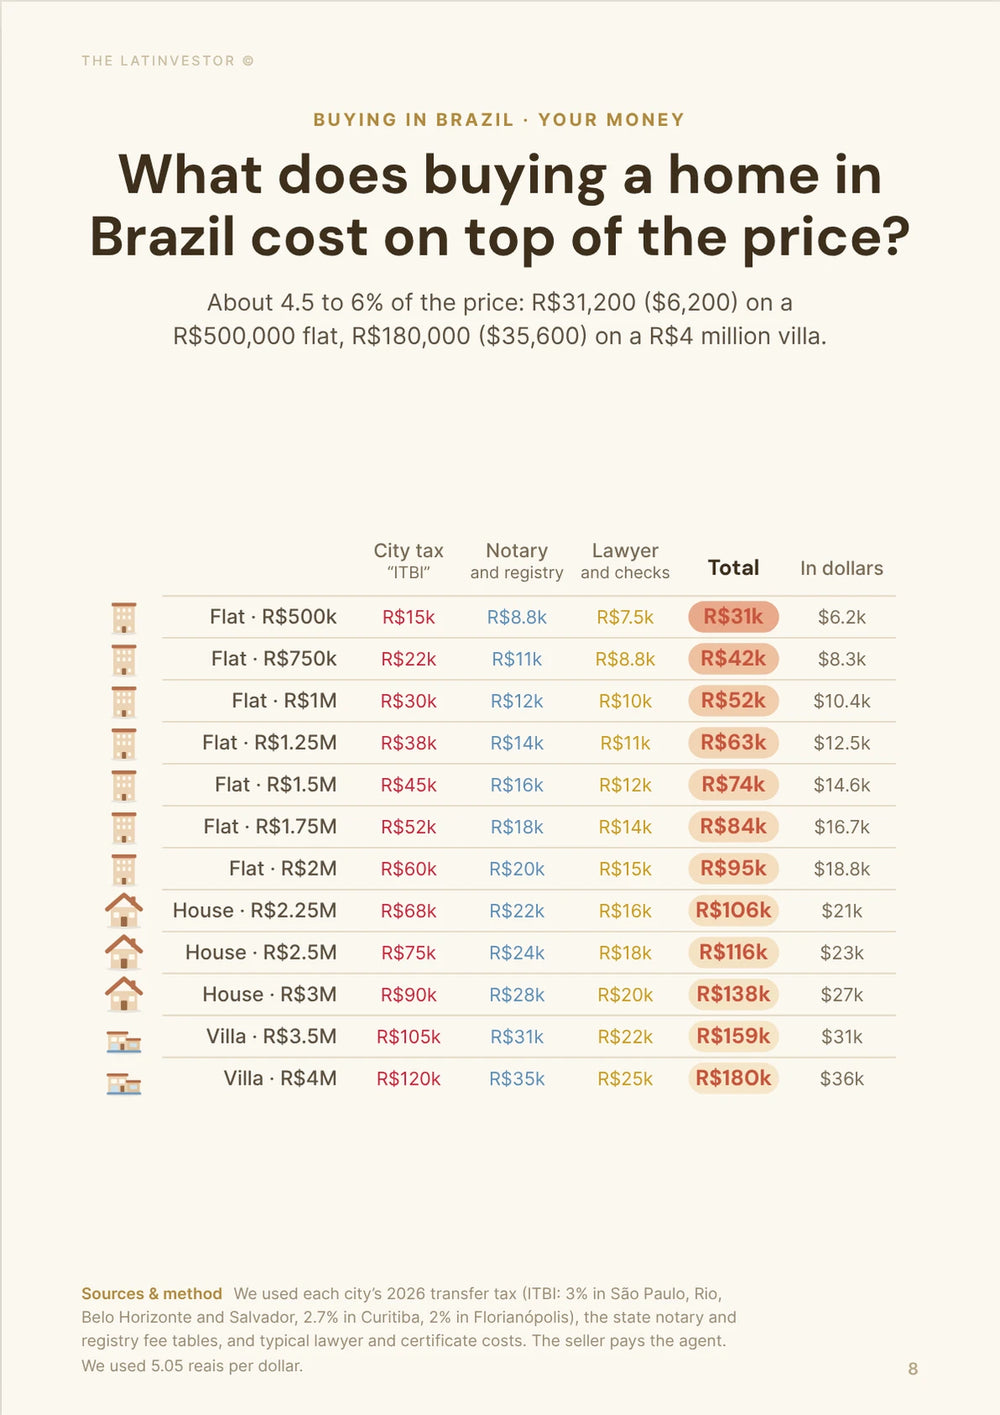
What are the total closing costs as a percent in Brazil?
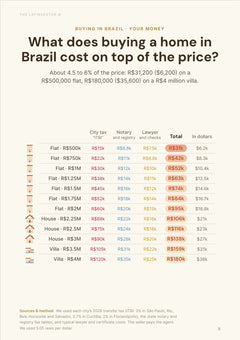
About 4% to 6% of the price. On a BRL 1,000,000 apartment (about USD 198,000), that's BRL 40,000 to BRL 60,000 (about USD 7,920 to USD 11,900). It drops to about 3% in cities with a 2% ITBI, if you skip the lawyer.
The biggest line is the ITBI, a city tax of 2% to 4%: 2% in Florianópolis and Brasília, 2.7% in Curitiba, 3% in São Paulo, Rio de Janeiro, Salvador and Belo Horizonte, and 4% in Fortaleza (2% if paid before the deed).
Then the notary and registry, about 1% together (in São Paulo, the 2026 deed fee is BRL 6,026 for a property between BRL 768,400 and BRL 1,152,600), plus your lawyer, certificates, sworn translations and the exchange costs. The agent's 6% to 8% commission is usually paid by the seller. More detail in our article on property taxes and fees in Brazil.
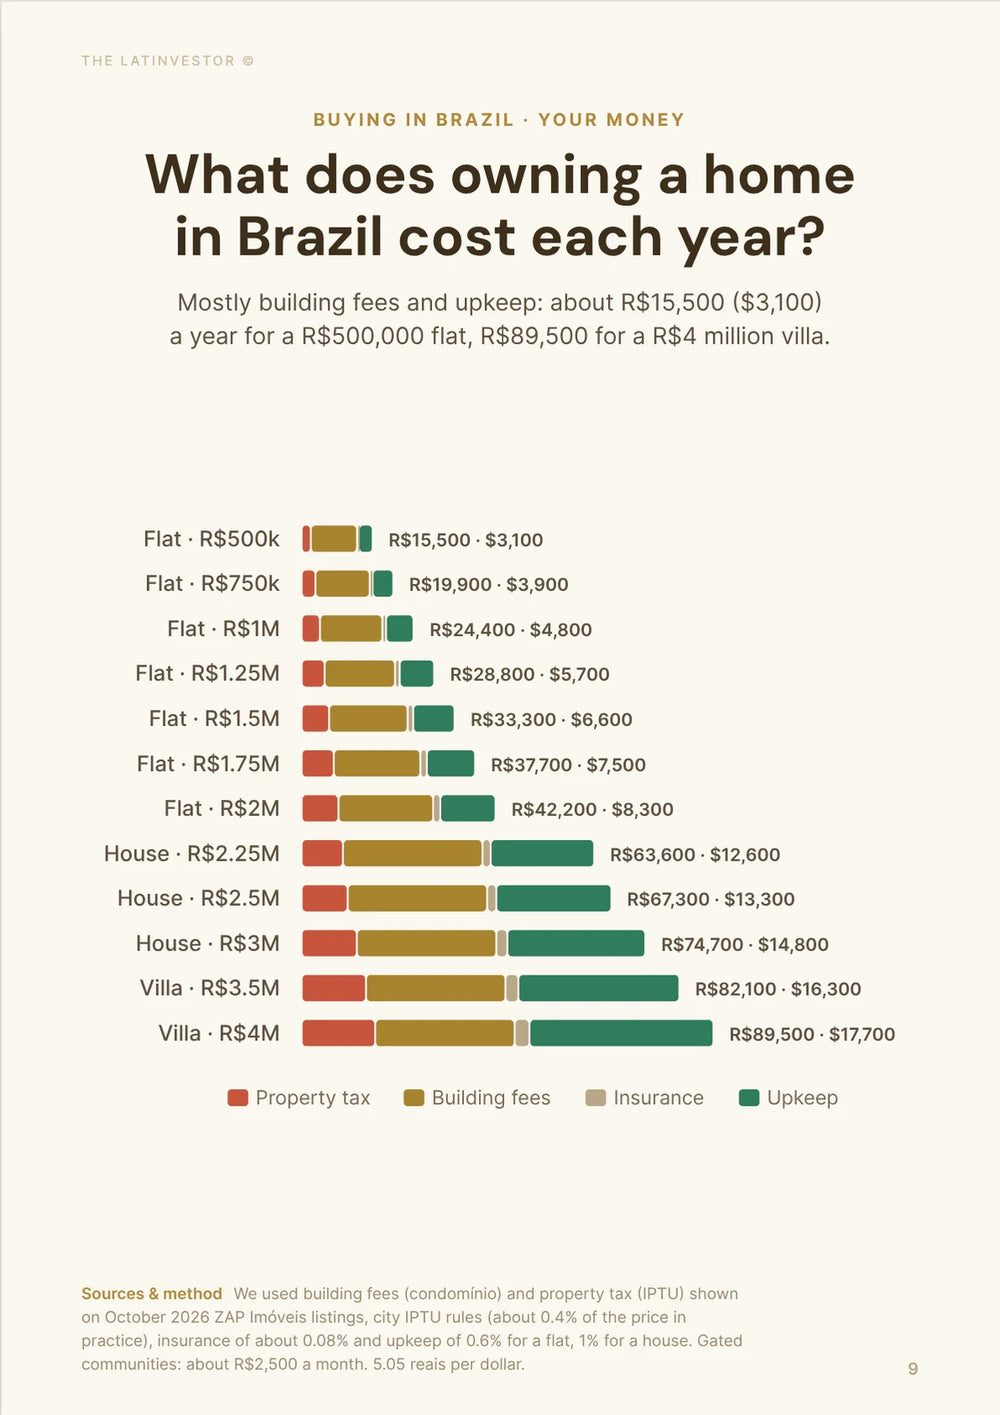
What annual property tax should I budget?
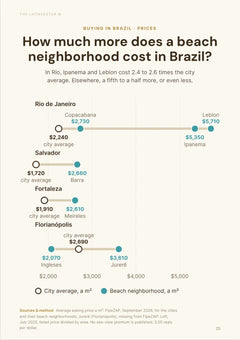
IPTU is a city tax charged on the city's assessed value (valor venal), which is often well below the market price. In 2026, rates go from 0.3% for homes in Brasília to 0.6% to 0.8% in Belo Horizonte and 0.6% to 1.4% in Fortaleza.
The only reliable figure is the property's own bill: ask the seller for the last IPTU carnê before you make an offer, and budget condo fees on top (Loft's 2026 averages: BRL 842 a month in São Paulo, BRL 620 in Rio).
How is rental income taxed for foreigners?
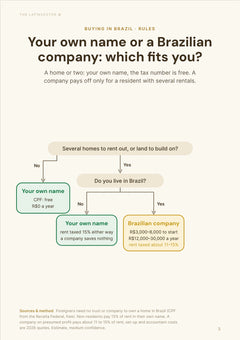
If you're not a Brazilian tax resident, 15% of the gross rent is withheld at source. It's on the rent, not the profit, so put it in any yield calculation.
The tenant or the agency that pays you usually handles the withholding, so use a local administrator who knows how. Once you spend more than 183 days in Brazil in 12 months, you become a tax resident and rent is taxed at up to 27.5%.
The CBS/IBS tax reform only catches individual landlords with more than three rented properties and more than BRL 240,000 of rent a year, so one or two units aren't affected.
What insurance is common and how much?
In an apartment, the building is already insured by the condo (the Civil Code makes it mandatory), so you insure your unit's contents and liability. A basic seguro residencial cost about BRL 280 to BRL 480 a year for an apartment in São Paulo, Rio or Belo Horizonte in 2026, and about BRL 450 to BRL 750 for a house. That's roughly USD 55 to USD 149 a year.
Cover usually includes fire, lightning, explosion, electrical damage, theft and civil liability. The price goes up with the address, flood risk, beach exposure, valuable contents and weak security.
Our methodology
This article walks a foreign buyer through a purchase in Brazil: what you can buy, the documents, the steps and timeline, the checks, financing, moving the money, and what it costs to buy and own. It's general information, not legal or tax advice for your case.
Rules come from official sources first: the Civil Code and federal laws on Planalto, INCRA, the SPU, the CNJ and the registries (ONR), the Receita Federal for the CPF and taxes, the Ministry of Justice for residency, the Banco Central do Brasil for payments, loans and the Selic, and STJ decisions. Costs come from city tax offices and the 2026 notary tables; market figures from FipeZAP, CBIC and Loft.
Some figures are estimates, and we say so: the 30 to 90 day timeline, and the insurance quotes, which come from a 2026 market article rather than an official source. We removed older figures we couldn't trace to a source, such as a loan-to-value range for foreigners and a fixed IPTU amount in reais.
We checked these figures in October 2026. Conversions use about 5.05 reais per US dollar and 5.65 reais per euro.
Limits: FipeZAP figures are asking prices, not sale prices; IPTU depends on each city's assessed value; banks set their own conditions for foreign borrowers; the IOF depends on how each transfer is classified; and the STJ hasn't issued its binding ruling on Airbnb in condos yet.
Key sources used for this analysis include Brazil's Civil Code, Law 5,709/1971, INCRA, Law 14,382/2022, ONR, CNJ, 26º Tabelionato de Notas on e-Notariado, the CPF service abroad, Ministry of Justice on RN 36/2018, Banco Central on housing loans, Banco Central rates by bank, Banco Central on payments by non-residents, Receita Federal 2026 tax tables, CNB/SP 2026 fee tables, FipeZAP September 2026, the FipeZAP Raio-X discount survey via Portas, CBIC and SUSEP.


