Summary
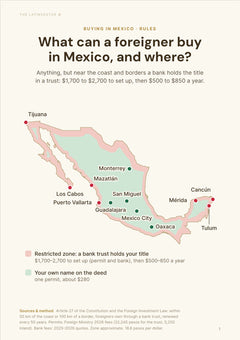
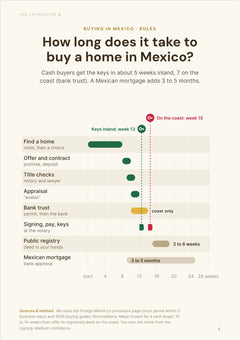
Yes. Americans can legally buy property anywhere in Mexico. The only twist is geography: within 50 km of a coast or 100 km of a border, a residential buyer holds the home through a bank trust (fideicomiso) instead of direct title.
Inland, in places like Mexico City or San Miguel de Allende, an American owns the property directly after a Foreign Ministry procedure that costs MXN 5,250 (about $280) in 2026.
The fideicomiso is not the part that should scare you. The beneficiary can live in, rent, sell and pass on the home, and the IRS said in Revenue Ruling 2013-14 that the standard Mexican land trust is not a foreign trust for U.S. tax purposes.
The 50-year term is not a countdown to losing the home. It can be extended, and the 2026 federal fee for an extension is MXN 595 plus MXN 9,740 if you file on time.
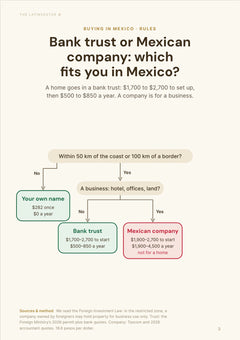
A Mexican company only makes sense for genuine commercial use. Setting one up costs roughly MXN 35,000 to 50,000 (about $1,900 to $2,700) before the yearly accounting, and it turns a home you would not report on Form 8938 into a company interest you would.
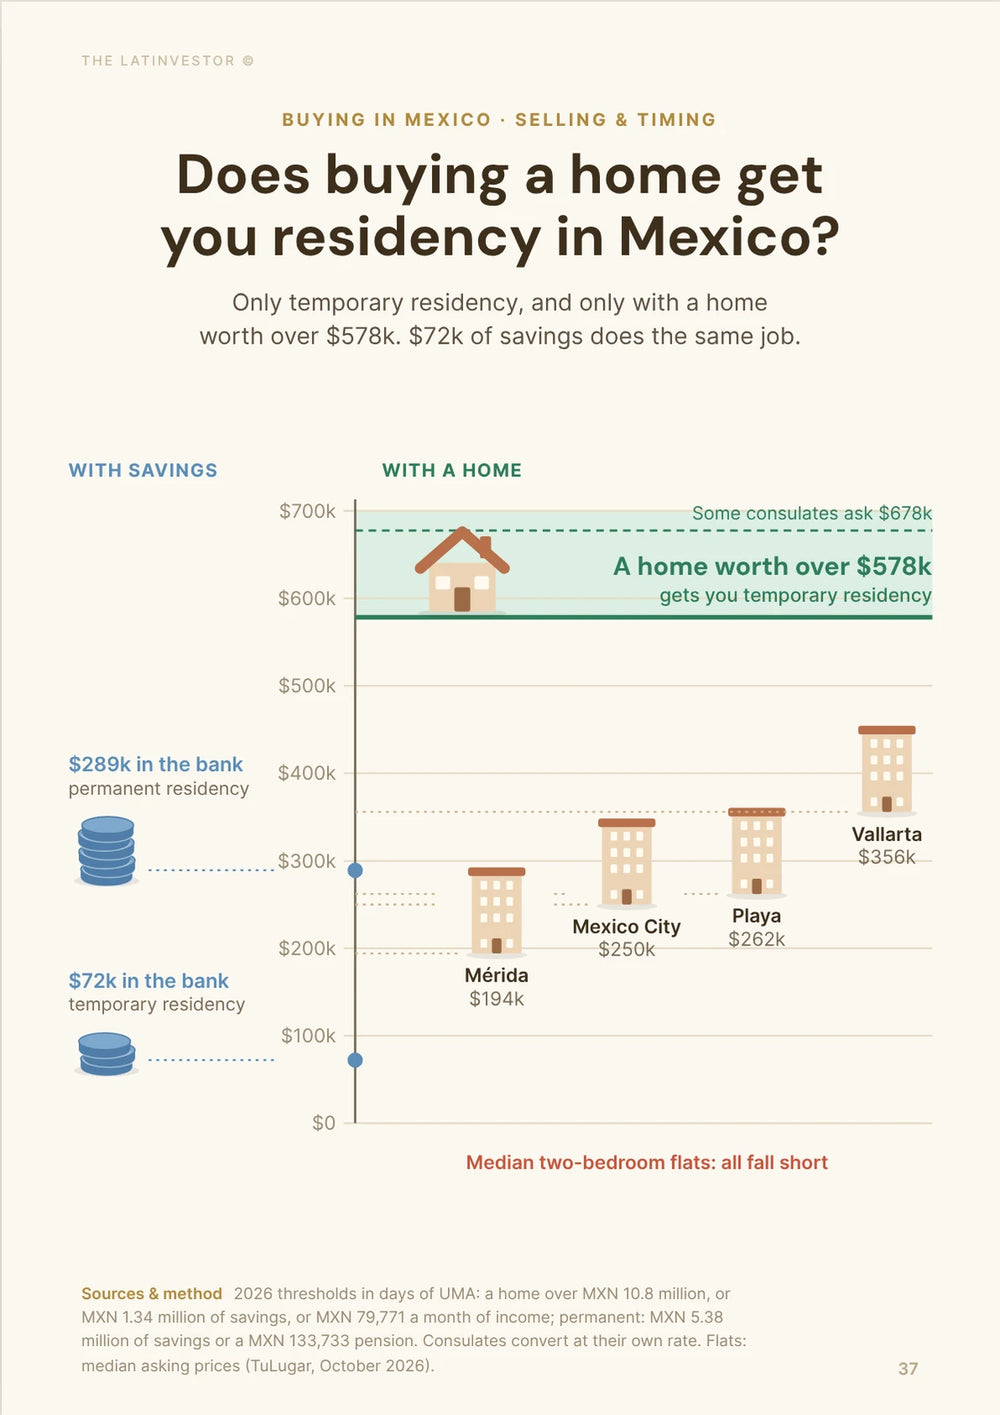
You don't need residency to buy, and buying doesn't give you residency. The property route to a temporary residence card asks for a very high value: one 2026 consular listing puts it at about MXN 10.76 million (around $578,000).
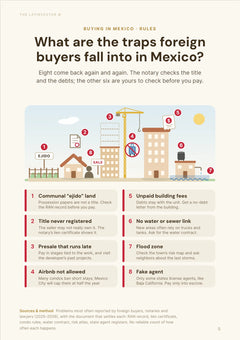
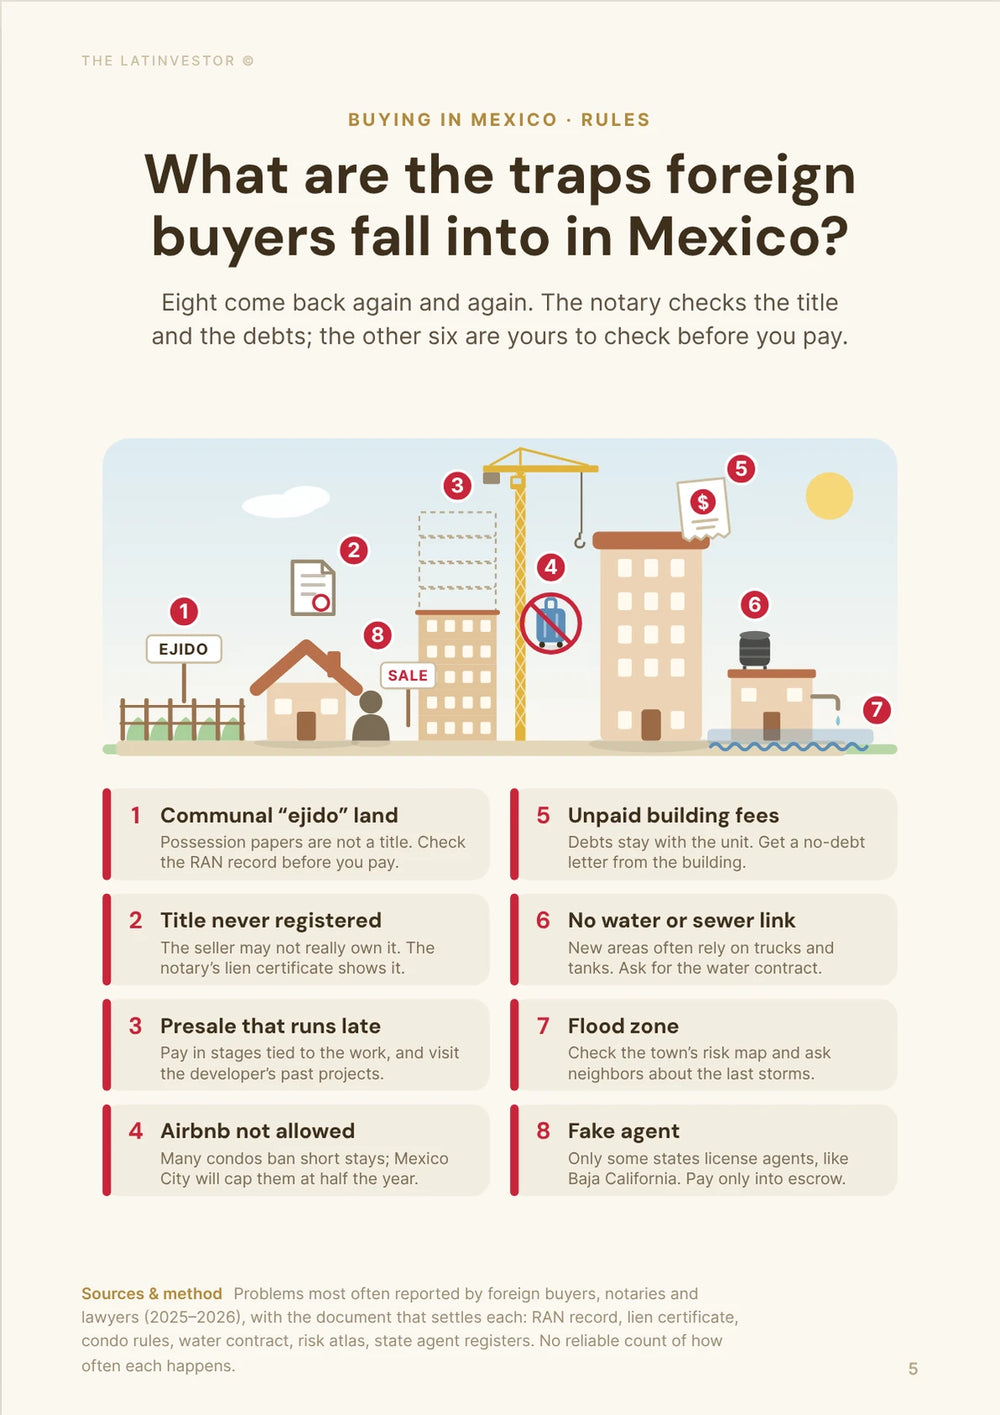
Ejido history is the real risk. Ejidos and agrarian communities still cover about 51% of Mexico’s territory, and a parcel certificate is not a private deed.
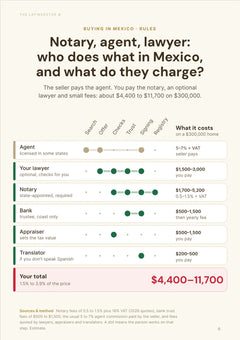
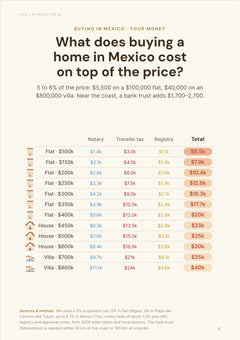
The 2026 SRE permit to open a fideicomiso is MXN 21,650 (about $1,160). Add a bank opening fee of roughly $550 to $800 and $550 to $700 a year, and plan on total closing costs of about 6% to 9% of the price on the coast.
The new 1% U.S. remittance tax, live since January 1, 2026, does not hit a normal wire from your U.S. bank account. It only applies to transfers funded with cash, money orders or cashier’s checks.
The exchange rate is the cost nobody mentions. The peso has weakened since early September (from under 17 to about 18.6 per dollar), which helps you, but your dollar still buys roughly 3% fewer pesos than on the 2025 average of 19.20, while national home prices rose 7.3% in a year.
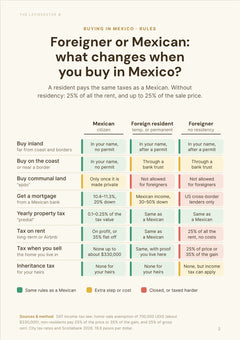
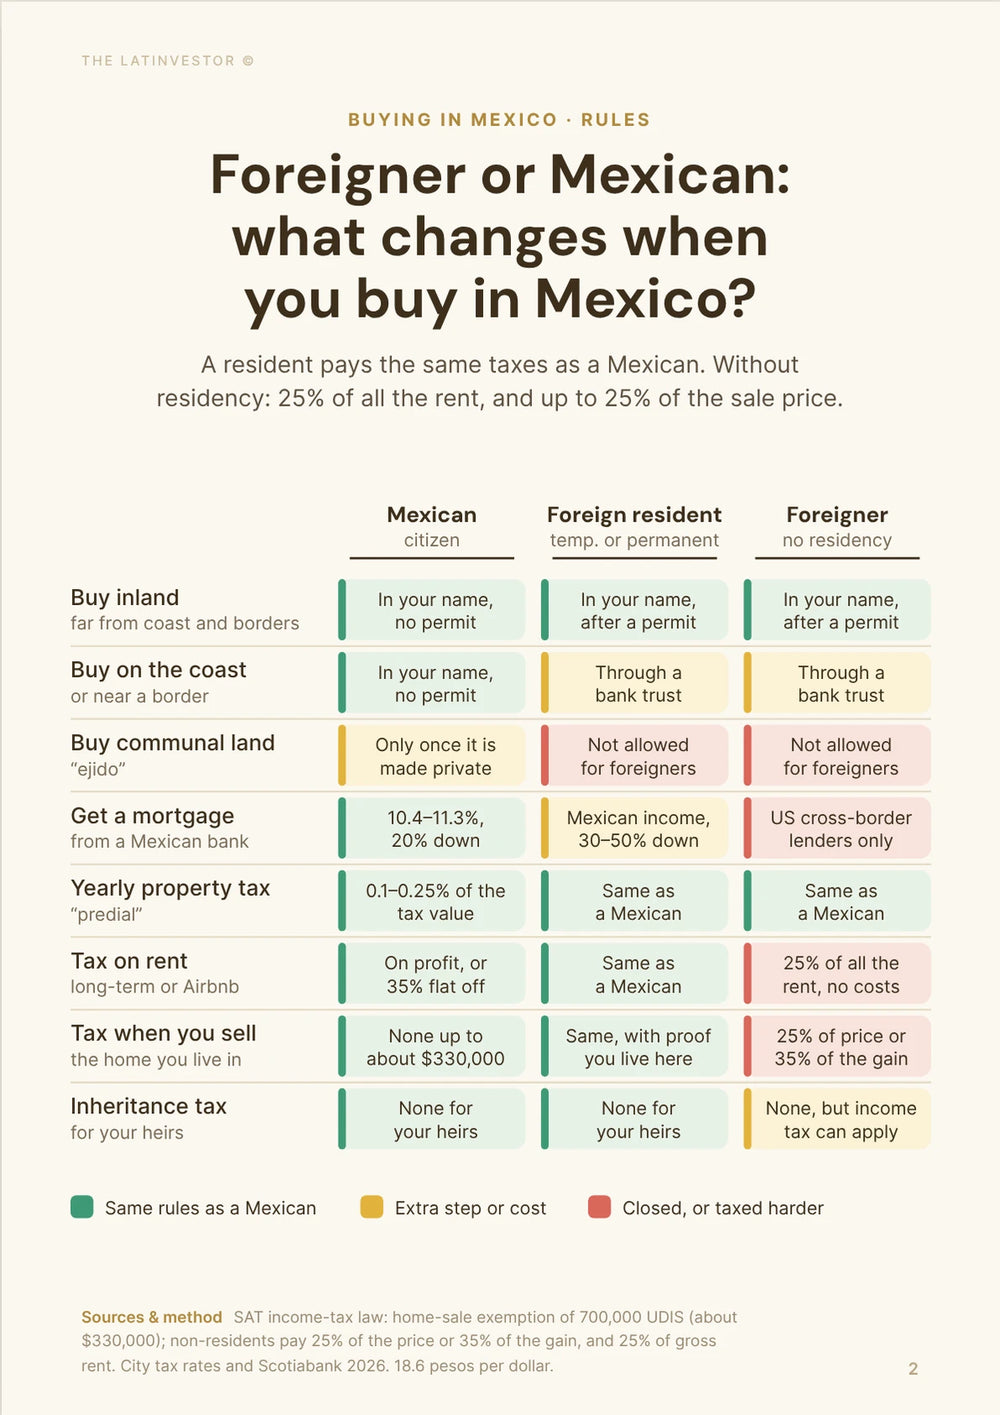
Renting out is allowed, but Mexico withholds 25% of gross rent from non-residents, and Airbnb withholds 4% of your bookings if you give it a Mexican tax ID (20% if you don’t).
Selling is straightforward, but a non-resident pays either 25% of the gross sale price or up to 35% of the net gain through a Mexican legal representative. The U.S. foreign tax credit can offset part of that on your U.S. return.
On the U.S. side, the house itself is not reported on Form 8938, but Mexican bank accounts are reported on an FBAR once their combined balance tops $10,000 at any point in the year.
Bottom line: the foreign-ownership rules are routine. Spend your energy on clean title, the real tax bill, and how and when you move the dollars.

Can Americans legally buy property in Mexico today?
Yes. Americans can legally buy property in Mexico today, including houses, condos and beachfront homes, although the ownership structure changes near Mexico’s coasts and international borders.
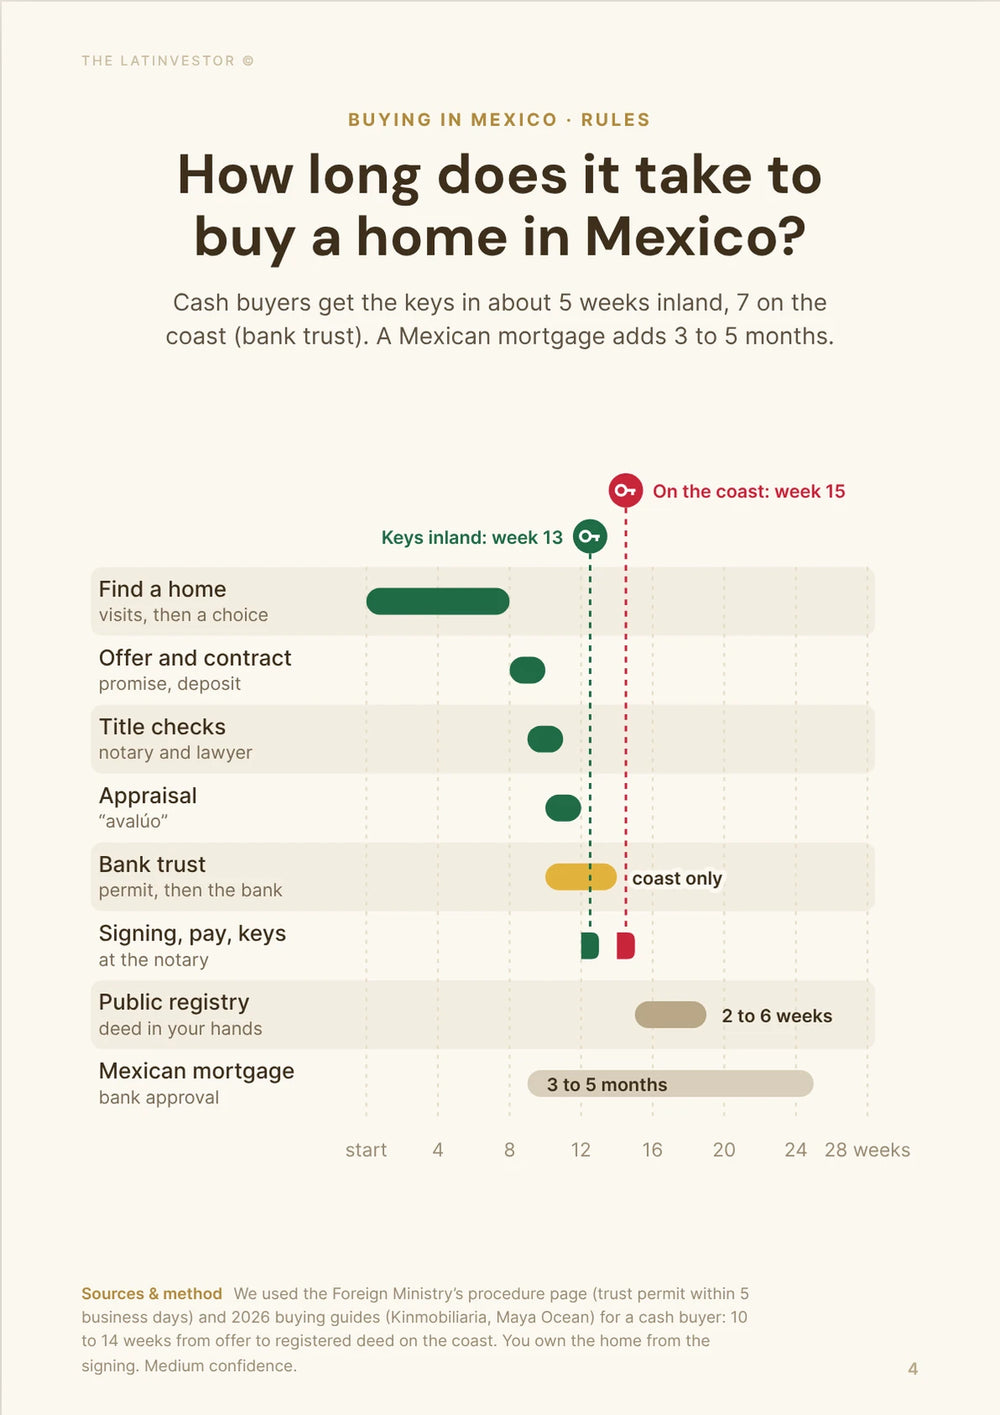
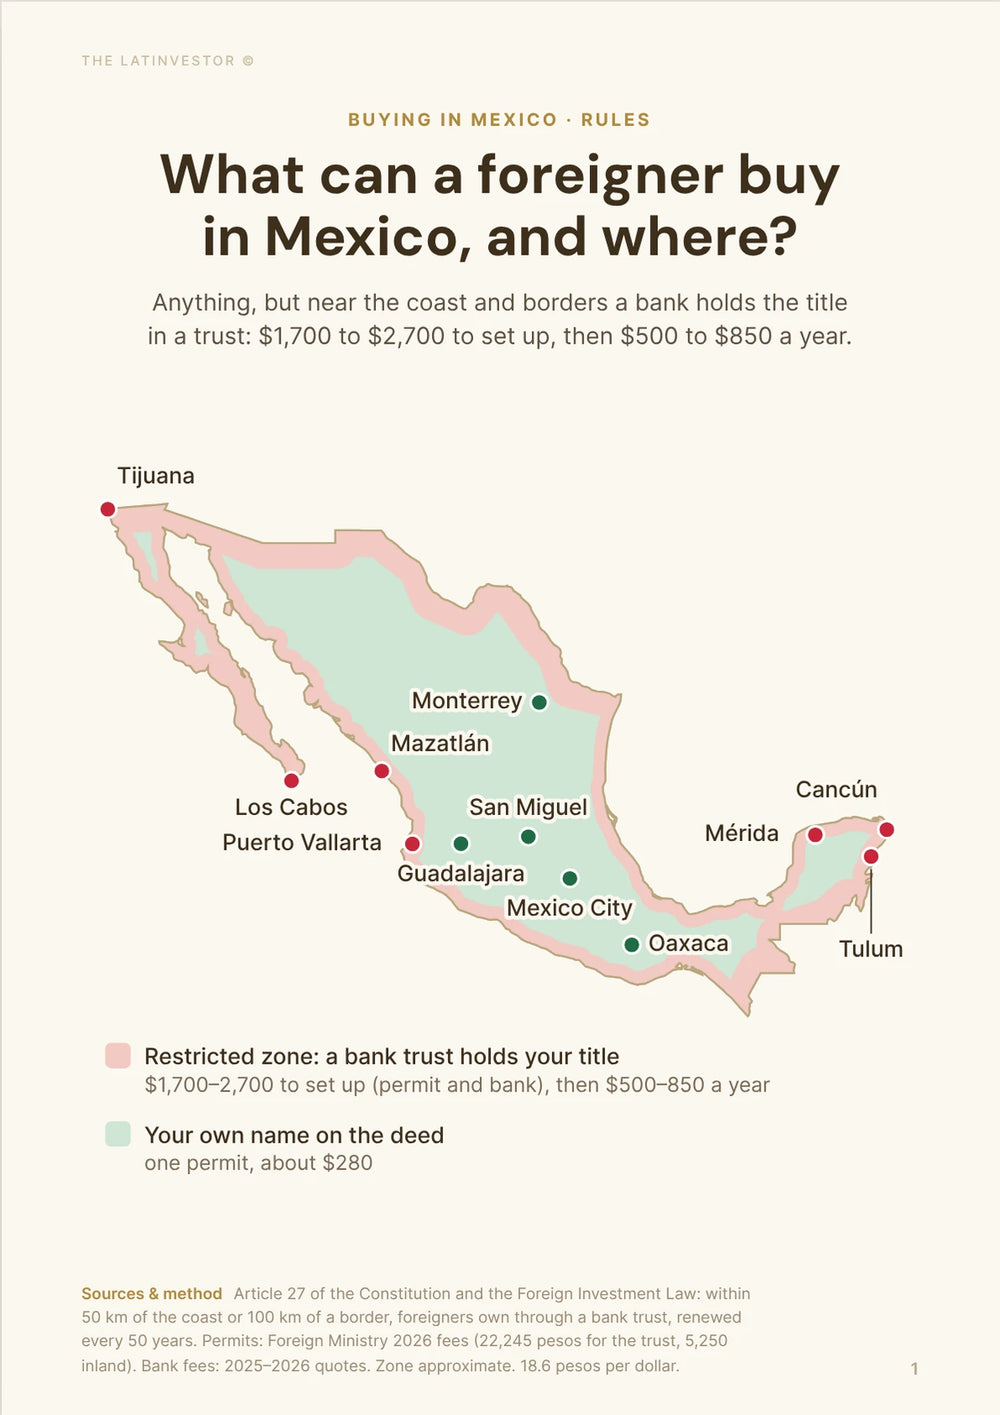
Throughout most of Mexico, an American can acquire the property directly. The buyer signs an Article 27 agreement with the Foreign Ministry (SRE), which costs MXN 5,250 (about $280) in 2026.
The exception covers what Mexican law calls the restricted zone: land within 50 kilometers of a coastline or 100 kilometers of an international border. An American buying residential property there normally uses a fideicomiso, a Mexican bank trust authorized by the Foreign Ministry.
This is why an American can directly own a home in Mexico City or San Miguel de Allende while generally using a fideicomiso for a condo in Puerto Vallarta, Cancún or Los Cabos.
The rules are moving the other way from what some people fear. In 2026 Mexico simplified several Article 27 procedures: the fideicomiso permit now only needs the online application through SIPAC27 and proof that the fee was paid. We found no 2026 reform that removes or tightens the restricted zone.
| Property situation | Can an American buy? | Typical structure | Main issue |
|---|---|---|---|
| Home well inland | Yes | Direct ownership | Foreign-buyer permit and normal closing |
| Coastal home or condo | Yes | Fideicomiso | Bank holds legal title |
| Home near U.S. border | Yes | Fideicomiso | Same restricted-zone rule |
| Certain commercial property in restricted zone | Yes | Mexican company may be possible | Use of property matters |
| Ejidal land without proper conversion | Not like ordinary private property | Agrarian regime | Title must be checked carefully |
Why do people still say Americans cannot own property in Mexico?
People keep saying Americans cannot own Mexican property because the rule affecting beaches and borders gets repeated as though it applies to the entire country.
Article 27 of Mexico’s Constitution does prohibit foreigners from directly owning land within 50 kilometers of the coast and 100 kilometers of an international border. Read that sentence without the rest of the legal framework and the conclusion sounds obvious: Americans cannot own coastal Mexican real estate.
Mexico subsequently built a legal system allowing foreigners to use and benefit from residential property in those areas through fideicomisos. The Foreign Investment Law specifically provides for the arrangement, and the Foreign Ministry currently processes the permits.
The confusion survives partly because the places Americans hear most about are exactly where the restriction applies. Los Cabos, Puerto Vallarta, Cancún, Playa del Carmen and Tulum are all coastal markets. Someone researching a Mexican vacation home can therefore encounter fideicomisos almost immediately and assume every foreign buyer in Mexico faces the same restriction.
Move inland and the picture changes quickly. Large parts of Mexico allow foreigners to acquire direct ownership after completing the Article 27 procedure.
The accurate rule is straightforward: Americans can buy throughout Mexico, but they generally cannot hold residential coastal or border land directly in their own name.
Where can Americans own Mexican property directly?
Americans can directly own Mexican property located outside the 50-kilometer coastal strip and the 100-kilometer border strip.
The Foreign Ministry procedure explicitly allows foreigners to acquire ownership of real estate outside the restricted zone. The buyer signs the Article 27 agreement, promising not to seek the protection of the U.S. government over the property, and pays the MXN 5,250 fee.
For practical purposes, this puts many of Mexico’s major inland markets in the straightforward category. Mexico City and San Miguel de Allende are obvious examples. Most of Guadalajara also sits comfortably outside the restricted coastal zone.
Coastal resort markets fall on the other side. Puerto Vallarta, Cancún and Los Cabos are all within the constitutional coastal strip, so an American buying a residential property there will normally use a fideicomiso.
The distinction can sometimes produce surprising results. Two properties in the same state may require completely different structures simply because one lies inside the restricted zone and the other does not.
Direct foreign ownership in inland Mexico is a normal legal route, not some unusual exception. If you are unsure, ask the notary to confirm in writing whether the exact address falls inside the zone before you sign anything.
| Example market | Inside restricted zone? | Typical American ownership |
|---|---|---|
| Mexico City | No | Direct ownership |
| San Miguel de Allende | No | Direct ownership |
| Guadalajara | Generally no | Direct ownership |
| Puerto Vallarta | Yes | Fideicomiso |
| Cancún | Yes | Fideicomiso |
| Los Cabos | Yes | Fideicomiso |
Can Americans really own beachfront property in Mexico?
Yes. Americans can buy and control beachfront residential property in Mexico through a fideicomiso, even though they cannot normally hold the coastal land directly in their own name.
A fideicomiso sounds stranger than it functions. A Mexican bank becomes the trustee and holds legal title to the property. The American buyer becomes the beneficiary and receives the rights set out in the trust.
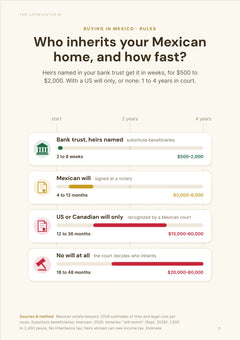
Mexico’s Foreign Investment Law allows those rights to include the use and enjoyment of the property and the economic benefits produced by it. In a properly structured residential fideicomiso, the beneficiary can normally live in the property, sell the beneficial interest, designate successor beneficiaries and receive income from permitted rentals.
The bank does not move into the house, decide when the owner can visit or take the property’s rental income for itself. Its role is mainly tied to the legal title and the administration of the trust.
The IRS examined this structure in Revenue Ruling 2013-14. Its example involved a U.S. person with Mexican residential property in the restricted zone. The American controlled possession, improvements and rental activity while the Mexican bank principally held title and collected its fee. That arrangement was substantial enough for the American to control the property, yet limited enough on the bank’s side that the IRS did not classify it as a trust for U.S. federal tax purposes.
An American buying on the beach does give up one specific thing: personal legal title to the land. The practical control retained through a standard fideicomiso is much broader than the phrase “foreigners cannot own beachfront property” suggests.
| Property right | Direct owner | Fideicomiso beneficiary |
|---|---|---|
| Live in the property | Yes | Yes |
| Use it as a vacation home | Yes | Yes |
| Rent it when permitted | Yes | Yes |
| Receive rental income | Yes | Yes |
| Sell the property or beneficial rights | Yes | Yes |
| Name successor beneficiaries | Through estate planning | Generally yes |
| Hold legal title personally | Yes | No |
Does an American lose the Mexican property when the 50-year fideicomiso ends?
No. The 50-year term does not normally mean an American loses the Mexican property after five decades because Mexican law allows fideicomisos to be extended.
The Foreign Ministry currently describes restricted-zone fideicomiso permits as lasting for a maximum initial period of 50 years. It also maintains a separate procedure for extending the duration of an existing fideicomiso.
The 50-year number can sound suspiciously similar to a long lease, but the economics are very different. A beneficiary can buy and sell the rights during the trust period, and the legal framework allows the trust to continue through an extension.
The practical issue appears when buying an older resale property. If a fideicomiso has already been running for decades, we would want to know how much time remains, whether the trust will be extended during the transaction, which bank acts as trustee and what fees or paperwork will accompany the change.
The SRE fee schedule updated in September 2026 still lists the extension as an active procedure: MXN 595 to receive and review the request, plus MXN 9,740 to issue it if you file on time, or MXN 10,615 if you file late. That is about $560 in total when filed on time, before bank and notary fees, so file before the trust runs out.
So the 50-year number deserves attention, especially on an older property, but it should not be interpreted as a countdown to confiscation.
Can an American use a Mexican company instead of a fideicomiso?
Sometimes, although a Mexican company is mainly useful when the property genuinely has a business or non-residential purpose.
Mexican companies with foreign shareholders can directly acquire certain properties in the restricted zone when those properties are used for non-residential activities. Mexican regulations include uses such as commercial, industrial, agricultural and service activities within that framework.
The government still distinguishes those acquisitions from residential foreign ownership. A recent federal simplification measure, for example, retained a specific notification procedure for Mexican companies with foreign participation acquiring restricted-zone property for non-residential purposes.
This can make a Mexican company attractive for an investor developing commercial premises, operating a business or buying property whose real use falls clearly outside residential ownership.
A personal beach house is different. Forming an S.A. de C.V. costs roughly MXN 35,000 to 50,000 (about $1,900 to $2,700) in legal and notary fees, then it needs a Mexican accountant every month. It also changes your U.S. paperwork: the IRS says a home held through a foreign company is reported on Form 8938 as an interest in that company, and the company itself usually brings its own U.S. filings.
We would be skeptical of anyone presenting a Mexican corporation as the automatic “better” structure for every American buyer. For a normal coastal residence, the fideicomiso exists precisely for that situation.
Do Americans need Mexican residency before buying property in Mexico?
No. An American does not generally need Mexican temporary or permanent residency before buying Mexican real estate.
Mexico treats immigration status and property ownership as separate legal questions. Foreign Ministry and diplomatic guidance allows foreigners with regular migratory status to go through the property-acquisition process, and current federal paperwork asks foreign buyers to provide the relevant immigration information.
So an American visiting Mexico legally can potentially buy property without first becoming a Mexican resident.
Buying property can later become relevant to immigration, but the direction works differently. Mexican consulates offer a temporary-residence route for owners of Mexican real estate above a qualifying value, but the bar is high and it changes from one consulate to another. One 2026 consular listing sets it at 91,710 times the daily UMA, about MXN 10,758,500 (around $578,000). Most Americans qualify more easily through income: about MXN 79,770.80 a month (around $4,290) or average savings of about MXN 1,344,372.60 (around $72,300) over the last 12 months for temporary residence in 2026.
Simply buying a home therefore does not hand the buyer a residence card, and buying a cheap condo does not create an automatic “golden visa.”
For someone who wants both a Mexican home and residency, we would treat them as two connected projects rather than one transaction. The property purchase follows property law; the residence application follows immigration law.
Is ejido land safe for Americans to buy in Mexico?
Ejido land can become private property, but Americans should not buy an ejidal parcel as though an informal contract or parcel certificate were the same thing as a normal private deed.
This is where Mexican property research gets serious. According to the latest Registry of Agrarian Land figures incorporated into federal rules, Mexico had 29,849 ejidos and 2,425 agrarian communities at the end of 2025. Together they covered about 99.6 million hectares.
That is roughly 51% of Mexico’s territory.
That scale is why ejido history cannot be treated as some obscure problem affecting a few remote villages. Social property still covers more land than many foreign buyers probably realize, including areas around expanding cities and tourism markets.
Ejidal parcels can move into the private-property system, but there is a formal legal process. The ejido assembly must authorize dominio pleno where applicable, the agrarian registry has to record the relevant acts, and the parcel eventually needs the title and registration required for it to function as private property.
A seller showing a parcel certificate has therefore shown something important, but not necessarily what the American buyer thinks. A parcel certificate establishes agrarian rights. It is not automatically equivalent to a privately titled home recorded in the ordinary Public Registry of Property.
We would be especially cautious around cheap undeveloped lots where the sales pitch relies on phrases such as “regularization is coming,” “the title is being processed” or “everyone here buys this way.”
| What the seller shows | What it tells us | Ordinary private title? | Risk for buyer |
|---|---|---|---|
| Registered private deed | Property is in private regime | Yes, subject to verification | Normal due diligence |
| Ejidal parcel certificate | Holder has agrarian parcel rights | No | Different legal regime |
| Assembly approval for dominio pleno | Privatization process has advanced | Not yet by itself | More steps must be checked |
| Title issued after valid conversion | Parcel has moved toward private regime | Potentially, after registration | Verify complete chain |
| Private possession agreement | Someone claims contractual or possessory rights | No | High |
How do Americans make sure a Mexican property actually has clean title?
Americans should verify the Mexican property itself before worrying too much about the foreign-buyer structure, because bad title can cause far more trouble than a properly created fideicomiso.
The notario público plays a central role here. A Mexican notary has far greater legal responsibility than the person Americans usually picture when they hear the word “notary.” The notary formalizes the deed, checks documents needed for the transaction, handles important tax and registration steps and sends the instrument into the Public Registry system.
Mexico’s consumer rules for residential real estate also give notaries responsibilities around reviewing the documentation presented by the parties, explaining deed costs, dealing with relevant tax payments and filing the instrument for registration.
Still, we would not assume the notary makes every difficult property risk disappear. A straightforward resale condo with a clean recorded history is one thing. Pre-construction property, land with an ejidal history, unusual possession claims, boundary problems or complicated development permissions deserve more scrutiny.
A buyer should be able to establish who legally owns the property, whether the seller can transfer it, whether liens or encumbrances exist, whether taxes and relevant charges are current, whether the physical property matches the legal description and whether the final deed records the deal the buyer thinks was agreed.
The foreign-buyer rule is quite standardized once the property qualifies. Problems become much harder when the underlying asset itself is messy.
How much extra does an American pay to buy in Mexico in 2026?
Buying Mexican property is not dramatically more expensive simply because the buyer is American, although foreign buyers can face extra federal and bank costs depending on the ownership structure.
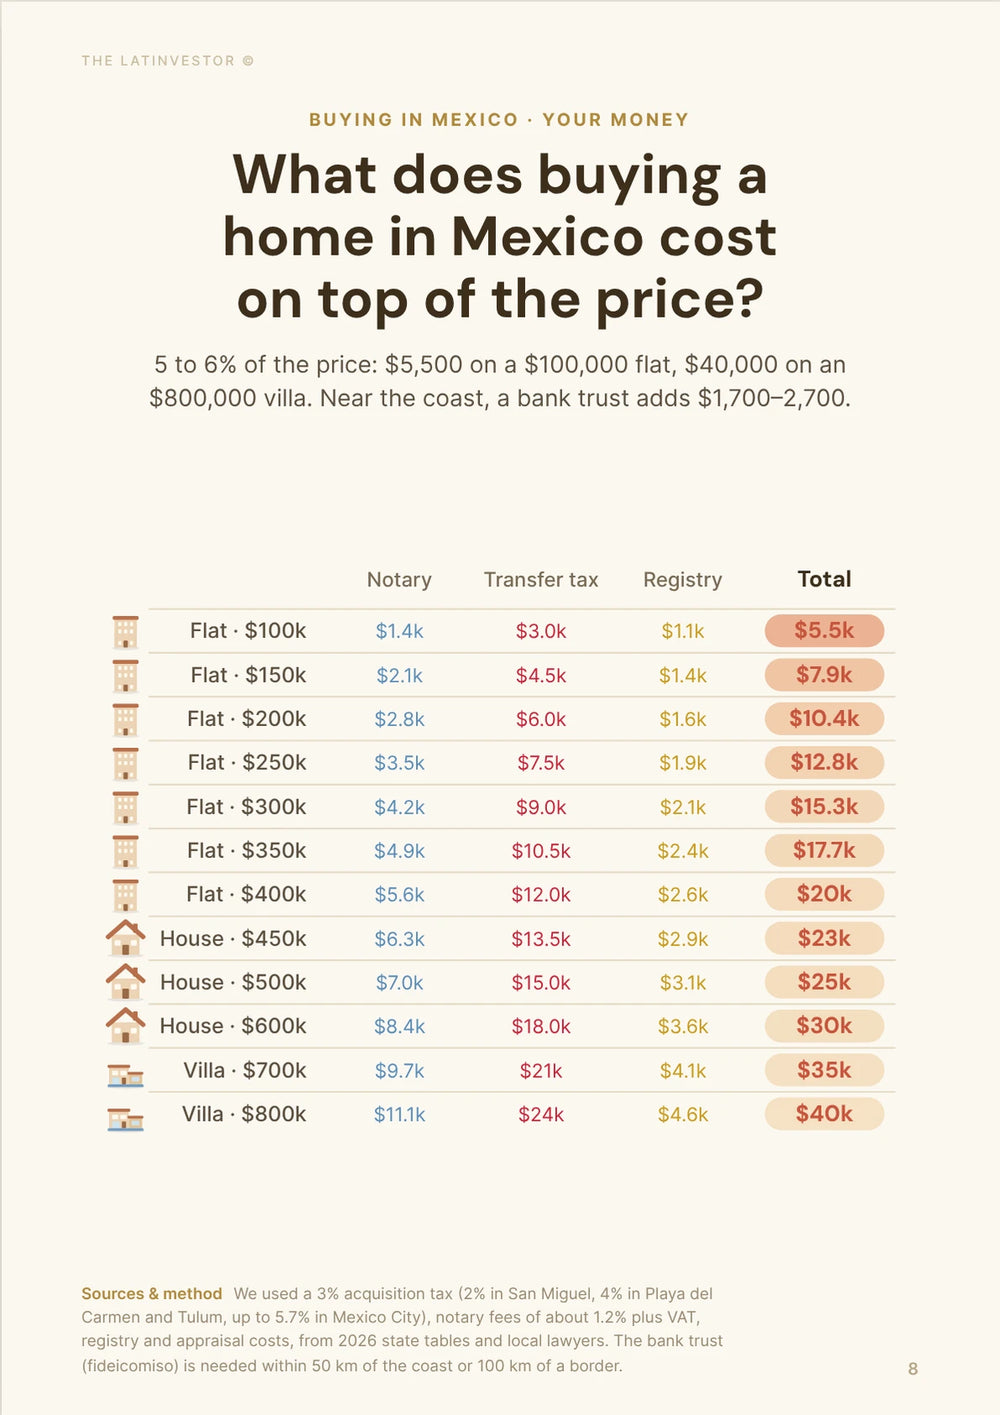
Every buyer can encounter acquisition tax, notarial costs, registration expenses, valuations and other closing charges. Those amounts vary by state, municipality, property value and transaction, so a single nationwide “Mexico closing cost percentage” is usually too simplistic.
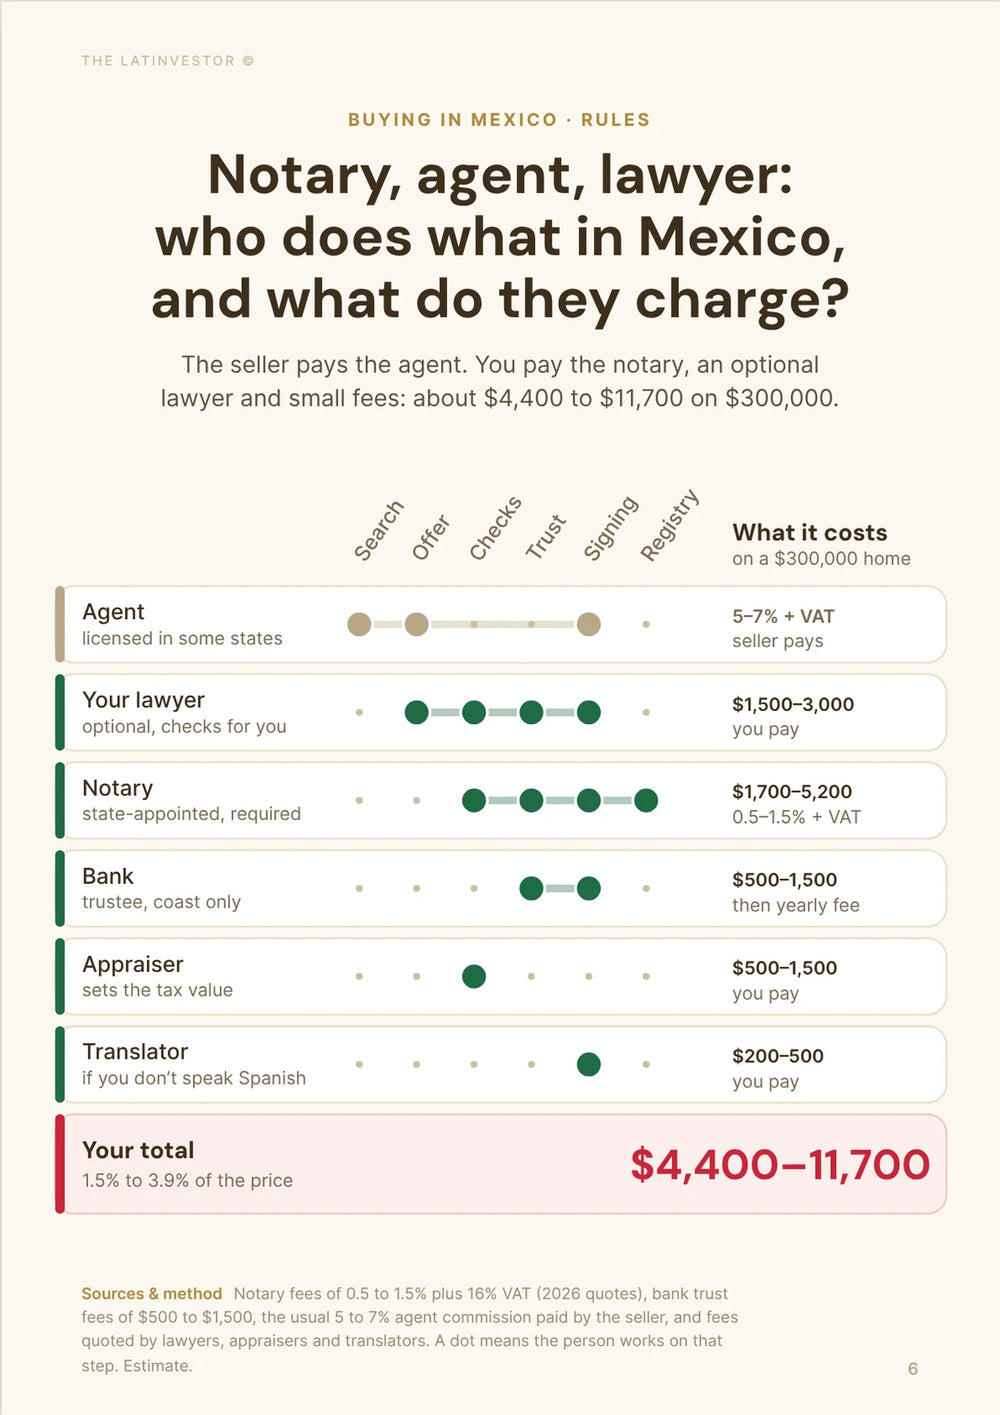
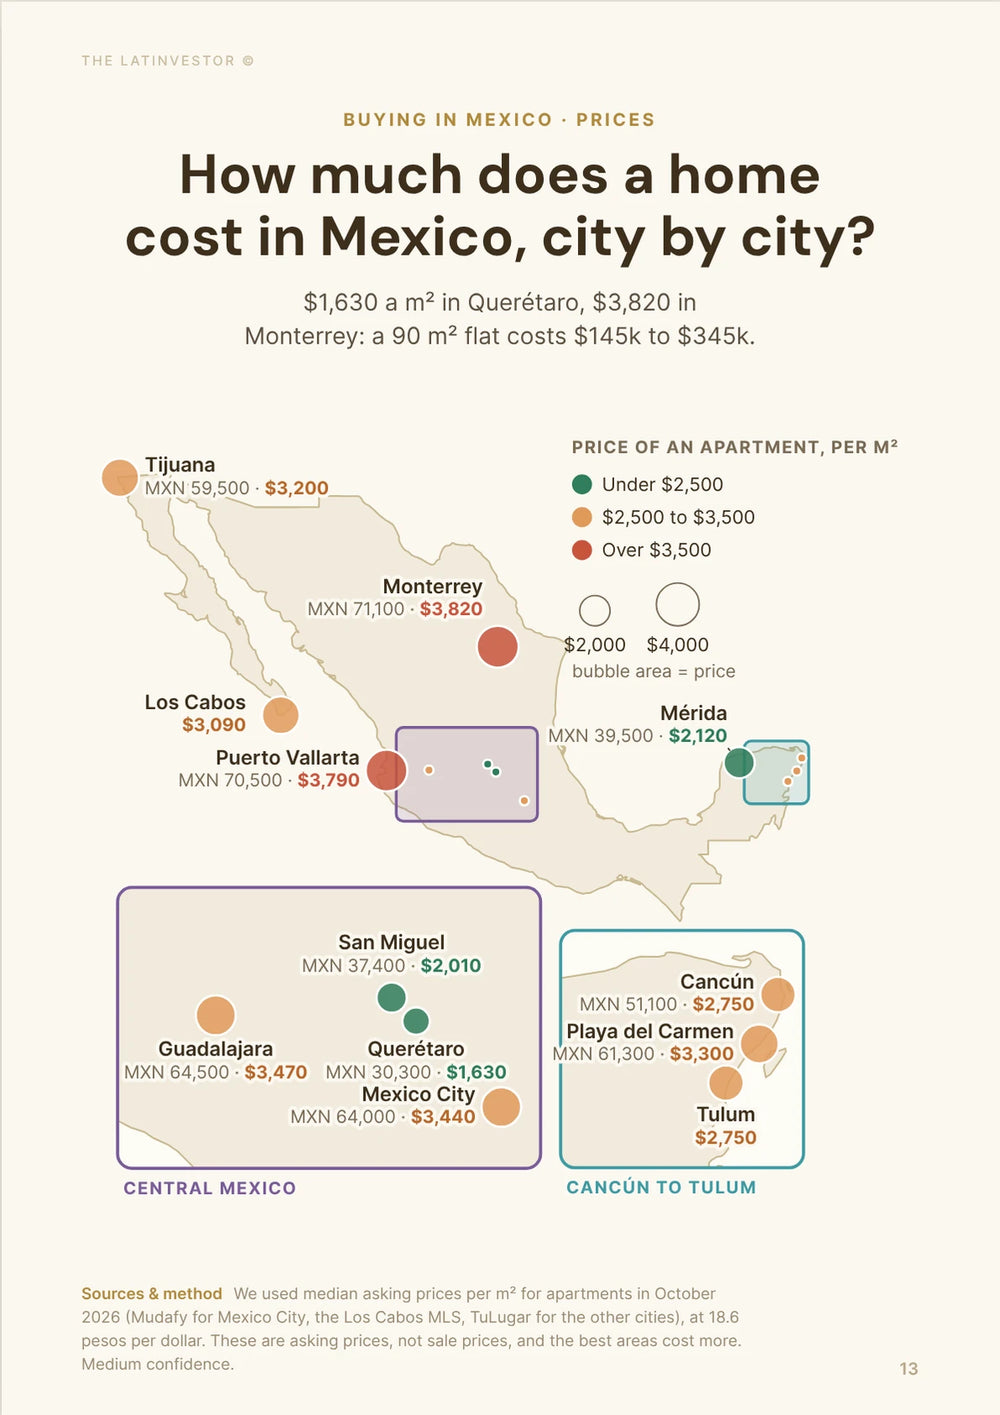
As a rough planning number, total closing costs for a foreign buyer on the coast, trust included, run about 6% to 9% of the price. The notary’s own fee is usually 0.5% to 1.5% of the price.
Restricted-zone buyers add fideicomiso expenses. The SRE schedule valid from January 1, 2026 charges MXN 21,650 (about $1,160) for the permit to create a restricted-zone fideicomiso. Some guides still quote an older, lower figure, so check the line on your closing statement.
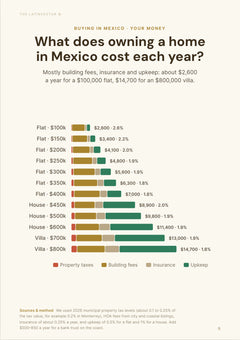
The bank trustee then sets its own fees. A 2026 broker comparison puts the opening fee at about $550 (Banorte) to $800 (HSBC) and the yearly fee at about $550 to $700. These are not official bank tariffs, so ask two or three banks for a written quote: the yearly fee is paid for as long as you own the home, so it is worth negotiating.
Direct foreign ownership outside the restricted zone also has a federal procedure: the Article 27 agreement costs MXN 5,250 (about $280), on top of the normal expenses of buying and notarizing the property.
An American should budget beyond the listing price, but the foreign-buyer premium itself is usually a collection of identifiable administrative costs rather than a special tax imposed simply for being American.
| Cost | Inland direct purchase | Coastal fideicomiso purchase | Same everywhere? |
|---|---|---|---|
| Acquisition tax | Yes | Yes | No |
| Notarial costs | Yes | Yes | No |
| Public Registry costs | Yes | Yes | No |
| Foreign-buyer federal procedure | Yes, MXN 5,250 | Covered by the trust permit | Government-set |
| Fideicomiso creation permit | No | Yes, MXN 21,650 | Federal fee |
| Bank setup/admin fees | No | About $550-800, then $550-700 a year | Bank-specific |
Will the new 1% U.S. remittance tax hit the money you send for a Mexican home?
No, not if you wire the money from a U.S. bank account. The 1% remittance tax that started on January 1, 2026 only applies to transfers paid with cash, a money order, a cashier’s check or a similar paper instrument.
The tax came with the One Big Beautiful Bill Act, and Mexico is the country it hits hardest because of the size of family remittances. Treasury and the IRS published proposed rules in April 2026 confirming that transfers funded from a U.S. bank account or a U.S. debit or credit card are outside its scope. It depends on how the transfer is paid, not on your citizenship.
What to do: send the deposit and the balance by bank wire from your own U.S. account to the notary’s or the escrow account, never in cash through a money-transfer counter. On a $300,000 purchase, a cash-funded transfer would cost $3,000 in tax alone, and Mexican notaries generally won’t accept large cash payments for a property anyway.
Has the peso's recent slide made Mexican property cheaper for Americans?
Cheaper than a few weeks ago, yes, but not cheaper than a year ago. The peso went from under 17 per dollar in early September to about 18.6 in October 2026, yet your dollar still buys roughly 3% fewer pesos than on the 2025 average of 19.20, and national home prices kept rising at the same time.
The federal mortgage agency SHF measured a 7.3% rise in home prices over the year to the second quarter of 2026. For a buyer paying in dollars, a home priced in pesos is therefore about 11% more expensive than a year earlier. Forecasters expect the peso to firm up again: BBVA sees 17.30 pesos per dollar at the end of 2026, the Banxico analyst survey 17.57 and Citi 18.20.
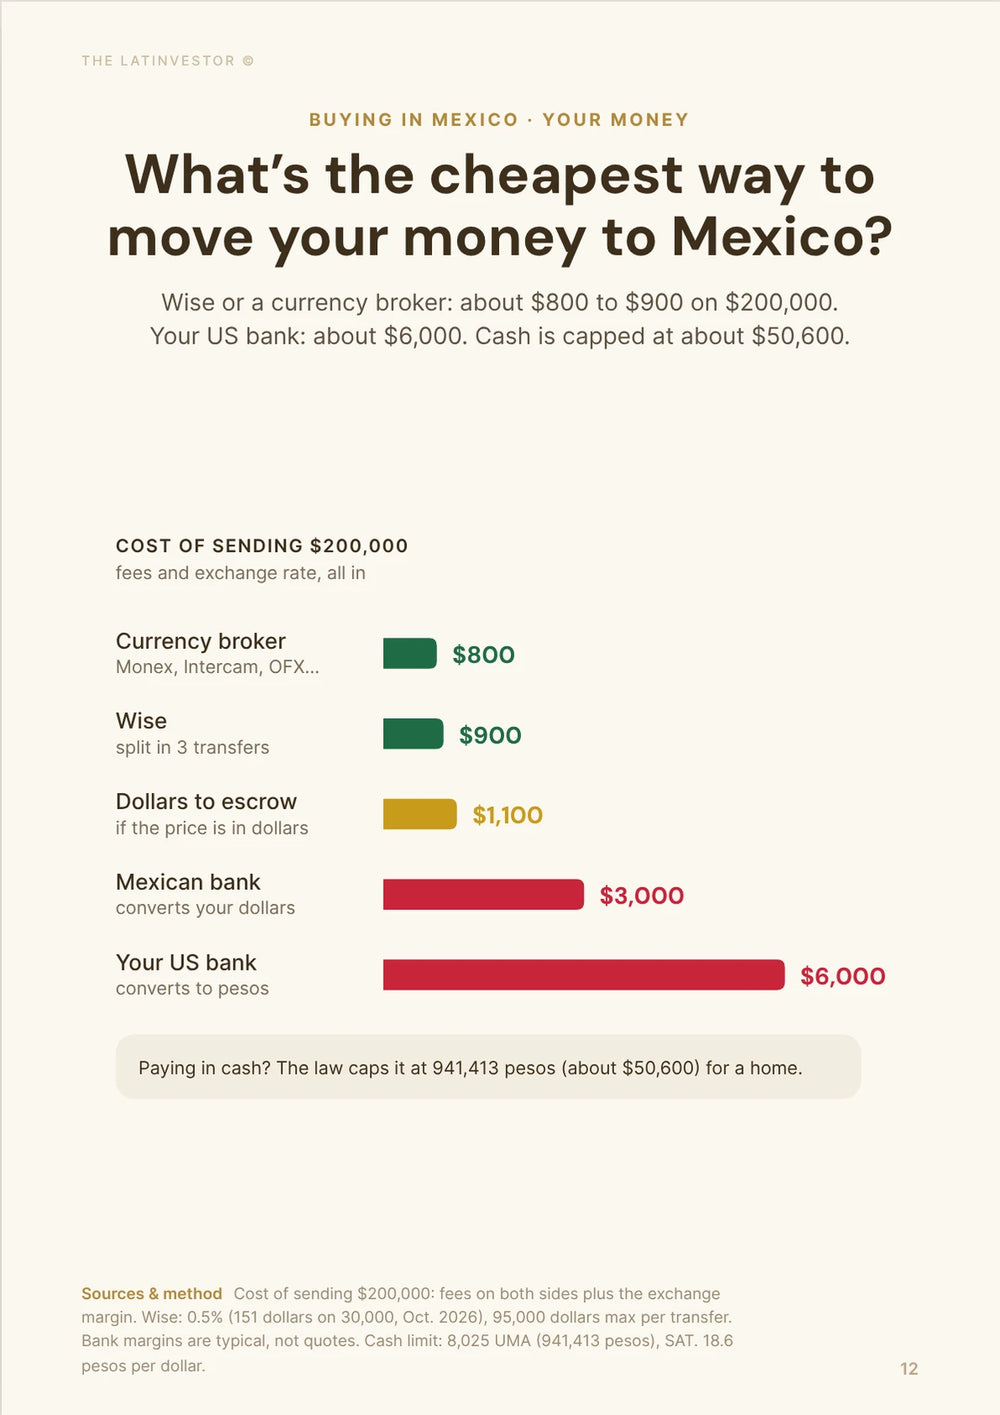
What to do: check whether the price is set in pesos or in dollars. Beach condos are often listed in dollars, inland homes in pesos. If the price is in pesos, agree on the exchange rate or the date it will be fixed in the contract, and convert with a currency specialist or your bank’s wire desk rather than accepting the default bank rate without comparing. If the price is in dollars, the exchange rate is the seller’s problem: a peso that keeps weakening makes their dollar price look high next to local peso listings, which gives you room to negotiate.
Can Americans rent out property they buy in Mexico?
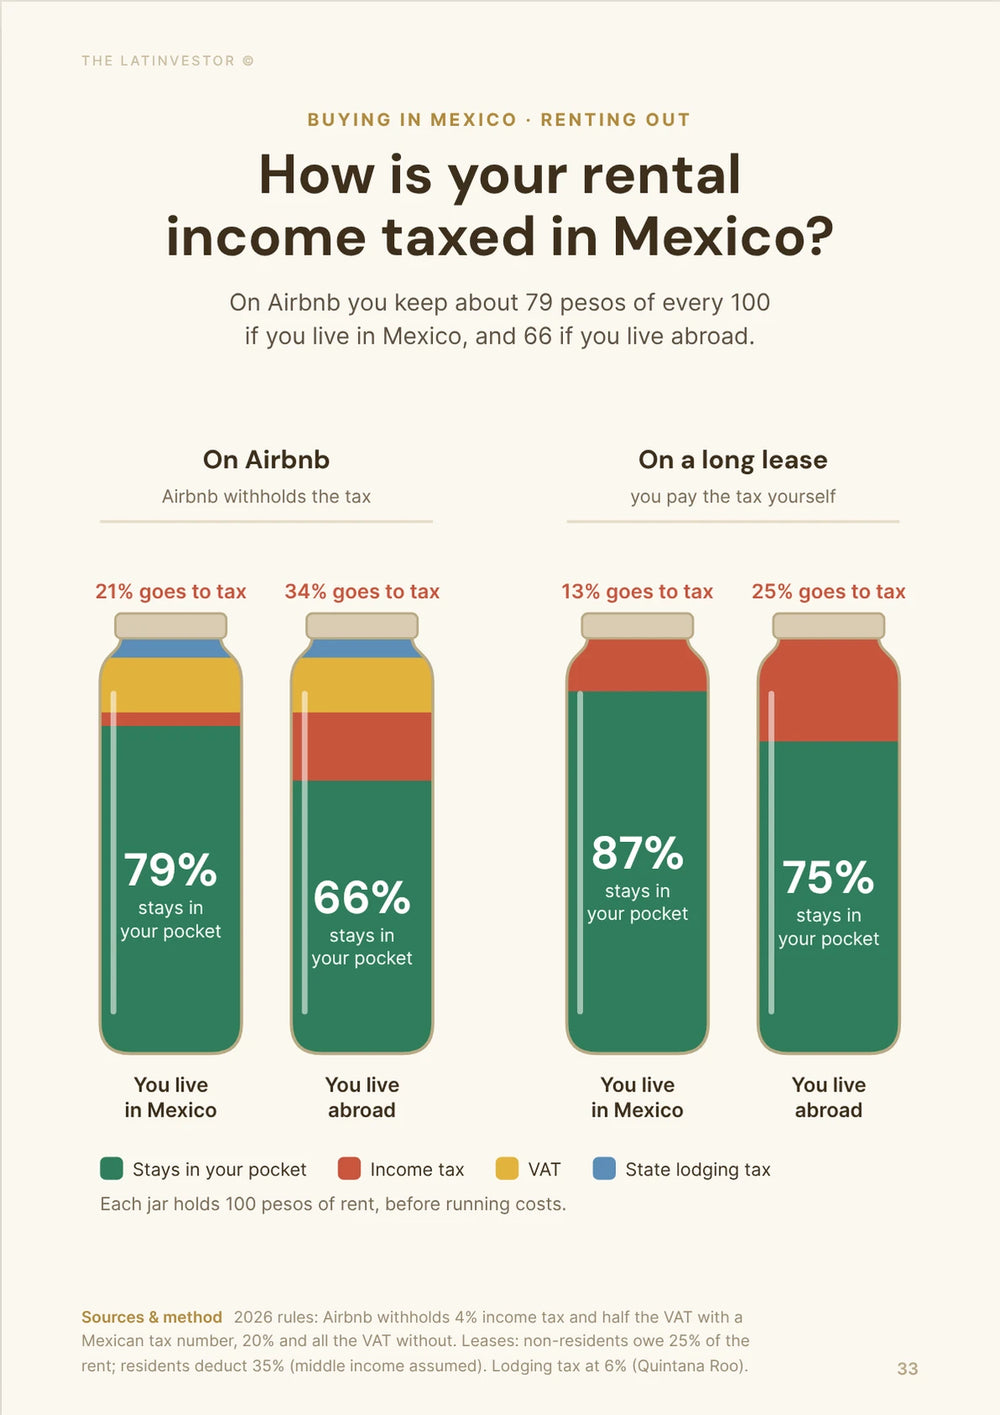
Yes. Americans can generally earn rental income from Mexican property they own, including property held through a fideicomiso, provided the specific rental activity complies with local, tax and condominium rules.
Mexico’s Foreign Investment Law allows a restricted-zone beneficiary to receive the fruits, products and economic returns generated by the property. The IRS’s Mexican land-trust ruling also used an example where the American beneficiary could occasionally rent the property and receive the rental income directly.
So the fideicomiso itself does not turn a coastal condo into a property that can only be used personally.
The real issue is whether the exact condo, house or municipality allows the rental model the buyer has in mind.
A condominium regime can restrict short stays. Local governments can impose registrations, taxes or operating rules. A building marketed heavily to investors can also change its internal rules later through the mechanisms available to the owners’ association.
Then comes Mexican tax, which agents’ revenue forecasts often leave out. A non-resident landlord pays 25% of the gross rent, with no deduction for expenses. On short stays, Airbnb and similar platforms withhold 4% of income tax if you give them a Mexican tax ID (RFC) and 20% if you don’t, and 16% VAT applies to lodging.
For a pure investment purchase, we would want the rental rules and the tax bill confirmed in writing before using projected Airbnb income to justify the price. Getting an RFC before the first booking is the cheapest fix available.
Can an American sell Mexican property and bring the money back to the United States?
Yes. Americans can sell Mexican property and transfer their proceeds, although Mexican and U.S. taxes can materially change the amount they ultimately keep.
Directly owned property can be sold through the normal Mexican conveyancing process. A fideicomiso beneficiary can also sell or assign the rights associated with the property through the trust structure.
There is no general rule forcing an American to keep the sale proceeds inside Mexico.
Taxes deserve more attention. A non-resident seller pays Mexican income tax either as 25% of the gross sale price, with no deductions, or up to 35% of the net gain if a Mexican legal representative files for you. On most homes that gained value modestly, the net-gain route costs far less, so arrange the representative before closing. The notary calculates and withholds the tax.
The main-home exemption (up to 700,000 UDIS, once every 3 years) is only for Mexican tax residents who can prove the home is where they live, so most Americans living in the United States won’t get it.
A U.S. citizen also remains within the U.S. tax system on worldwide income. The same economic gain can therefore matter on both sides of the border, although U.S. foreign-tax-credit rules may reduce double taxation when qualifying Mexican tax has already been paid.
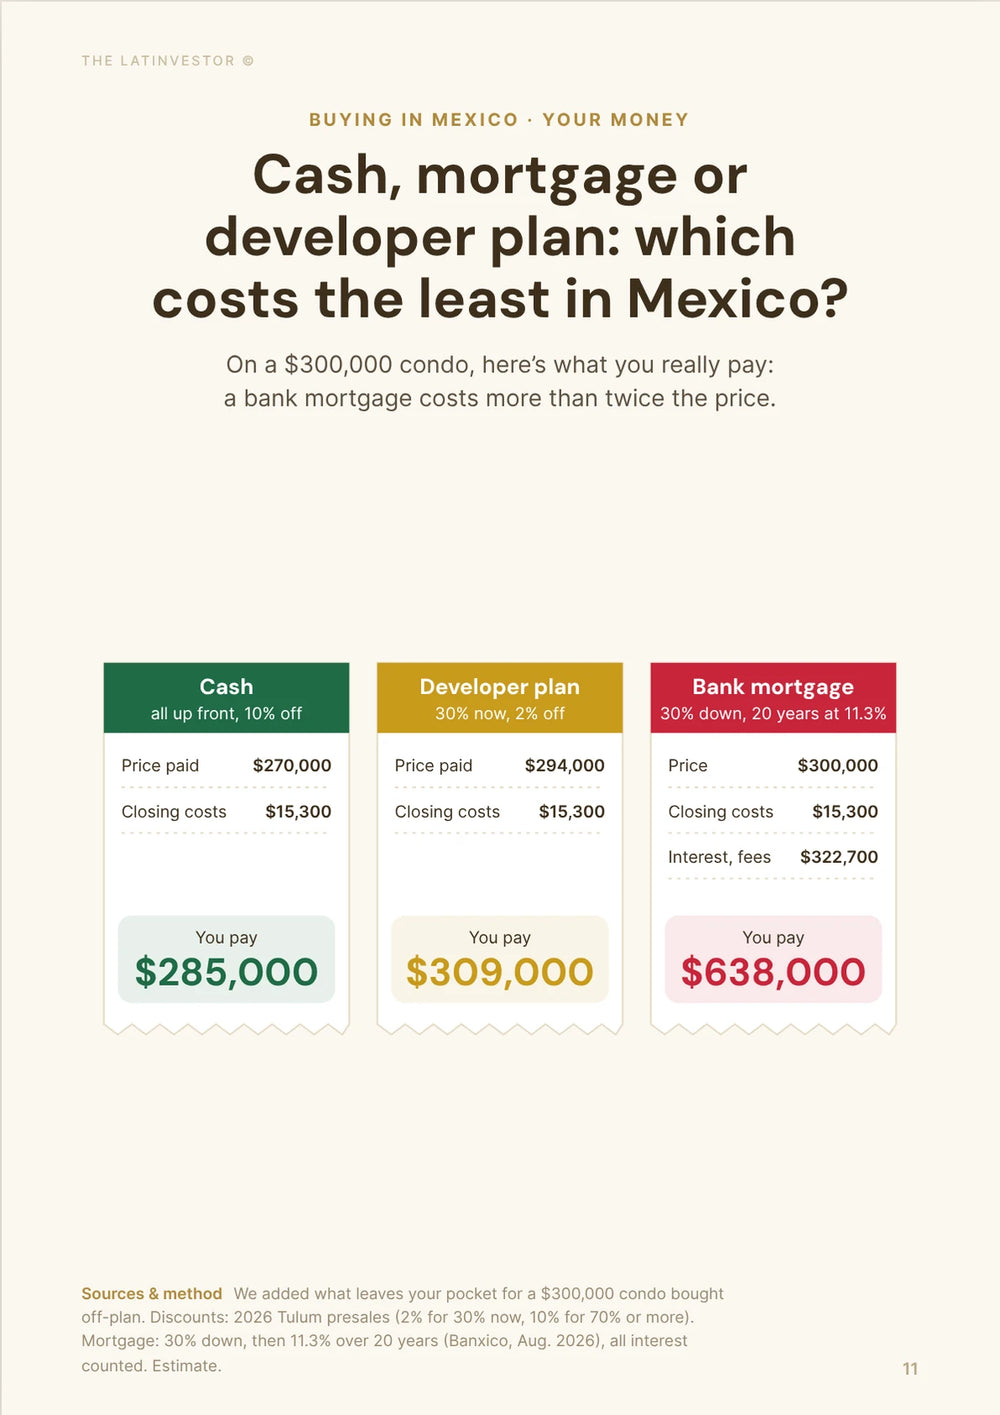
For investors, this can make the headline return misleading. A property bought for $250,000 and sold for $350,000 has not necessarily produced a clean $100,000 profit after acquisition costs, improvements, trust expenses, selling costs and taxes are included.
The ability to resell is straightforward. Calculating the real after-tax return takes more work.
Does a Mexican fideicomiso create a U.S. foreign-trust reporting nightmare?
Usually not for the standard Mexican land-trust arrangement described by the IRS, which the agency has specifically said does not count as a trust for U.S. federal tax purposes.
Revenue Ruling 2013-14 is unusually helpful here because it dealt directly with a U.S. person owning Mexican residential real estate in the restricted zone.
In the IRS example, the Mexican bank held legal title while the U.S. beneficiary controlled possession, paid property expenses and taxes, decided on improvements and could rent the home. The bank mainly followed instructions concerning title and received its annual fee.
The IRS concluded that this arrangement was not a trust under the federal tax definition it analyzed.
That removes one of the scarier assumptions Americans can make after hearing the words “Mexican bank trust.” A normal land fideicomiso does not automatically become the kind of foreign trust that triggers the U.S. reporting treatment associated with conventional offshore trusts.
We still would not extrapolate the ruling to every structure carrying the fideicomiso name. A more complicated arrangement containing different assets, powers or beneficiaries may need separate U.S. tax advice.
Rental income and capital gains also remain taxable issues even when the fideicomiso itself is not treated as a U.S. foreign trust.
What does an American have to report to the IRS for a Mexican home?
Less than most people fear: the home itself is not reported on Form 8938, but your Mexican bank accounts and any rental income are.
The IRS says plainly that foreign real estate held directly, including a personal residence or a rental property, is not a specified foreign financial asset for Form 8938. A standard fideicomiso is treated like direct ownership under Revenue Ruling 2013-14. A home held through a Mexican company is different: the company interest is reported.
Mexican bank accounts are where Americans slip. If the combined balance of your foreign accounts goes above $10,000 at any point in the year, you file an FBAR. Opening a peso account to pay the closing, the bank trust fees or a property manager often crosses that line without people noticing.
Rental income goes on your U.S. return like any other rental, and the Mexican tax withheld can usually be claimed as a foreign tax credit. Keep every Mexican tax receipt (CFDI) and the notary’s withholding statement: without them, you risk paying tax twice.
Is buying property in Mexico actually less secure than buying in the United States?
A properly titled and properly registered Mexican property can give an American a strong legal position, but buying casually in Mexico is far less forgiving than many foreign buyers expect.
The cleanest transactions are relatively easy to understand. The seller owns private property, the title history checks out, the notary formalizes the transfer, the required foreign-ownership structure is used and the resulting deed or trust rights are correctly registered.
Mexico also has institutions specifically built around those transactions. Foreign Ministry procedures currently exist for direct foreign ownership and restricted-zone fideicomisos. Public Registries record private-property rights. The Registry of Agrarian Land deals with ejidal and communal rights.
Risk is concentrated in deals that cross those systems awkwardly or bypass them altogether.
The clearest example is social property. As seen above, the latest federal agrarian figures still put about 51% of Mexico’s territory in ejidos and agrarian communities. That does not make half of Mexican homes problematic, since much of that land is rural and many urban properties have perfectly ordinary private title. It does show why land history deserves real attention.
Pre-construction projects create another type of risk. Here the buyer may be paying before the finished property and final individual title exist. Developer history, permits, construction progress, escrow arrangements, cancellation clauses and the exact contract become far more important than they are in a completed resale.
Mexico is not inherently an unsafe place for Americans to own real estate. Formal transactions with verified rights are a different world from deals where the buyer relies on the seller’s promises because the price looks attractive.
What should Americans be most suspicious of when buying Mexican property?
Americans should be most suspicious when a seller wants them to accept an incomplete legal position today because proper title, registration or authorization will supposedly arrive later.
That pattern appears in several forms.
A cheap land parcel may still have ejidal status while the promoter promises future privatization. A pre-construction seller may talk extensively about projected appreciation while providing little clarity on permits or delivery protections. Someone claiming ownership may offer a private contract or power of attorney instead of completing the normal notarized transfer.
Those situations are much more concerning than the existence of a fideicomiso.
The fideicomiso can look intimidating because Americans rarely use anything similar when buying a normal home in the United States. Yet the mechanism is written into Mexican foreign-investment law, administered by the Foreign Ministry, handled by regulated Mexican banks and used routinely in major coastal markets.
A questionable title does not gain that legitimacy merely because a persuasive seller says the paperwork is normal for the area.
Mexico’s consumer authorities have repeatedly advised property buyers to verify the seller’s authority and documentation and to complete the acquisition through the proper notarized process rather than relying solely on private agreements.
If the paperwork is unusual, it needs a legal explanation that can be independently verified. Reassurance from the person receiving the money is not enough.
So, can Americans buy property in Mexico?
Yes. Americans can legally buy property across Mexico today, and the claim that foreigners are generally prohibited from owning Mexican real estate is wrong.
Outside the restricted coastal and border zones, Americans can acquire direct ownership through the current federal process for foreign buyers. Inside those zones, residential purchases normally use a fideicomiso, giving the American beneficiary broad practical control while a Mexican bank holds legal title.
The latest government procedures continue to support both routes. Mexico has recently simplified parts of the Article 27 process rather than dismantling it, and the Foreign Ministry still issues restricted-zone trust permits with terms of up to 50 years that can be extended.
For an American deciding whether to buy, the foreign-ownership rules are fairly predictable. The harder work is property-specific: confirming private title, spotting ejidal history, checking liens and registration, understanding condominium or rental restrictions, reviewing pre-construction risks and making sure the transaction reaches a valid notarized closing.
Our final judgment is clear. Americans can absolutely buy Mexican property, including beachfront homes. A properly structured purchase is legally routine. The money questions in 2026 are the trust fees, the Mexican tax on rent and resale, and the exchange rate. The deals worth avoiding are the ones where the property itself cannot survive serious due diligence.
Our methodology
This article answers whether, where and how an American can own property in Mexico, and what it costs in fees and taxes on both sides of the border. We split the question into its parts: where the property is, whether the buyer holds direct title or a fideicomiso, whether the land is private or agrarian, and how rent, resale and money transfers are taxed.
For the ownership rules, we used Mexico’s Constitution, the Foreign Investment Law and its regulations, and checked them against the procedures and fee schedule the Foreign Ministry (SRE) currently publishes, updated in September 2026. Bank trust fees come from a 2026 broker comparison and are estimates, not official bank tariffs. Closing-cost ranges are planning estimates from a 2026 notary-fee guide.
For ejidal land we used the Agrarian Law and 2026 federal agrarian-program rules based on Registry of Agrarian Land data. For Mexican taxes we used the Income Tax Law (articles 93, 113-A, 113-C, 158 and 160) and SAT guidance. For the U.S. side we used IRS Revenue Ruling 2013-14, the IRS pages on Form 8938 and FBAR, Publication 514, and the 2026 proposed rules on the remittance tax. Home-price trends come from the SHF index, and exchange-rate history and forecasts from BBVA Research, the Banxico analyst survey and Citi.
We checked these figures in October 2026. Conversions use about 18.6 pesos per US dollar and 20.9 pesos per euro.
Limits: residency thresholds are set and converted by each consulate, so confirm the figure with the one where you will apply. Bank fees vary by property and are negotiable. Tax outcomes depend on your residency and the method the notary applies, so get a written estimate before closing. This is not legal or tax advice.
Key sources used for this analysis include: the Mexican Constitution, Article 27, the Foreign Investment Law, the Foreign Investment Law regulations, SRE’s 2026 Article 27 costs, SRE guidance for foreign acquisition outside the restricted zone, SRE’s restricted-zone fideicomiso procedure, SRE’s fideicomiso extension procedure, the 2026 Diario Oficial Article 27 simplification, SRE guidance for Mexican companies buying for non-residential use, Homia’s 2026 fideicomiso bank-fee comparison, Compass Abroad on 2026 notary and closing costs, Tandazo on company formation costs, the Agrarian Law, the 2026 agrarian-program rules using RAN/PHINA data, Registry of Agrarian Land statistics, Profeco guidance on buying a used home, Profeco guidance on home purchases, a 2026 Mexican consulate visa listing, NorthAmericans on 2026 residency solvency thresholds, SAT guidance on selling real estate, Income Tax Law article 160, Income Tax Law article 158, Income Tax Law article 113-A, Income Tax Law article 93, IRS Revenue Ruling 2013-14, IRS questions and answers on Form 8938, IRS on the FBAR, IRS Publication 514 on the Foreign Tax Credit, Greenback on the 2026 remittance tax rules, the SHF home price index, Calcu.mx exchange-rate history and BBVA Research’s September 2026 Mexico outlook.