

Summary
There's no single best place to buy in Uruguay: it depends on what you want. For rental income, central Montevideo (Ciudad Vieja, Cordón, Centro) gives the best gross yields, around 6% to 7% on asking prices; for resale and lifestyle, Pocitos, Punta Carretas and Carrasco (USD 3,950 to 4,370 per m²); for a summer house, Punta del Este, where apartments list at a median of USD 3,638 per m².
The priciest apartments in Montevideo are in Carrasco (USD 4,370 per m²), Parque Rodó (4,347) and Punta Carretas (4,184), according to INGAR's September 2026 asking-price report. On the coast east of Punta del Este, apartments in Manantiales (USD 5,650) and José Ignacio (USD 5,000) cost more still.
Among the barrios with published data, Ciudad Vieja is the cheapest at USD 2,157 per m², about half of Carrasco. A 45 m² one-bedroom there lists around USD 97,000, against roughly USD 145,000 in Cordón.
Yields move the other way from prices: Ciudad Vieja shows about 7.0% gross, Punta Carretas and Parque Rodó about 5.1%. After the 10.5% rental tax withholding, vacancy, management and yearly property taxes, expect roughly 3.3% to 4.7% net.
Airbnb doesn't beat a normal lease on average. In Montevideo, the typical listing made about UYU 312,000 (USD 7,780) in the 12 months to September 2026 at 44% occupancy (AirROI), less than a year of rent on a Pocitos one-bedroom at UYU 29,000 a month.
For long-term tenants, the steady demand sits in Cordón, Centro, Pocitos and Buceo, where 1-bedrooms list at about UYU 25,000 to 29,000 a month. Montevideo asking rents fell 3.9% over the year to August 2026, so don't plan on rent rises above inflation (4.68%).
The up-and-coming corridor is still Cordón: 26.4% of all promoted-housing (vivienda promovida) sales declared in Montevideo since the scheme began. The bus-rapid-transit plan agreed in March 2026 for 18 de Julio could help Centro and Cordón over 2026-2029.
What to avoid: generic rental towers in Punta del Este sold on peak-season income, and outer Montevideo barrios where a high headline yield hides vacancy and slow resale. We found no reliable 2026 price per m² for areas like Casabó or Manga.
Prices are flat in real terms. ANV promoted-housing prices rose 5.1% in dollars in Montevideo and 9.3% in Maldonado over the 12 months to April 2026, but fell 2.2% in Montevideo and stayed roughly flat in Maldonado in inflation-indexed units (UI).
Locals and expats point to the same top addresses: Pocitos, Punta Carretas and Carrasco in Montevideo, the Península and Playa Mansa in Punta del Este. If you buy to rent out, start from the rent you can verify, at a price per m² close to the barrio median, and budget about 6% in buying costs without an agent and 9.5% with one.


What does a square meter cost in Uruguay's main areas?
Which areas in Uruguay have the highest property prices per square meter?
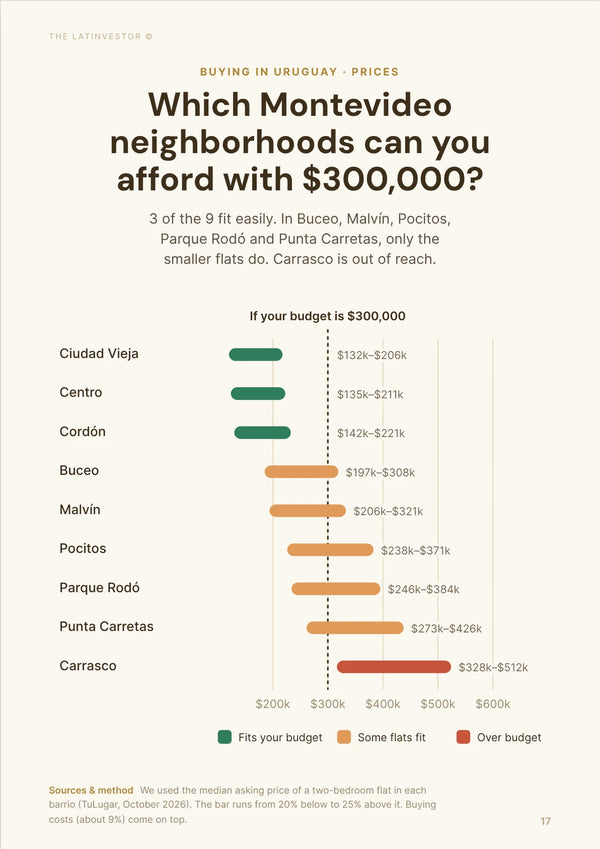
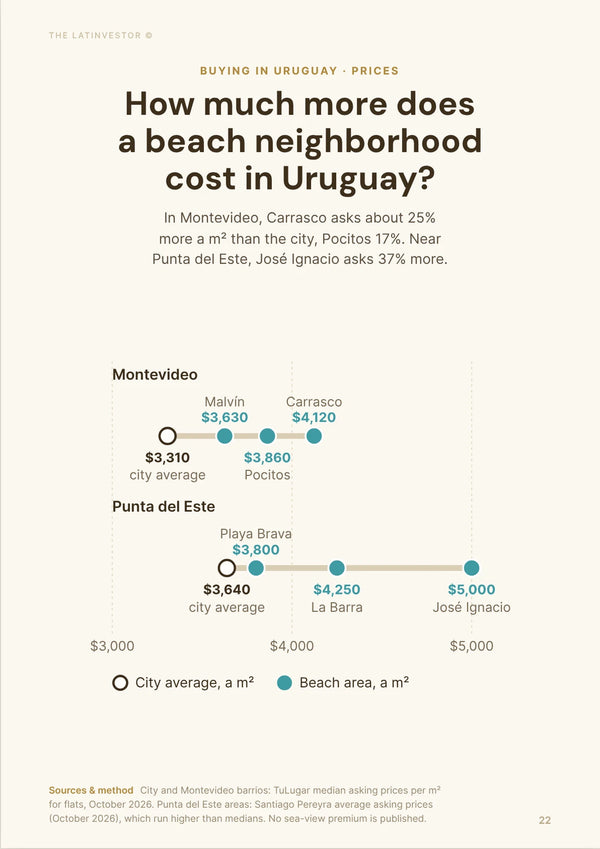
In Montevideo, the most expensive apartments are in Carrasco (median asking price USD 4,370 per m²), Parque Rodó (USD 4,347), Punta Carretas (USD 4,184) and Pocitos (USD 3,956), according to INGAR's September 2026 report. The city's median across barrios is USD 2,841 per m².
On the coast, Punta del Este apartments list at a median of USD 3,638 per m² (TuLugar, October 2026). The beach villages east of town cost more, for apartments: Manantiales around USD 5,650 per m², José Ignacio USD 5,000 and La Barra USD 4,250 (Santiago Pereyra listings survey, October 2026). Playa Brava sits around USD 3,800, Playa Mansa USD 3,600 and the Península USD 3,350.
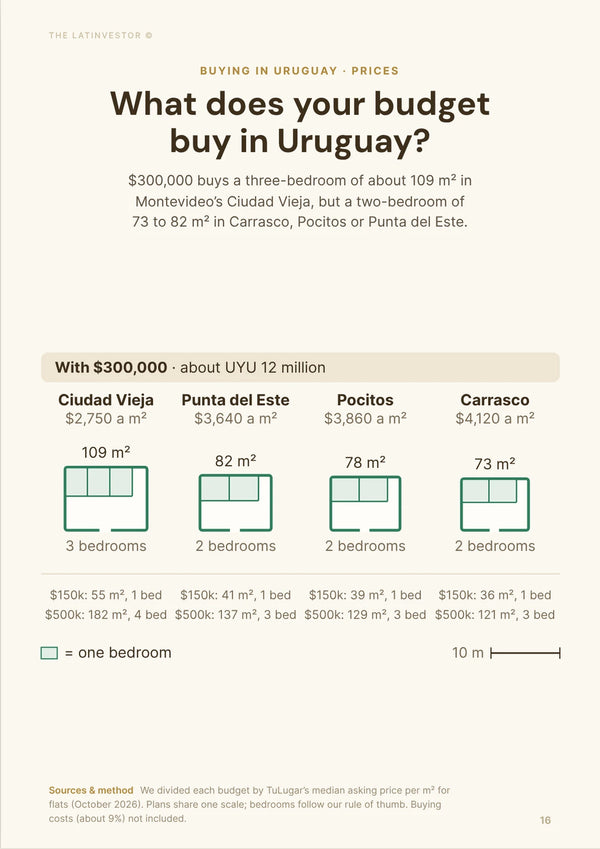
All these are asking prices, not sale prices. A 70 m² two-bedroom in Pocitos at the median lists around USD 277,000; the same size in Punta Carretas around USD 293,000.
Why these areas cost more:
- Carrasco: low-rise, leafy, family-oriented, close to the airport and international schools, but you'll need a car.
- Punta Carretas: the Rambla, the golf course, the shopping mall, and everything within walking distance.
- Pocitos: Montevideo's best-known beach, dense apartment towers, shops and cafés on every block.
- José Ignacio: a small, high-end seaside village with luxury villas and very little supply.
Which areas in Uruguay have the most affordable property prices?
Among the Montevideo barrios with published data, the cheapest is Ciudad Vieja at USD 2,157 per m² (INGAR, September 2026; TuLugar shows USD 2,750 in October 2026, a different sample). Then come Centro (USD 3,026) and Cordón (USD 3,228).
At those prices, a 45 m² one-bedroom lists around USD 97,000 in Ciudad Vieja and USD 145,000 in Cordón. New promoted-housing units sold in Montevideo averaged USD 2,411 per built m² over the 12 months to April 2026 (ANV), which is a real sale price, not an asking price.
Outer barrios like Reducto, Maroñas, Punta de Rieles or Colón are cheaper still, but we found no reliable 2026 price per m² for them, so we won't put a number on it. Check recent sales with a local escribano (notary) before you trust a listing.
The trade-offs are real: in Ciudad Vieja, building quality varies a lot and some streets go quiet at night; further out, you'll wait longer for good tenants and resale is slower.
 Uruguay Property Prices

Which areas in Uruguay give the best rental yields?
Which neighborhoods in Uruguay have the highest gross rental yields?
In Montevideo, the highest estimated gross yields are in Ciudad Vieja (about 7.0%), Centro and Cordón (about 6.2% each), and Buceo (5.6%), according to INGAR's September 2026 estimates on asking prices. The city median is 6.1%.
The prime coastal barrios yield less because prices are higher: Carrasco 5.5%, Malvín 5.4%, Pocitos 5.3%, Punta Carretas and Parque Rodó 5.1%. In Punta del Este, a long-term lease gives about 4% to 5.5% gross (Caetano Inmobiliaria, July 2026).
Gross isn't what you keep. Take off the 10.5% IRNR withholding on gross rent (12% of taxable rent, DGI), about one month of vacancy, 8% management, and roughly 0.4% of the price a year for contribución inmobiliaria, Impuesto de Primaria and insurance. That's our estimate of net yield:
| Barrio (Montevideo) | Asking price per m² (Sept. 2026) | 1-bed rent (Oct. 2026) | 2-bed rent (Oct. 2026) | Gross yield (INGAR) | Net yield (our estimate) |
|---|---|---|---|---|---|
| Ciudad Vieja | USD 2,157 | UYU 26,000 (about USD 650) | UYU 30,000 (about USD 750) | 7.0% | 4.7% |
| Centro | USD 3,026 | UYU 24,900 (about USD 620) | UYU 30,000 (about USD 750) | 6.2% | 4.1% |
| Cordón | USD 3,228 | UYU 27,000 (about USD 675) | UYU 33,900 (about USD 845) | 6.2% | 4.1% |
| Buceo | USD 3,657 | UYU 25,000 (about USD 625) | UYU 33,700 (about USD 840) | 5.6% | 3.7% |
| Carrasco | USD 4,370 | UYU 38,250 (about USD 955) | UYU 50,000 (about USD 1,250) | 5.5% | 3.6% |
| Malvín | USD 3,807 | UYU 29,000 (about USD 725) | UYU 40,000 (about USD 1,000) | 5.4% | 3.6% |
| Pocitos | USD 3,956 | UYU 29,000 (about USD 725) | UYU 40,250 (about USD 1,000) | 5.3% | 3.5% |
| Punta Carretas | USD 4,184 | UYU 34,500 (about USD 860) | UYU 42,000 (about USD 1,050) | 5.1% | 3.3% |
| Parque Rodó | USD 4,347 | UYU 28,000 (about USD 700) | UYU 36,550 (about USD 910) | 5.1% | 3.3% |
Portal reports sometimes show double-digit yields in outer barrios like Manga, Casabó or Colón. We couldn't verify any 2026 figure there, and a yield that high usually means the price is low for a reason: slow resale, tenants who pay late, longer gaps between leases.
Why the central barrios do best:
- Ciudad Vieja: the lowest prices per m² in the data, with offices and tourists nearby.
- Cordón: students and young workers near the universities, lots of new small units.
- Centro: the 18 de Julio commercial axis, offices and every bus line.
- Buceo: coastal, with shopping and offices, at a lower price than Pocitos next door.
 70+pages
Which areas in Uruguay work best for short-term rentals?
Which neighborhoods in Uruguay perform best on Airbnb?
In Montevideo, the average Airbnb listing ran at 44% occupancy and UYU 2,936 (USD 73) a night over the 12 months to September 2026, for about UYU 312,000 (about USD 7,780) in yearly revenue (AirROI). Pocitos, Punta Carretas and Ciudad Vieja are where tourists and business travelers stay, but AirROI doesn't publish barrio-level figures.
That average is less than a year of rent on a Pocitos one-bedroom (UYU 29,000 a month, so UYU 348,000 a year), before cleaning, platform fees and furniture. In Montevideo, Airbnb only pays if your unit does clearly better than average.
Punta del Este is a different market: 34.6% occupancy over the year to July 2026, USD 192 a night, about USD 11,445 a year (AirROI). From December to February, occupancy rises to 50.6% at USD 221. The villages earn more per listing but fill less: La Barra 27.4% at USD 403 (USD 16,599 a year), José Ignacio 29.7% at USD 394 (USD 17,232).
Why these areas work:
- Pocitos: beach, restaurants, easy airport access, guests all year.
- Punta Carretas: mall, golf course, Rambla, business travelers.
- Península (Punta del Este): port, restaurants, nightlife, and you don't need a car in summer.
- Playa Mansa: calmer water, families, many buildings right on the beach.
Which tourist areas in Uruguay are becoming oversaturated with short-term rentals?
The signs of oversaturation show up in secondary Punta del Este locations away from the beach, in generic towers sold to foreign buyers on summer income, and in some inland developments near José Ignacio that you can't walk anywhere from.
Punta del Este had 2,807 active Airbnb listings over the year to July 2026, and the average one was booked about one night in three (34.6%, AirROI). Many are near-identical one- and two-bedroom units that compete only on price.
The clearest warning sign: owners cutting rates hard in March or November just to get any booking. If a building's listings all look the same, yours will too.
Which areas in Uruguay are best for long-term rentals?
Which neighborhoods in Uruguay have the strongest demand for long-term tenants?
The steadiest long-term demand is in Cordón, Centro, Tres Cruces and La Blanqueada in Montevideo, where universities, hospitals, offices and the main bus terminal keep tenants coming. Pocitos and Buceo add young professionals and couples.
The market is soft right now: Montevideo asking rents were down 3.9% over the year to August 2026 (El País / Inmuebles Data). We found no reliable vacancy or time-to-rent figure by barrio; a well-priced unit in these areas tends to lease fastest, an overpriced one sits.
Who rents where:
- Cordón: students and young workers who want to be near the universities and nightlife.
- Tres Cruces: commuters who use the bus terminal and work downtown.
- Centro: public employees, small business owners, tenants on a budget.
- La Blanqueada: hospital staff and families who want more space at a lower price.
What these barrios have in common: you can walk to work, school and shops, and live without a car.
What are the average long-term monthly rents by neighborhood in Uruguay?
The average rent on all current leases in Uruguay was UYU 22,400 (about USD 560) a month in August 2026 (INE, 150,909 contracts, all property types). New listings ask more: in Montevideo, one-bedrooms averaged UYU 29,400 (about USD 730) and two-bedrooms UYU 40,100 (about USD 1,000) (El País / Inmuebles Data, August 2026).
By barrio, median advertised one-bedroom rents in October 2026 went from UYU 24,900 (USD 620) in Centro and UYU 25,000 (USD 625) in Buceo to UYU 34,500 (USD 860) in Punta Carretas and UYU 38,250 (USD 955) in Carrasco (Cambio Uruguay).
For a two-bedroom, expect around UYU 30,000 (USD 750) in Centro or Ciudad Vieja, UYU 33,700 to 33,900 (USD 840 to 845) in Buceo or Cordón, and UYU 40,000 to 42,000 (USD 1,000 to 1,050) in Pocitos, Malvín or Punta Carretas.
The top end is Carrasco, at about UYU 50,000 (USD 1,250) for a two-bedroom. Leases are usually priced in pesos and adjusted once a year.
 70+pages
Which areas in Uruguay are up and coming?
Which neighborhoods in Uruguay are gentrifying and attracting new investors?
Cordón is the clearest case: it accounts for 26.4% of all promoted-housing (vivienda promovida) sales declared in Montevideo since the scheme began, against 7.0% for Centro (ANV, to May 2026). Tres Cruces, Barrio Sur and La Comercial are following the same pattern, with new small-unit buildings replacing old houses.
Montevideo concentrates 20,904 of the 26,242 promoted units sold nationally (about 80%). In dollars, promoted-housing prices in the city rose 5.1% over the 12 months to April 2026, but fell 2.2% in inflation-indexed units (UI).
On the coast, La Barra and Atlántida get mentioned as next in line. We found no reliable 2026 price-growth figure for either, so treat any "next José Ignacio" pitch with care.
Which areas in Uruguay have major infrastructure projects planned that will boost prices?
The project with the most direct effect on housing is in Montevideo: in March 2026, the Intendencia de Montevideo signed an agreement to overhaul metropolitan transport with bus rapid transit along 18 de Julio and the main corridors, with works planned over 2026-2029. Centro, Cordón and Ciudad Vieja sit right on it.
In Maldonado, the departmental government has a 2026-2030 works plan for roads, sidewalks and lighting that covers Punta del Este, La Barra, José Ignacio and Pinares. Useful, but not the kind of project that moves prices on its own.
The Casupá dam for Montevideo's water supply is moving slowly: OSE launched the international tender, works are expected in 2027, and the contract will only be awarded after environmental approval (El Observador, June 2026). It matters for the city's water security, not for any one barrio's prices.
We found no reliable study measuring how much Uruguayan prices rise after a project like this, so we won't give a figure. Disruption during works can also hurt rents for a while.
Which areas in Uruguay should a property investor avoid?
Which neighborhoods in Uruguay with lots of problems should I avoid and why?
The riskiest places for a foreign investor are the outer Montevideo barrios sold on very high yields, like Manga, Casabó and Colón Sureste, and the generic rental towers of Punta del Este.
Specific issues:
- Manga: more insecurity, few shops and services, longer gaps between tenants.
- Casabó: uneven building quality, tenants who pay late, few property managers.
- Colón Sureste: far from central services, weak resale market.
- Generic Punta del Este towers: lots of similar units, 34.6% average annual occupancy, high building fees.
Nationally, reported robberies fell 2.1% between the third quarters of 2025 and 2026 (Ministerio del Interior), but there's no reliable crime rate by barrio. Visit at night, talk to the building's administrator, and ask a local escribano how fast similar units resold.
Which areas in Uruguay have stagnant or declining property prices?
In real terms, most of the market is flat. ANV promoted-housing prices fell 1.3% nationally and 2.2% in Montevideo in inflation-indexed units over the 12 months to April 2026, and stayed roughly flat in Maldonado, even though they rose 6.3%, 5.1% and 9.3% in dollars.
Within that, the weakest spots are secondary Punta del Este locations away from the beach, older central Montevideo buildings with high upkeep, and oversupplied investment towers.
Why they lag:
- Secondary Punta del Este: too many similar units competing on price, demand packed into three months.
- Older central Montevideo buildings: rising maintenance costs, no elevator or garage, competition from new promoted units.
- Generic investment towers: bought on Airbnb projections that didn't happen, building fees that eat the income.
 70+pages
Which areas in Uruguay have the best long-term appreciation potential?
Which areas in Uruguay have appreciated the most recently?
The only official long series covers promoted housing: in Montevideo, it went from USD 1,955 per built m² in the first half of 2021 to USD 2,477 in January to April 2026, up 26.7% in five years, or about 4.8% a year in dollars (ANV). In Maldonado, it rose 9.3% in dollars over the last 12 months.
There's no official series by barrio. From asking prices and what brokers report, the areas that held value best are coastal Montevideo (Pocitos, Punta Carretas), the Cordón promoted-housing corridor, and the top of the Maldonado coast (José Ignacio, Manantiales).
What they share: little land left near the beach, steady tenant demand, and new buildings that keep improving the street.
Which neighborhoods in Uruguay are expected to see price growth in coming years?
The best bets for growth are Cordón, Tres Cruces, Parque Batlle and La Blanqueada in Montevideo, plus La Barra and Atlántida on the coast. Nobody publishes a credible forecast by barrio, so we don't give one.
What could drive them:
- Cordón and Tres Cruces: more promoted-housing buildings and the 18 de Julio bus-rapid-transit works.
- Ciudad Vieja: the lowest price per m² in the data (USD 2,157), with room to catch up if renovation continues.
- La Barra: spillover from Punta del Este, but prices are already at USD 4,250 per m².
- Atlántida: cheaper beach living within an hour of Montevideo.
The main catalyst is still Law 18.795 (promoted housing): its tax breaks keep pulling new projects into the same corridors. For the country, our estimate is +3% to +6% in dollars over the next 12 months and +3% to +5% a year over the medium term, close to inflation (4.68% over 12 months to September 2026), not a boom.
Don't pick an area "for the residency": a home above UI 3.5 million (about USD 580,000) plus 60 days a year still makes you a tax resident, but since Law 20.446 (January 2026) the 11-year tax holiday for new residents needs more than 183 days a year or property above UI 12.5 million (about USD 2.1 million), so a USD 600,000 flat in Punta Carretas no longer gets you the holiday, and buying never gives you a residence permit.
What do locals and expats really think about Uruguay's areas?
Which areas in Uruguay do local residents consider the most desirable to live?
Locals put Carrasco, Punta Gorda, Pocitos and Punta Carretas at the top in Montevideo, and the Península, Playa Mansa and Pinares in Punta del Este for those who want to live by the sea all year.
Why:
- Carrasco: low density, the best schools, embassies, a suburban feel close to the city.
- Punta Gorda: quiet coastal streets, established families, green spaces.
- Pocitos: the beach, restaurants, everything on foot.
- Punta Carretas: the mall, the golf course, the Rambla, a prestige address.
The people living there are mostly established professionals, business owners, diplomats and upper-middle-class families. The low yields in these barrios (5.1% to 5.5% gross) tell you the same thing: people pay up to live there.
Locals and foreign buyers mostly agree. Locals care more about schools and family life; foreigners about walkability and furnished rentals.
Which neighborhoods in Uruguay have the best reputation among expat communities?
Expats tend to settle in Pocitos, Punta Carretas, Ciudad Vieja and Carrasco in Montevideo.
Why:
- Pocitos: the most furnished rentals, English easy to get by with, beach life.
- Punta Carretas: upscale shops, close to embassies, everything on foot.
- Ciudad Vieja: cheaper restored apartments, old buildings, cultural life.
- Carrasco: families, international schools, quiet streets.
Argentines are by far the largest foreign group in the beach market, an estimated 50% to 55% of buyers in Maldonado (local brokers, June 2026). In Montevideo, you'll also meet Brazilians, Americans and Europeans, many of them remote workers, retirees or people posted by their company.
Which areas in Uruguay do locals say are overhyped by foreign buyers?
Locals often point to generic investment towers in Punta del Este, some developments sold as "the next José Ignacio," and new Montevideo projects sold mainly on Airbnb income.
Why locals think they're overpriced:
- Generic Punta del Este towers: sold on peak-season income, while the average listing fills 34.6% of the year.
- "Next José Ignacio" areas: priced like the original without its village center or its beach.
- Airbnb-led Montevideo projects: pro-formas above the city's 44% average occupancy.
Foreign buyers see the marketing, the amenities and a familiar developer brand. Locals look at how fast units resell and what they really rent for, and often conclude the premium isn't worth it.
Which areas in Uruguay are considered boring or undesirable by residents?
Residents commonly see the outer barrios like Manga, Casabó, Las Acacias and Colón Sureste as boring or undesirable. The low prices there reflect what's on offer, not a hidden opportunity.
What residents say:
- Manga: few restaurants, little going on at night, a long trip to central Montevideo.
- Casabó: industrial feel, few green spaces or places to meet.
- Las Acacias: purely residential, few services on foot, you need a car.
- Colón Sureste: far from the beaches, little commerce, a place "just for sleeping."
Our methodology
This article compares the main areas to buy in Uruguay (Montevideo barrios and Punta del Este zones) on price per m², rents, gross and net yields, short-term rental results, recent price changes, and what locals and expats think of them.
Prices come from official sale data first, the Agencia Nacional de Vivienda (ANV) for promoted housing and the INE for current leases, then from asking-price portals: INGAR (September 2026) and TuLugar (October 2026) for barrio medians, the Santiago Pereyra survey for Punta del Este zones, and Cambio Uruguay and El País / Inmuebles Data for rents. Short-term rental figures all come from one provider, AirROI.
Tax and residency rules come from the DGI (Dirección General Impositiva) and Law 20.446. Net yields are our own calculation: gross rent minus the 10.5% IRNR withholding, about one month of vacancy, 8% management and about 0.4% of the price a year in property taxes and insurance.
We checked these figures in October 2026. Peso amounts are converted at about 40.1 pesos per US dollar and 45 pesos per euro (BCU, October 2026). Property is priced in dollars in Uruguay, while long-term rents are paid in pesos, so a yield in dollars also moves with the exchange rate.
Limits: portal prices are asking prices, not sale prices, and each portal samples differently (INGAR and TuLugar don't give the same figure for the same barrio). There's no official price series by barrio, no reliable vacancy rate by area, and no 2026 figure we could verify for outer barrios like Manga or Casabó, so we left those without numbers.
Key sources used for this analysis include INGAR, TuLugar, Agencia Nacional de Vivienda (ANV), Instituto Nacional de Estadística (INE), Cambio Uruguay, AirROI, Santiago Pereyra Inmobiliaria, Dirección General Impositiva (DGI), El Cronista, Intendencia de Montevideo and Banco Central del Uruguay (BCU).