
Summary
No. A weak Buró de Crédito score no longer cuts a standard Infonavit loan: since 2025, Infonavit releases 100% of the amount it calculates for you, whatever your rating. It repeated this in October 2026.
The old rule was real. Before 2025, a weak credit file could cut what you received to roughly 80% or 90% of your calculated amount.
Infonavit still checks the bureau, but only for three red flags: fraud, a wrong death record and extreme over-indebtedness.
"100%" means 100% of your own amount, not the headline maximum of about MXN 2.94 million. That depends on your salary, age, term (up to 30 years) and Housing Subaccount savings.
Points matter more than your Buró score. The 100-point T100 model now covers low-cost homes of around MXN 600,000, but the 1,080-point precalification is still used for bigger loans, reportedly on homes above about MXN 800,000.
Vivienda para el Bienestar is the easy door: earn under two minimum wages, have no active Infonavit mortgage and no home. By September 2026, 667,000 homes were contracted out of 1.8 million, but only 89,000 had been handed to families.
Other debt only becomes a problem when it eats your repayment capacity. Infonavit rates run from 3.69% to 10.45% depending on salary, well below the 11.31% banks quote on average.
A thin credit file is not a bad one. Infonavit judges you mostly on your formal job and contribution history.
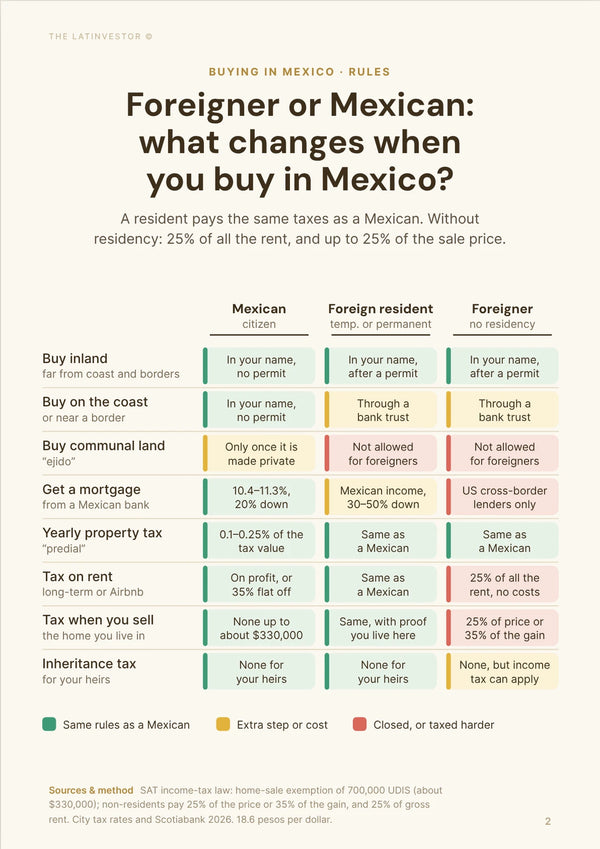
Foreigners can use Infonavit only as formal workers in Mexico with an IMSS number and employer contributions. An investor living abroad cannot.
Once a bank is involved, credit counts again. With Cofinavit or Apoyo Infonavit, the bank decides on its share, and banks granted loans at 9.99% on average in June 2026.
So don't spend months fixing a mediocre score first. Check your precalification and amount in Mi Cuenta Infonavit, and only clean up your file if it has a red flag or if you'll need a bank to close the gap.

Did Infonavit really stop cutting loans for bad Buró scores?
Yes. Since 2025, a bad Buró de Crédito rating no longer reduces the amount you can get from a standard Infonavit loan.
Infonavit says it again in a clarification reported on October 8, 2026: if you authorize the credit check, you get 100% of your calculated maximum, whatever your rating. The question keeps coming back because many brokers and older websites still tell people to "fix their Buró" first.
The old system really did work differently. Infonavit used your credit history to decide how much of your calculated amount to release: weaker profiles could get roughly 80% or 90%, stronger ones 100%. So that old advice was right at the time. It just isn't anymore.
One catch: "100%" means 100% of the amount Infonavit calculates for you. It does not mean everyone can borrow the maximum advertised Infonavit mortgage.
| Situation | Under the older system | Current treatment | Effect on pure Infonavit financing |
|---|---|---|---|
| Strong credit record | Could receive full calculated amount | Full calculated amount remains possible | Little change |
| Weaker credit record | Could reduce available percentage | Rating itself no longer reduces it | Much easier |
| Credit-bureau consultation | Influenced financing | Still requested | Check remains |
| Serious credit-file problem | Could hurt qualification | Can still trigger review | Still relevant |
Why does Infonavit still check the Buró de Crédito?
Infonavit still checks the Buró de Crédito, but only to catch a few serious problems, not to grade you.
You still have to authorize the consultation. Infonavit then looks for three things: fraud records, a person wrongly registered as deceased, and extreme over-indebtedness. If one of those shows up, you have to contact the credit bureau and fix or update your record before the application moves on.
Also, being "in the Buró" does not mean you have bad credit. CONDUSEF keeps repeating it: the bureau records all borrowing, good payments included. Anyone with a credit card or a car loan has a file there.
What matters now is whether your report has a serious unresolved problem. A mediocre score on its own carries little weight.
Can bad credit still stop an Infonavit home purchase?
Ordinary bad credit should no longer stop a standard Infonavit home purchase on its own, although extreme debt or serious errors in the credit file can still cause problems.
Old late payments and a low score are one thing. The three red flags (fraud, a death record, "sobreendeudamiento extremo") are another.
A worker who missed several credit-card payments a few years ago may still have an unattractive Buró history, yet that history should no longer automatically shrink the Infonavit amount. Someone carrying debts so heavy that another mortgage would clearly stretch repayment capacity can face a different outcome.
This doesn't mean Infonavit stopped caring about risk. Its audited accounts showed more than MXN 184 billion in credit-risk reserves at the end of 2025. The risk is now judged mainly through your income and repayment capacity, not your Buró score.
| Credit situation | What Infonavit currently says | Likely effect |
|---|---|---|
| Low credit score | Rating does not reduce calculated maximum | Usually limited |
| Old late payments | No automatic score-based haircut | Usually limited |
| Little credit history | No requirement for a high score | Usually limited |
| Extreme over-indebtedness | Specifically reviewed | Can delay or restrict application |
| Fraud or identity anomaly | Must be clarified | Can block normal processing |
| Incorrect death record | Must be corrected | Can block normal processing |
 Buying in Mexico as a Foreigner
If credit scores matter less, what actually decides how much Infonavit will lend?
Your income and repayment capacity decide how much Infonavit lends, far more than your Buró score.
In 2026, Infonavit advertises loans of up to about MXN 2.94 million (about $158,000), but adds right away that the real amount depends on your capacidad de pago. The figure in Mi Cuenta Infonavit is the one to look at, not the headline maximum.
Income is only part of that calculation. Age matters because Infonavit allows repayment periods of up to 30 years, subject to age limits. The current rules generally require age plus the selected mortgage term to stay within 70 years for men and 75 years for women.
Housing savings matter too. The balance accumulated in the Subcuenta de Vivienda comes from employer contributions and can add meaningful resources to a purchase.
Employment history also feeds into Infonavit's own qualification system. If a worker leaves formal employment and later returns, for example, Infonavit says the points linked to age, salary and existing Housing Subaccount savings are preserved, while continuous contribution periods are affected.
So two people with the same Buró score can get very different offers. One may simply earn more, have more housing savings and more years left to repay.
| Factor | How much it matters now | Why |
|---|---|---|
| Buró rating alone | Low for pure Infonavit financing | Score no longer cuts the calculated amount |
| Monthly income | High | Shapes repayment capacity |
| Age and mortgage term | High for some borrowers | Limits time available to repay |
| Housing Subaccount savings | High | Adds money to the purchase |
| Formal employment history | High | Feeds Infonavit qualification |
| Extreme existing debt | Potentially high | Can trigger additional review |
Do Infonavit points matter more than your credit score?
Yes. Infonavit's own precalification tells you much more than your Buró score.
Mi Cuenta Infonavit still sends you to the "precalificación y puntos" section to see if you qualify and for how much. The familiar threshold is 1,080 points. These are Infonavit points, not Buró points: they come from your salary, age, Housing Subaccount savings and continuous contributions.
The two "scores" answer different questions. The Buró shows how you handled other credit. Infonavit points show whether you fit its own lending model and how much it can lend you.
So 1,080 points is no longer the rule for everyone, but it hasn't disappeared either. The next section explains who falls where.
 70+pages
Did Infonavit really drop from 1,080 points to 100?
Only for part of the market. In October 2026, the 100-point T100 model covers low-cost homes, mostly under Vivienda para el Bienestar, while the 1,080-point precalification still applies to bigger loans.
The government presented T100 as a major simplification of the old origination model. When the reform was introduced, Infonavit director Octavio Romero contrasted the previous 1,080-point structure with a much simpler 100-point approach, particularly for workers targeted by Vivienda para el Bienestar.
The shift went beyond changing a number on a screen. The government said requirements that could penalize workers for circumstances outside their control, including some employer-related factors, were being removed or reduced.
Infonavit wants to take T100 further. Its 2026 Strategic and Financial Plan describes a second phase that recognizes incomes above ten and up to 15 times the minimum wage, which could support loans of about MXN 4.1 million (about $220,000) for some workers who would otherwise have needed Cofinavit or a bank.
In practice, two systems now run side by side. Press reports from July 2026 describe T100 for homes of up to about MXN 600,000 (about $32,000), with buyers earning roughly MXN 8,364 to 16,728 a month, and the 1,080-point precalification still in use for homes above about MXN 800,000. Women get a 20-point bonus, and Mexico City was not yet part of that stage. Infonavit itself has not published a clear list of which products run under T100.
The official pages don't help: one Vivienda para el Bienestar FAQ still mentions 1,080 points. Don't guess from a checklist. Your precalification in Mi Cuenta Infonavit shows which track you are on.
Is Vivienda para el Bienestar easier to qualify for than a normal Infonavit home?
Yes, by design. It targets lower-income Infonavit workers, and the entry rules have nothing to do with your credit score.
The program's site asks for income between one and two minimum wages, at least six months in your job and no active Infonavit mortgage. Infonavit adds that you must not already own a home, and says the old 1,080-point requirement was removed for this program. Homes are about 60 m² with two bedrooms.
The program targets 1.8 million new homes by 2030, of which 1.2 million through Infonavit, the rest through Conavi and Fovissste. In September 2026, 88% of Infonavit's new-home buyers in the program earned between 1 and 1.5 minimum wages.
Is Vivienda para el Bienestar actually handing over homes yet?
Slowly. In September 2026, the government reported 667,000 homes contracted (37% of the 1.8 million goal) and 277,000 under construction, but only 89,000 assigned to families.
Infonavit's own share was 37,400 new homes placed with workers, in 124 developments across 29 states. That's up from about 23,300 in mid-June, so deliveries are speeding up, but the gap between "contracted" and "handed over" is still wide.
What to do: assignment depends on which units are available, so ask which development you'd be offered, where it is and when it will be finished. A cheap home far from work, or one that won't be ready for two years, may not be a deal. If your income is above two minimum wages, this program isn't for you anyway; look at a standard Infonavit loan.
 70+pages
This is just a preview page. Prices and rents move fast: your guide is refreshed every month, and you always get the latest version.
Does having other debt still reduce your chances with Infonavit?
Normal debt won't sink an Infonavit application, but heavy debt still can.
Infonavit explicitly keeps "extreme over-indebtedness" on its list of red flags. A credit-card balance is not that. The problem starts when what you already pay each month leaves little room for a mortgage payment, because the loan amount is set by your repayment capacity.
Standard Infonavit loans carry fixed rates from 3.69% to 10.45%, depending on your salary. Compare that with the 11.31% banks quote on average (Banxico, August 2026): Infonavit is still the cheapest money for most formal workers, so it's worth paying down expensive debt before you apply rather than going to a bank.
What if you barely have any credit history?
That's much less of a problem with Infonavit than with a bank.
A bank judges you on your past borrowing. Infonavit already sees your salary, your Housing Subaccount savings and how long you have contributed, through the social-security system. It doesn't need years of credit-card history to assess you.
This matters for younger workers: 75 of every 100 Vivienda para el Bienestar credits go to people under 39. You still authorize the Buró check, but a thin file is not a negative one.
Can a foreigner get an Infonavit loan?
Only if you work formally in Mexico. Infonavit is funded by employer contributions, so it serves workers registered with IMSS whose employer pays into their Housing Subaccount, whatever their nationality.
A foreign resident with a Mexican employer, a social-security number (NSS) and enough contribution history can check their precalification in Mi Cuenta Infonavit like anyone else. An investor living abroad, or a retiree on a residence visa without a Mexican payroll, has no Infonavit account and cannot use it.
For them, the options are cash, developer payment plans or a Mexican bank. Banks quoted 11.31% on average in August 2026 and granted 9.99% on average in June 2026, and they usually want legal residency, local income history and a large down payment. There, your credit file matters fully.
Does good credit still matter with Cofinavit?
Yes. Good credit can become important again with Cofinavit because a private financial institution has to approve part of the home loan.
Cofinavit combines money from Infonavit with financing from a bank or another participating financial institution. The second lender applies its own underwriting standards.
Current Infonavit documentation makes that separation concrete: Cofinavit applications require a credit-authorization letter from the financial institution. The bank therefore has an independent say in whether the transaction works.
Say Infonavit will lend you MXN 1.3 million, and you still need MXN 1 million more to buy a MXN 2.3 million home after your savings. Infonavit's soft line on your Buró only covers the first part. The bank can still turn down the other MXN 1 million (about $53,800) or charge you more.
This is the big exception. If you rely only on Infonavit, your score barely matters. If you need a bank to close the gap, it matters a lot.
| Financing route | Main lender | How much does conventional credit quality matter? | Why |
|---|---|---|---|
| Standard Infonavit | Infonavit | Much less than before | Buró rating no longer cuts calculated maximum |
| Vivienda para el Bienestar through Infonavit | Infonavit | Strongly de-emphasized | Program targets lower-income access |
| Cofinavit | Infonavit + financial institution | Can matter a lot | Bank must approve its portion |
| Apoyo Infonavit | Bank or financial institution | Can matter a lot | Mortgage itself comes from private lender |
 70+pages
Is good credit still important with Apoyo Infonavit?
Yes. With Apoyo Infonavit, the bank lends the money, so a poor credit record can still block you.
Apoyo Infonavit uses the worker's relationship with Infonavit to support a mortgage granted by a financial institution. The Housing Subaccount can serve as a form of backing, while subsequent employer contributions can help amortize the bank loan.
Apoyo Infonavit doesn't require any Infonavit points. That sounds easy, until you remember the bank decides whether to lend.
So with a weak Buró record, a standard Infonavit loan is now often easier to get than Apoyo Infonavit, even though Apoyo needs no points. Which product you use matters as much as Infonavit's rules.
Should you fix your credit before applying for an Infonavit home?
Not for a pure Infonavit loan. Waiting months just to raise an ordinary low score makes little sense under the current rules.
Check Mi Cuenta Infonavit first: your precalification and the amount on offer today. If that covers the home you want, a better Buró score changes almost nothing. Your salary, savings and the price of the home matter more.
There are still situations where repairing the credit file deserves immediate attention. Errors, identity problems, fraud records and extreme over-indebtedness can interfere with the application. Improving the file is also worthwhile when Cofinavit, Apoyo Infonavit or another bank mortgage will be needed.
An old unpaid debt can also hurt you elsewhere: CONDUSEF reminds consumers that the Buró keeps your payment record. Cleaning up real problems is still useful, just not before you check what Infonavit will give you.
So, do you still need good credit to buy an Infonavit home?
No. For a standard Infonavit loan, good credit is no longer needed to get the full amount Infonavit calculates for you. Infonavit confirmed it again in October 2026.
The limits have moved: income, repayment capacity, your points (100 under T100 for cheap homes, 1,080 for bigger loans), your Housing Subaccount and whether the total covers the home. Fraud, a wrong death record or extreme debt can still hold you up.
Once a bank is involved, through Cofinavit or Apoyo Infonavit, a poor record can still kill the deal.
So start with the amount in Mi Cuenta Infonavit. If it covers the home, an imperfect Buró history is unlikely to stand in your way.
Our methodology
This article answers one question: do you still need good credit to buy a home with Infonavit? We kept pure Infonavit loans separate from products where a bank lends part of the money (Cofinavit, Apoyo Infonavit), because the answer is different.
The rules come first from Infonavit and the federal government: Infonavit's guidance on the Buró de Crédito, its loan pages and rates (3.69% to 10.45% in 2026), its 2026 Strategic and Financial Plan and audited accounts, the Vivienda para el Bienestar requirements and FAQ, and SEDATU and Presidency briefings. Infonavit's October 2026 clarification on the Buró was taken from press reporting of it.
The split between the 100-point T100 model and the 1,080-point precalification, and the price bands of about MXN 600,000 and MXN 800,000, come from July 2026 press reports. Infonavit has not published a full list of which products run under T100, so we treat these bands as indicative. Program progress figures (667,000 homes contracted, 277,000 under construction, 89,000 assigned) come from the September 14, 2026 government briefing.
Bank rates come from Banco de México (11.31% average quoted rate, August 2026) and the Mexican Banking Association (9.99% average granted rate, June 2026).
We checked these figures in October 2026. Conversions use about 18.6 pesos per US dollar and 20.9 pesos per euro.
Limits: the amount any worker can borrow depends on their own Infonavit file, and Infonavit's public pages are not always consistent with each other. Your precalification in Mi Cuenta Infonavit is the only figure that applies to you.
Key sources used for this analysis include: Infonavit's guidance for derechohabientes, Infonavit's Plan Estratégico y Financiero 2026, the Vivienda para el Bienestar requirements, the Vivienda para el Bienestar FAQ, the June 2026 Presidency briefing on Infonavit, SEDATU on the Infonavit reform, CONDUSEF on the Buró de Crédito, UnoTV on Infonavit's October 2026 Buró clarification, El Imparcial on T100 and the 1,080-point scheme, Por Esto! on the September 2026 program update, Por Esto! on Infonavit's July 2026 update, UnoTV on the June 2026 Infonavit figures, Banco de México's interest-rate series, Crónica on ABM mortgage rates, and Infonavit Fácil on the former Buró-based system.