Summary
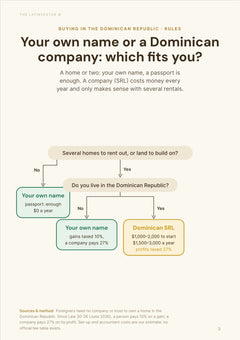
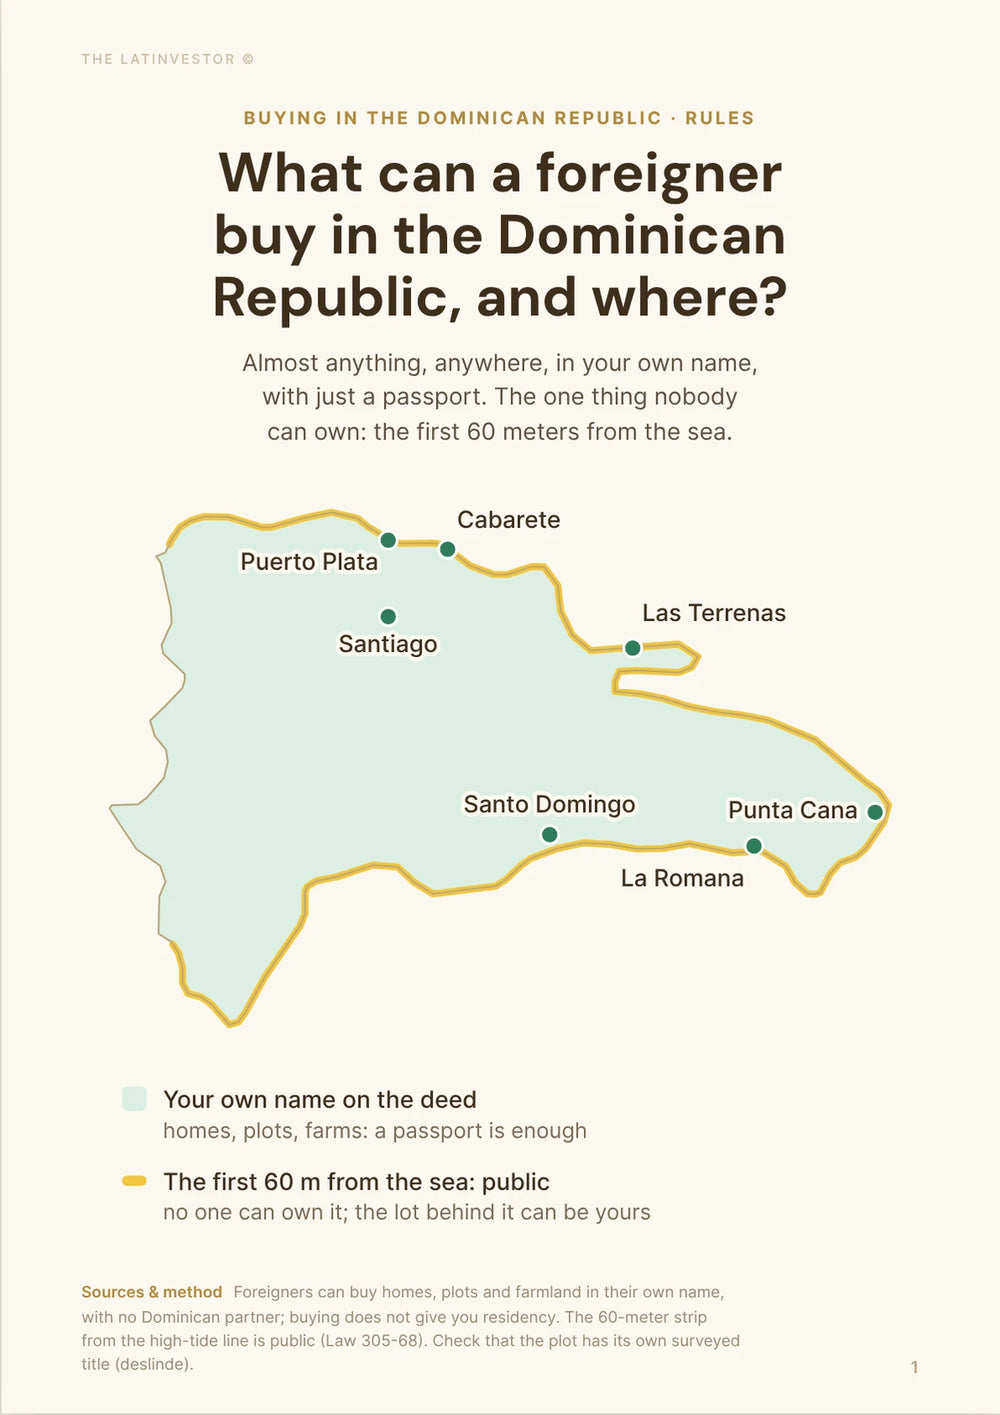
Yes: in 2026 a foreigner can buy a condo, house, villa or land in the Dominican Republic in their own name, with no residency, no local partner and no quota, and gets the same title as a Dominican.
The only real protection is the registered title. Ask for the Certificado de Título and a certification from the Registro de Títulos (about RD$1,000, or $16) before you pay anything big.
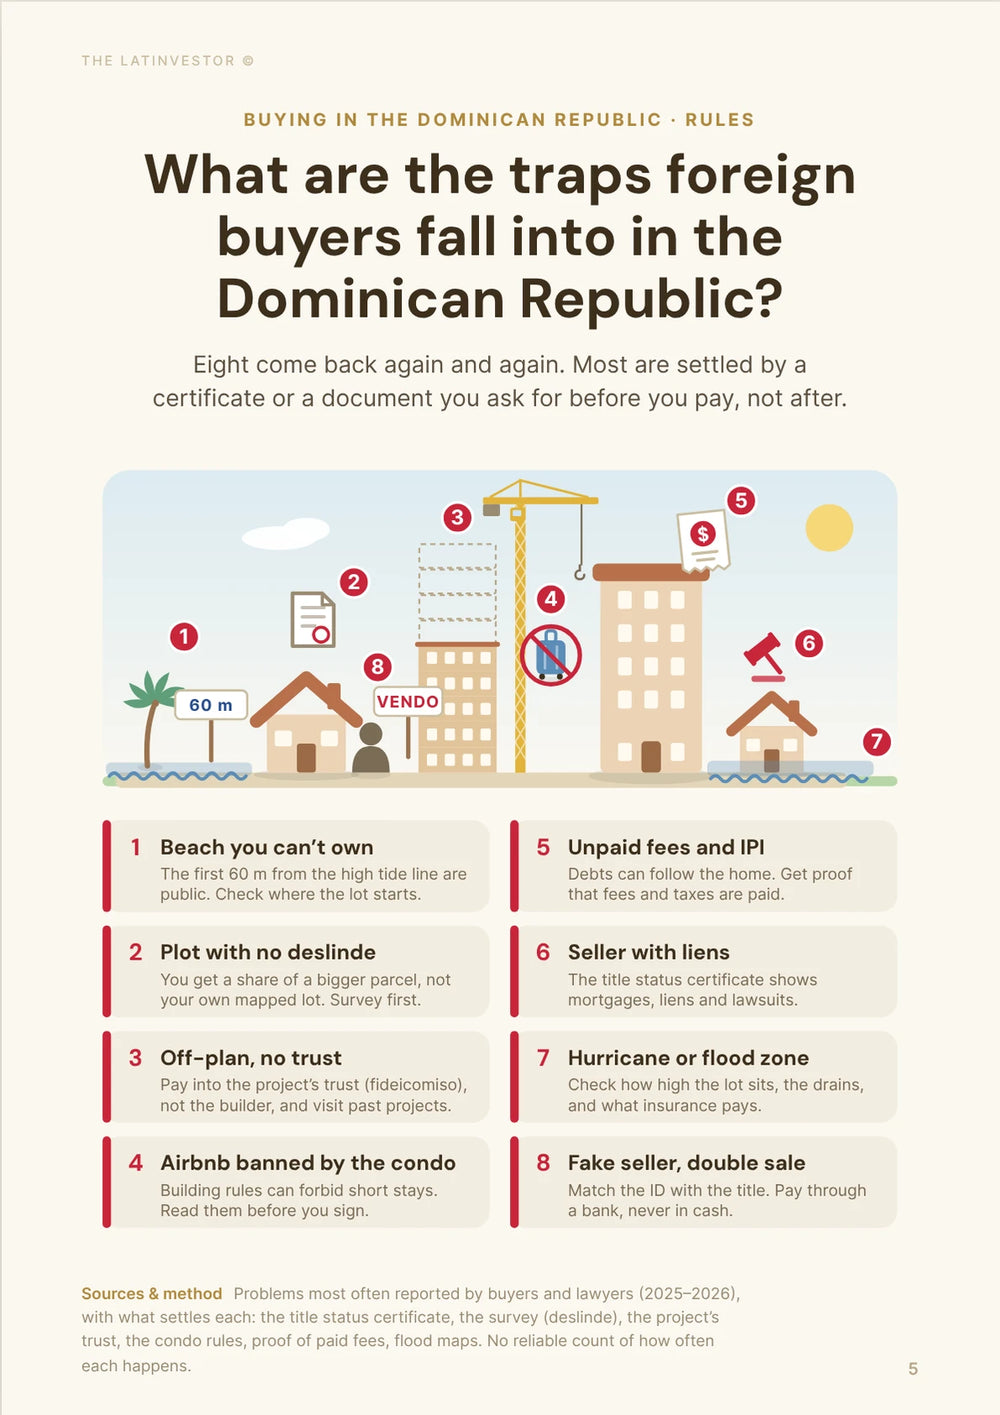
The 60 m strip from the high-tide line is public, and condo bylaws (Law 5038) can ban short stays. Read the reglamento before you buy to rent.
The classic mistake is treating a reservation, a promise of sale or possession as ownership. If the land has no individual survey (deslinde), budget RD$18,000 (about $295) to RD$60,000 (about $975) and 30 to 90 days to fix it.
You don't need a visa to buy. Buying doesn't give you residency either: investor residency needs a certified investment of at least $200,000, retiree residency a $1,500 monthly pension.
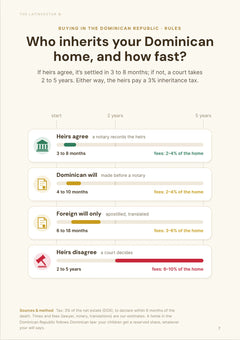
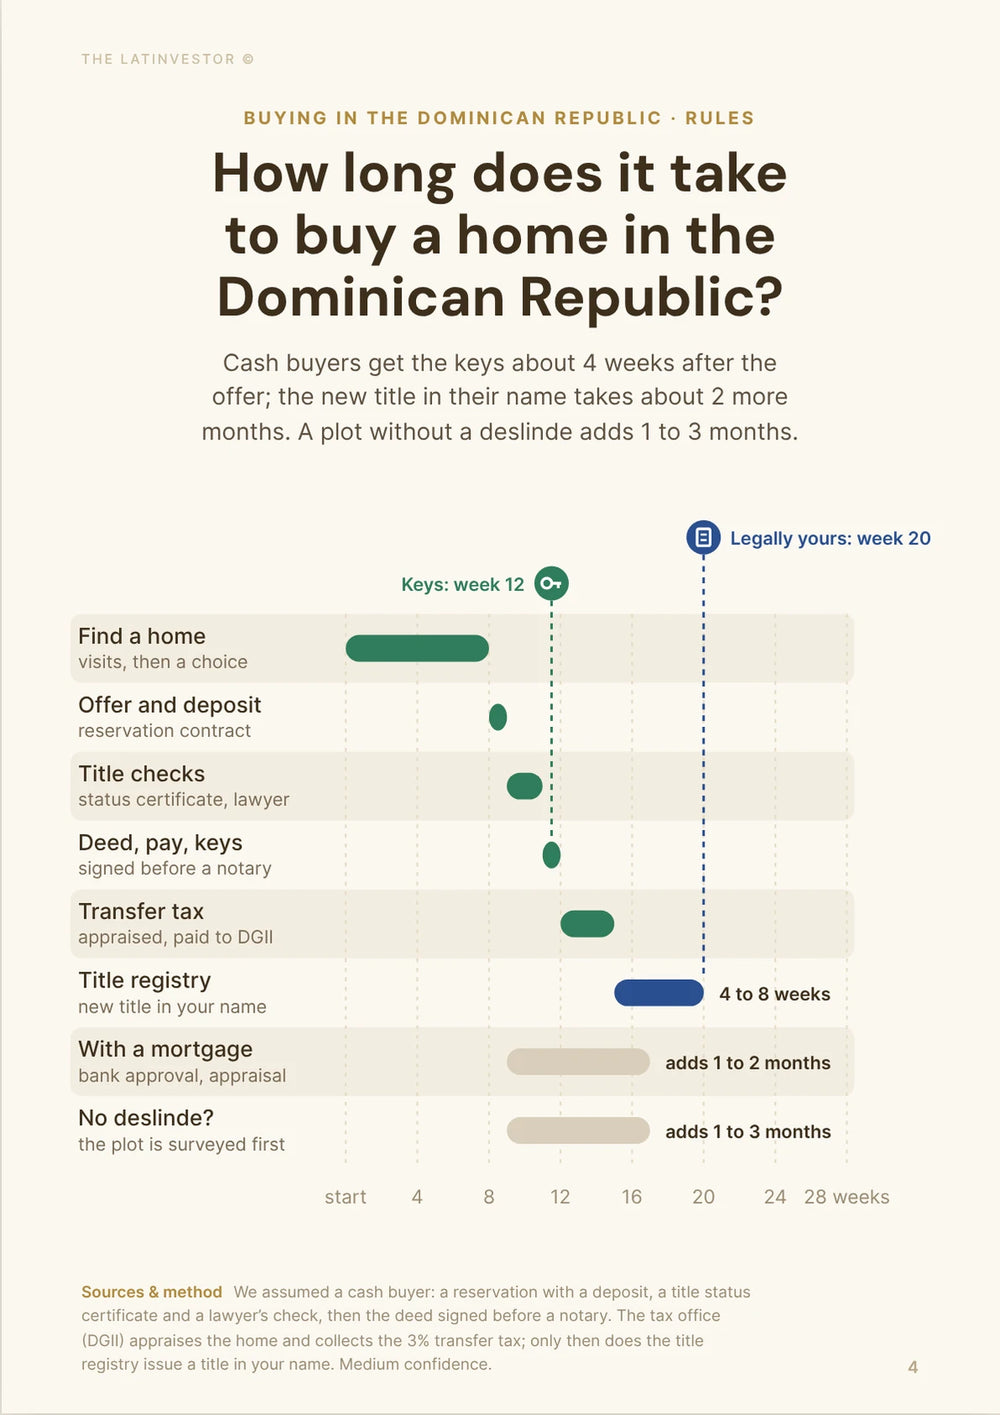
Expect roughly 45 to 90 days for a normal resale to reach a new title. A notary is part of every deal; a lawyer is optional by law but you should hire one (usually 1% to 1.5%).
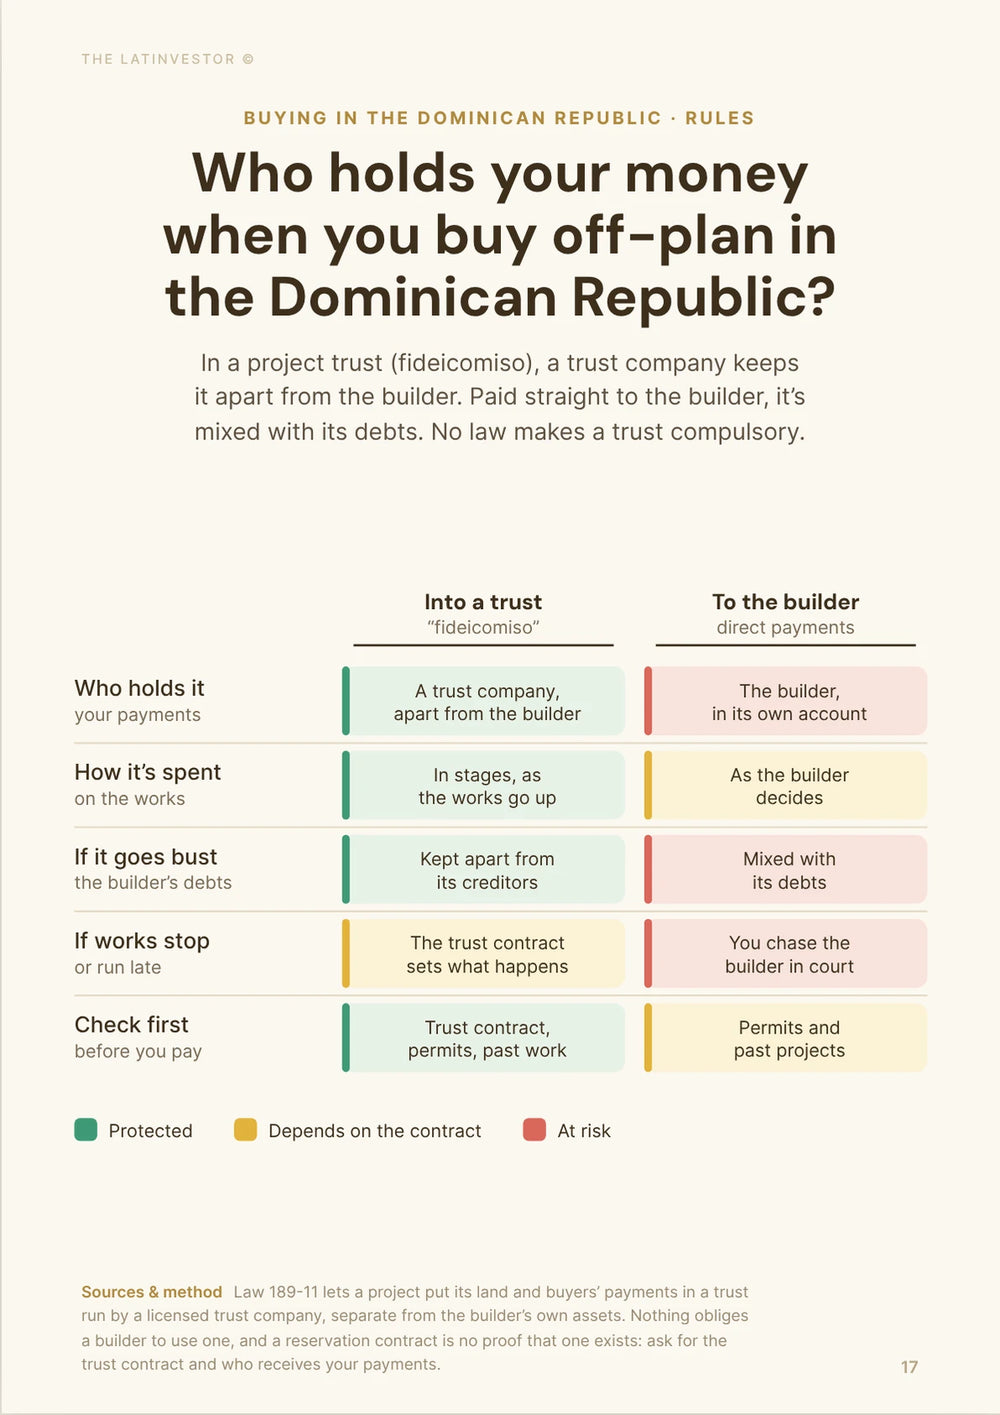
Off-plan has no general legal escrow. A fideicomiso (Law 189-11) helps, but it doesn't guarantee the building gets finished.
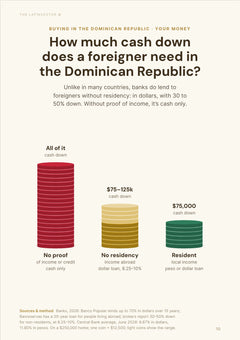
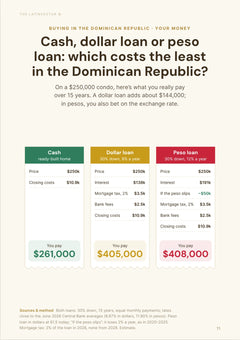
Banks lend to some foreigners, usually 50% to 70% of the price over 10 to 15 years. The BCRD average housing-loan rate was 8.87% in dollars and 11.90% in pesos in June 2026.
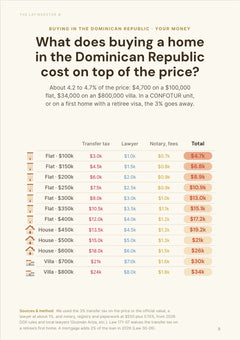
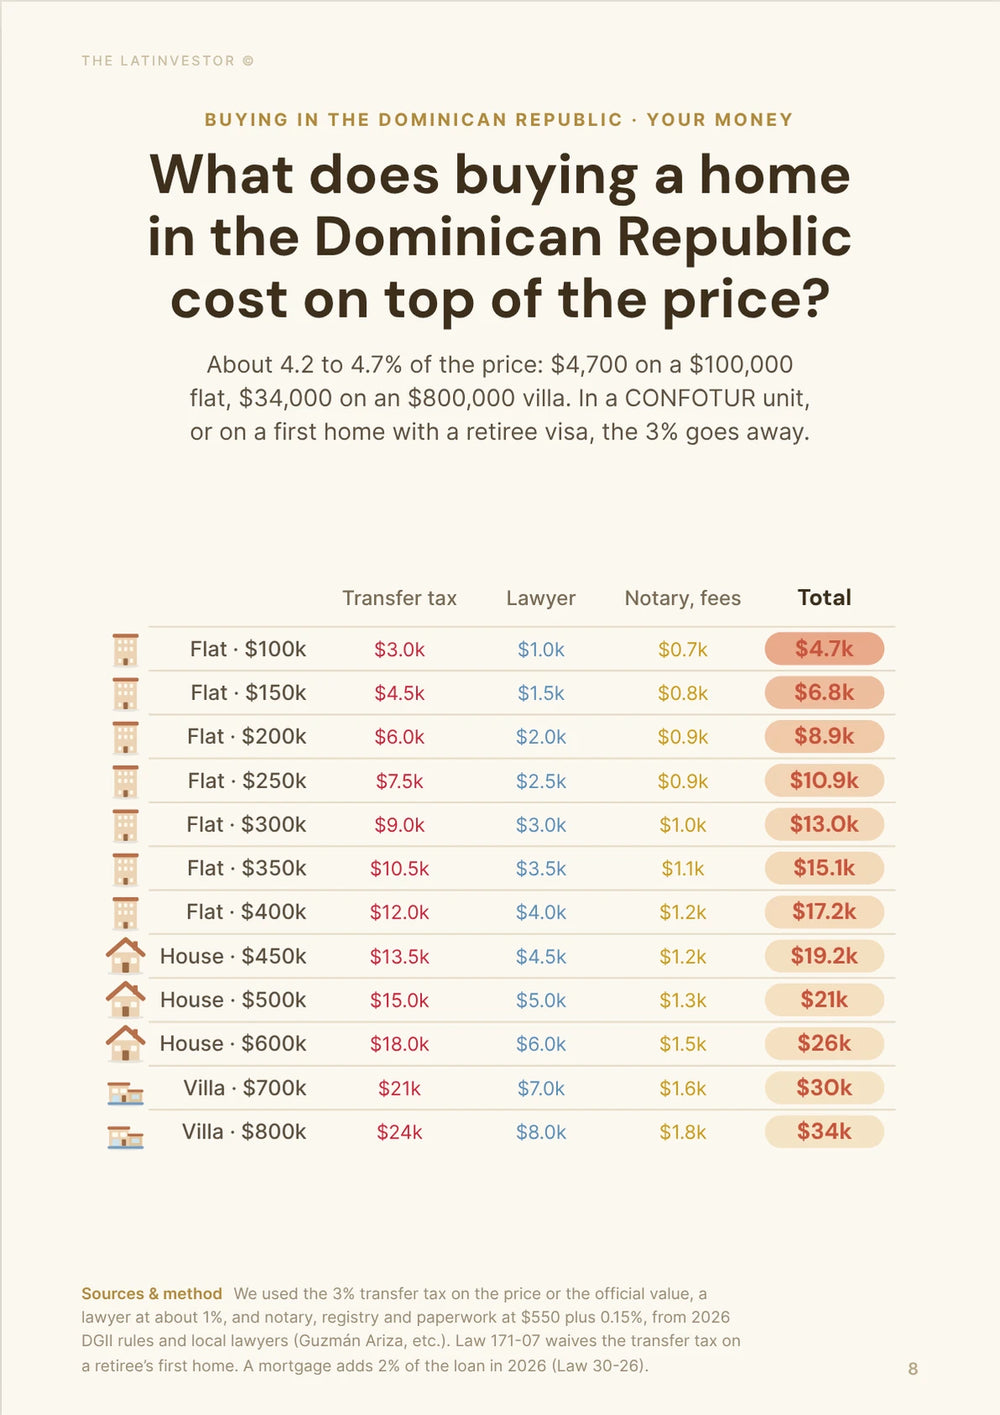
Budget 4.5% to 6.5% of the price for closing costs, or about 1.5% to 3.5% on a first purchase in a valid Confotur project, which skips the 3% transfer tax.
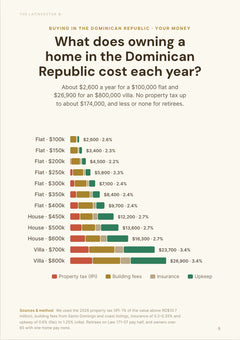
Annual IPI property tax is 0 below RD$10,695,494 of combined appraised value (about $174,000), then 1% of the amount above it.
Law 30-26 (June 2026) cut the tax on an individual's resale gain to a flat 10%, raised rent withholding to 15% and puts mortgage registration tax at 2% in 2026, 1% in 2027 and 0 from 2028.
Non-residents should budget for Dominican income tax on rental profit (the general rate for non-residents is 27%). Home insurance costs roughly 0.25% to 0.70% of the building value a year.
Bottom line: buying as a foreigner is easy; buying safely means a clean deslinde title, a lawyer who pulls the registry certification, a checked Confotur resolution and an off-plan payment plan tied to construction stages.


Property types, land and the few limits on what a foreigner can own
What property types can foreigners legally buy in the Dominican Republic right now?
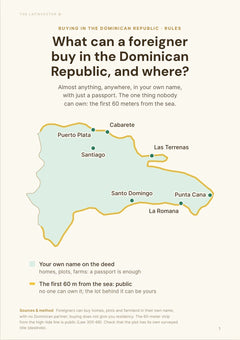
Foreigners can buy every main type of residential property in the Dominican Republic: condos, apartments, villas, detached houses, townhouses, serviced residences and residential land.
The condition that matters is the title: it must be clean, transferable and registered at the Registro de Títulos. You get exactly the same title as a Dominican buyer.
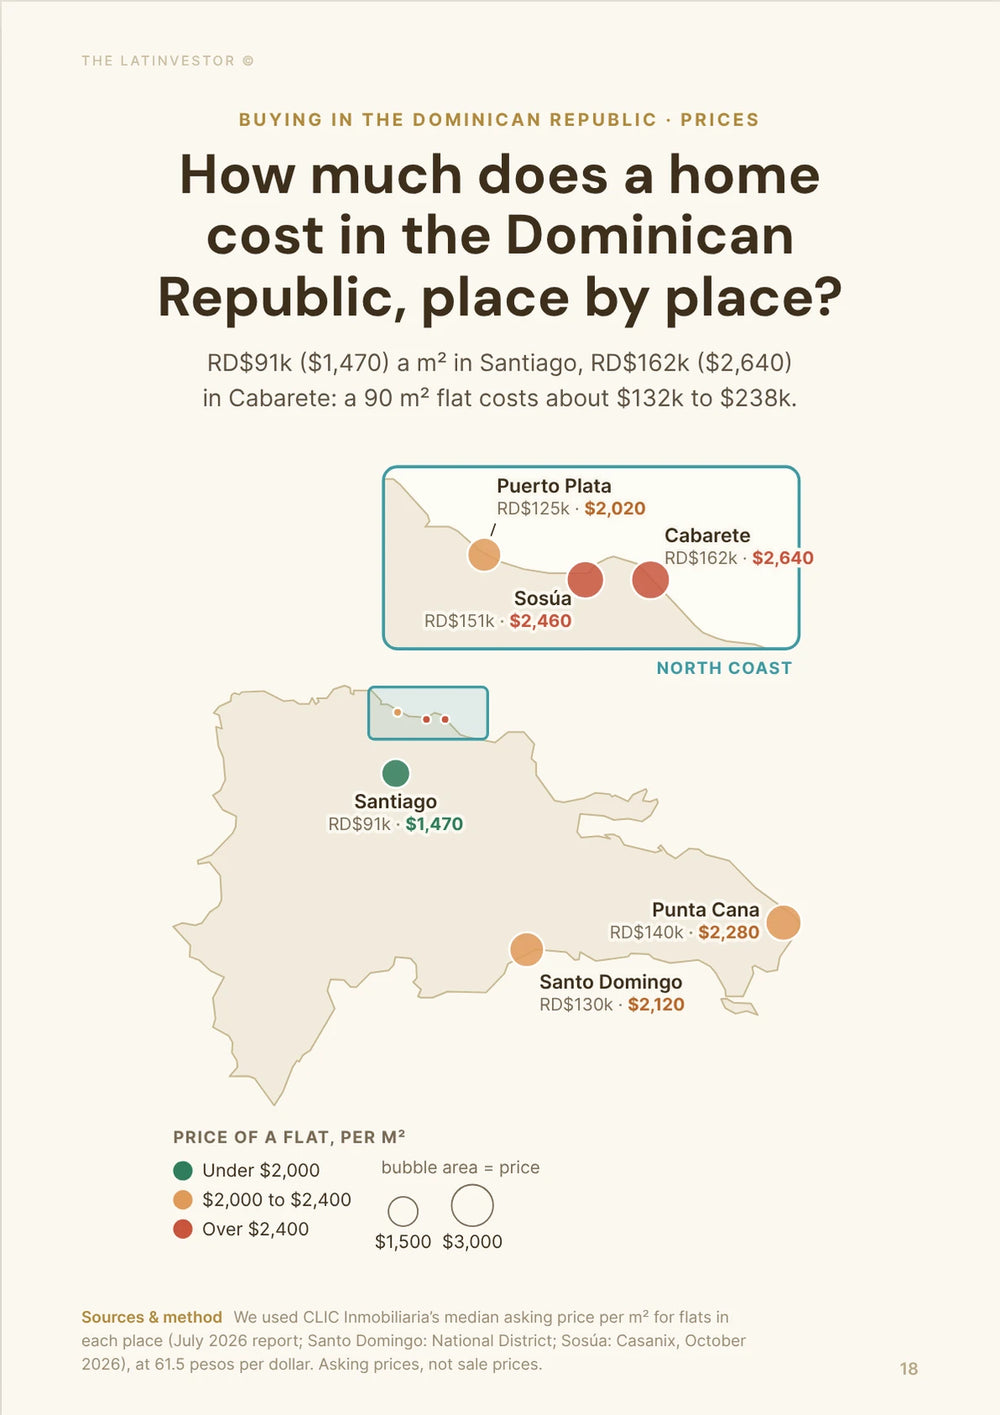
This matters most where foreigners buy the most, like Punta Cana, Bávaro, Cap Cana, Las Terrenas, Sosúa, Cabarete, Puerto Plata, La Romana, Santo Domingo and Santiago, because pre-construction projects and resort communities are common there.
In a condo, you own your unit plus a share of the common areas. But the building's bylaws can still limit rentals, pets, renovations and commercial use.
Can I own land in my own name in the Dominican Republic right now?
Yes. A foreign individual can own land in their own name in the Dominican Republic, as long as the ownership is registered at the Registro de Títulos.
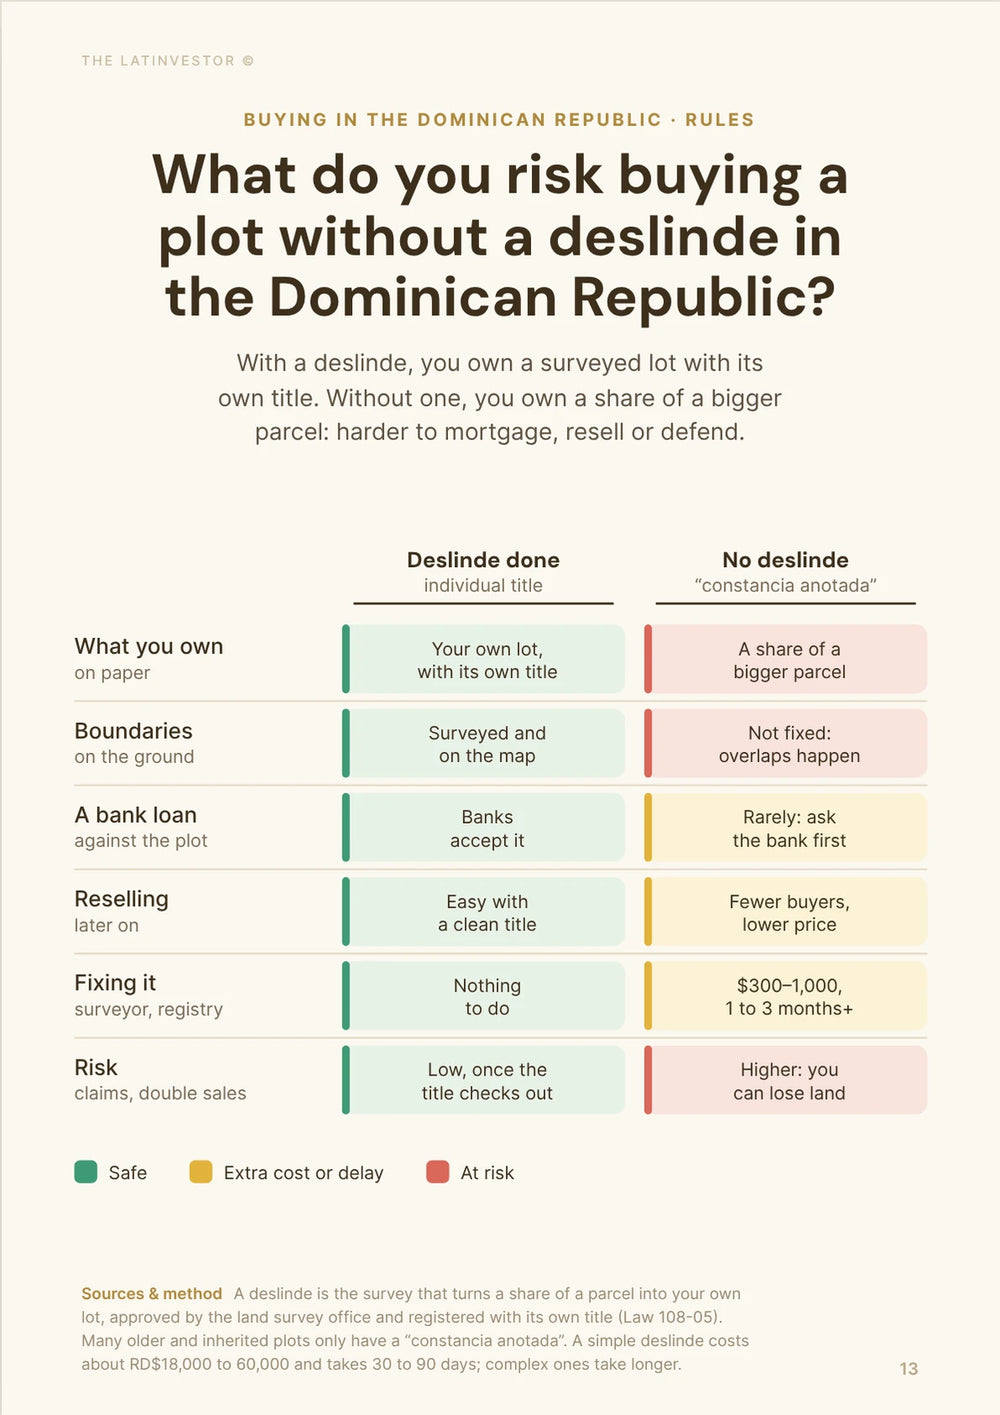
That includes the land under a villa or a house. What you need to check is that the land has its own surveyed title (a deslinde) and no old boundary problems. Avoid lots held only with a "constancia anotada", a share of a bigger parcel without defined limits.
If a deslinde is still needed, a July 2026 broker guide puts it at about RD$18,000 (about $295) to RD$60,000 (about $975) for the surveyor and process, and 30 to 90 days for a simple case.
Be extra careful outside dense city areas: a beach lot, hillside plot or rural parcel can look simple on site and still have title, survey or access problems.
Deslinde cost and time come from 1122 Real Estate's 2026 closing-cost guide.
In 2026, what other key foreign-ownership rules or limits should I know in the Dominican Republic?
In 2026, the extra limits in the Dominican Republic don't come from your nationality. They come from project rules, condo bylaws, the quality of the land title, tax steps and tourism-incentive (Confotur) status.
There is no foreign condo quota like in Thailand, and no cap on how many units a foreigner can own.
The beach rule surprises people: the 60 m strip measured from the high-tide line is public land (Law 305-68). A beachfront owner can't fence it off or build on it.
The sale must be recorded in the Dominican title system, and DGII has to collect the transfer tax before the title changes hands. There is no 2026 ban that limits normal residential buying by foreigners, but if a project claims Confotur tax benefits, check its resolution on MITUR's Confotur search before you sign.
We also used the Ministry of Environment's page on the 60-meter strip and MITUR's Confotur project search.
What's the biggest ownership mistake foreigners make in the Dominican Republic right now?
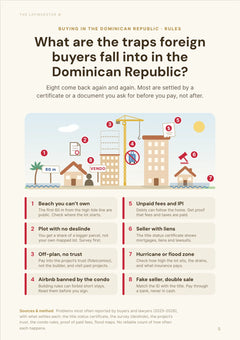
The biggest mistake is treating a reservation contract, a promise of sale, a developer's promise or simple possession as if it were registered ownership.
That can leave you with a delayed transfer, a disputed title, a resale you can't close, or a property no bank will finance later.
Other classic problems: weak checks on who the seller really is, old family titles, unclear condo bylaws, unpaid HOA fees, unpaid taxes, informal boundaries and pre-construction projects with missing paperwork.
Which visa or residency status changes what I can do in the Dominican Republic?
Do I need a specific visa to buy property in the Dominican Republic right now?
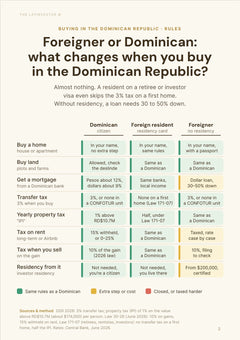
No. You don't need any visa or residency to buy property in the Dominican Republic in 2026. You can buy while visiting as a tourist.
What slows non-resident buyers down is compliance: the bank, the notary and the developer will check where your money comes from, and DGII must identify you for the transfer tax.
Most foreign buyers close with their passport. If you later rent the property out, you'll need to be registered with DGII to declare that income.
A typical file holds your passport, proof of address, proof of funds, marriage documents if relevant, and a power of attorney if you sign from abroad.
Does buying property help me get residency and citizenship in the Dominican Republic in 2026?
Only if the purchase fits the investor-residence route. Buying a property never gives you residency or citizenship by itself.
The investor route needs a certified investment of at least $200,000 (about RD$12.3 million), and a property can count. A cheaper condo doesn't qualify.
Many buyers use other routes instead: pensionado residency needs a pension of at least $1,500 a month (plus $250 per dependent) and rentista residency a stable income of $2,000 a month. The government advertises 45 working days to process a pensionado file, but gathering documents takes longer.
Citizenship is a separate naturalization process later on, with its own rules, timing and documents.
Income thresholds come from the DGM pages for pensionado and rentista residency.
Can I legally rent out property on my visa in the Dominican Republic right now?
Yes, in most cases. Your visa status doesn't stop you from renting out a property you own, and you don't need to live in the country: many foreign owners use local managers in Punta Cana, Bávaro, Las Terrenas, Cabarete, Sosúa and Santo Domingo.
There is still no national Airbnb license. MITUR's draft RENATUR registry, put out for consultation on 20 May 2026, would have made every short-term unit register. It was withdrawn on 20 July 2026 and sent to talks with the sector, with no new date.
What matters in practice: whether the condo bylaws allow short stays, whether you declare the rental income, and whether your manager handles guests, taxes and maintenance properly. Short-stay managers usually charge 20% to 25% of revenue.
Management fees come from Host My Spot; the RENATUR status from MITUR.
How does the buying process actually work step-by-step in the Dominican Republic?
What are the exact steps to buy property in the Dominican Republic right now?
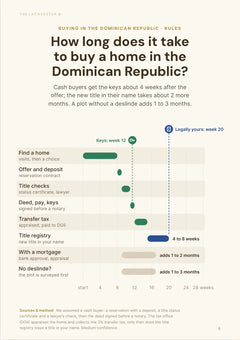
The usual order is: choose the property, reserve it, hire a lawyer, check the title, sign the promise of sale, finish due diligence, sign the notarized sale deed, pay the transfer tax, file the transfer and receive the new title.
You don't have to be there for every step. If you sign remotely, use a power of attorney prepared and legalized so the notary and the registry accept it.
The promise of sale is what binds you. But you're only safe once the new title is registered in your name.
A normal resale often takes about 45 to 90 days from accepted offer to new title. Off-plan purchases and messy titles take longer.
Is it mandatory to get a lawyer or a notary to buy a property in the Dominican Republic right now?
A notary is part of every formal purchase. A private lawyer is a different role and isn't mandatory, but a foreign buyer should always hire one.
The notary makes the key documents official. Your lawyer protects you: title, liens, the seller's authority, taxes, condo rules, contracts and closing.
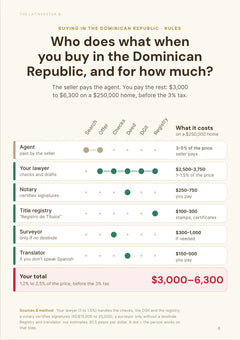
In 2026, lawyers usually charge about 1% to 1.5% of the price, and notaries about RD$15,000 to RD$45,000, or $245 to $730 (sometimes 0.10% to 0.25% of the price). Get the scope in writing: title check, lien check, seller identity, tax status, condo or HOA debts, transfer filing and review of any power of attorney.
Pick your own lawyer, not the developer's or the agent's.
Fee ranges come from Inmobiliaria Puntual and 1122 Real Estate (2026).
What checks should I run so I don't buy a problem property in the Dominican Republic?
How do I verify title and ownership history in the Dominican Republic right now?
The official place to check title and ownership history is the Registro de Títulos, part of the Registro Inmobiliario.
Ask for the Certificado de Título: it's the document that shows who legally owns a titled property.
Lawyers commonly look back at least 10 years, and further when the property went through family transfers, old subdivisions, inheritance, lawsuits or unclear surveys.
Walk away from any mismatch between the seller, the title, the cadastral description, the boundaries on site or the person actually signing.
How do I confirm there are no liens in the Dominican Republic right now?
Ask the Registro de Títulos for a certification of the property's legal status. It costs about RD$1,000 (about $16) and lists mortgages, annotations, seizures and restrictions.
The most common charge is a bank mortgage. Also check what the registry doesn't show: tax debts, condo or HOA arrears, utility bills and court cases.
Get that certification shortly before closing, not weeks earlier, and make the seller clear every debt before you sign the deed.
The certification fee comes from the Registro Inmobiliario FAQ.
How do I check zoning and permitted use in the Dominican Republic right now?
Start with the local ayuntamiento. If the property is in a resort, on the coast or near a protected area, also check with tourism and environmental authorities, and with the community's own rules.
Ask for the land-use confirmation for the parcel, plus any project approvals that show what can be built or rented.
A common trap is assuming a beautiful lot can take villas or short-term rentals before checking municipal rules, beach access, the 60 m strip, environmental limits and community bylaws.
Is it safe to buy off-plan as a foreigner in 2026?
It can be, but the law protects you less than most buyers think. There is no general legal escrow for off-plan deposits in the Dominican Republic: your protection depends on the contract and on whether the project uses a fideicomiso (Law 189-11).
A fideicomiso keeps the project's money and land separate from the developer, and a fiduciary releases payments. That's better than paying the developer directly, but it doesn't guarantee the building will be finished.
Supply is the other risk. RE/MAX counted more than 50 off-plan projects in its Punta Cana sample in 2026, and Airbnb occupancy there was only about 36% over the year to September 2026 (AirROI). On delivery you'll compete with many similar units for buyers and tenants.
What to do: tie payments to construction stages, not dates; check the building permit and the Confotur resolution yourself; get the name of the fiduciary and call it; and keep the final 30% or more for delivery. Visit finished projects by the same developer before you sign.
The payment advice is our own checklist for off-plan buyers.
Can I get a mortgage as a foreigner in the Dominican Republic, and on what terms?
Do banks lend to foreigners for homes in the Dominican Republic in 2026?
Yes, Dominican banks lend to some foreign buyers in 2026, but they pick carefully and ask for more paperwork than from locals.
Brokers report that non-residents usually put down 30% to 50%, so they borrow 50% to 70% of the price, over 10 to 15 years. Banco Popular advertises a dollar product up to 70% and 15 years, and Banreservas a product for Dominicans and residents abroad up to 20 years, but neither is guaranteed to a non-resident.
What counts most is stable, provable income and a clean source of funds, then residency status, credit history, bank references and the quality of the property's title.
Mortgage lending is growing: the outstanding stock reached RD$466.9 billion (about $7.6 billion) in July 2026, up 11.5% in a year (Superintendencia de Bancos).
We also used Tropical Assets on financing as a foreigner, Banreservas and El Dinero on the mortgage stock.
Which banks are most foreigner-friendly in the Dominican Republic in 2026?
In 2026, foreign buyers usually start with Banco Popular and Banreservas, then compare BHD, Banco BDI and Scotiabank.
They're the biggest mortgage lenders and the most used to checking income earned abroad.
Non-residents can get a loan, but expect a bigger down payment, more documents and a stricter look at the property file than a resident would face. Ask your bank which projects it already finances: an off-plan unit the bank doesn't know can be refused.
What mortgage rates are foreigners offered in the Dominican Republic in 2026?
No bank publishes a rate for non-resident foreigners. The best guide is the market: the BCRD average housing-loan rate was 8.87% for dollar loans and 11.90% for peso loans in June 2026.
Banco BDI's May 2026 reference rates were 8.9% to 9.9% for preferred dollar loans, 9.9% to 11.4% for ordinary dollar loans and 14% to 15% in pesos. Brokers quote foreigners about 8.25% to 10% in dollars. The old "6% to 7%" figures you still see online are out of date.
Most loans have a rate fixed for a short period, then reviewed by the bank. The Central Bank raised its policy rate to 5.50% in September 2026, so don't count on cheaper loans soon.
If you earn in dollars, borrow in dollars: a peso loan adds currency risk on top of a higher rate.
Rates come from Banco BDI's 21 May 2026 reference rates, the BCRD June 2026 averages reported by Tropical Assets, and the BCRD policy-rate decision.
What will taxes, fees, and ongoing costs look like in the Dominican Republic?
What are the total closing costs as a percent in the Dominican Republic in 2026?
In 2026, budget about 4.5% to 6.5% of the price for closing costs on a normal purchase in the Dominican Republic.
The biggest item is the 3% transfer tax, charged on the higher of the price and DGII's appraisal. Then come the lawyer (about 1% to 1.5%), the notary (about RD$15,000 to RD$45,000, or $245 to $730), small registry fees and, if you borrow, the 2% mortgage registration tax on the loan in 2026 (1% in 2027, nothing from 2028).
On a $250,000 (about RD$15.4 million) resale, that's roughly $11,250 to $16,250. On a first purchase in a project with a valid Confotur resolution, the 3% transfer tax goes away and total costs fall to about 1.5% to 3.5% ($3,750 to $8,750).
The agent's 3% to 5% commission is usually paid by the seller. Add RD$18,000 (about $295) to RD$60,000 (about $975) if the property still needs a deslinde.
Ranges come from 1122 Real Estate (July 2026) and Law 30-26 for the mortgage tax.
What annual property tax should I budget in the Dominican Republic in 2026?
In 2026, many homes owe no IPI at all: individuals only pay once the combined DGII-appraised value of all their Dominican property passes RD$10,695,494 (about $174,000).
Above that, the tax is 1% of the part over the threshold. A property appraised at RD$14 million pays about RD$33,000 (about $535) a year. DGII appraisals are often below the market price.
Units in a Confotur project can be exempt for up to 15 years, and owners over 65 living in their only home, and some pensionados and rentistas, can get exemptions. Properties held through a fideicomiso or a company don't get the individual threshold.
Confotur and senior exemptions come from Tropical Assets on Confotur and DGII.
How is rental income taxed for foreigners in the Dominican Republic in 2026?
Rent from a Dominican property is Dominican-source income, wherever you live. What you pay depends on who pays the rent, your expenses and whether you're a tax resident.
When a company rents from an individual, it must now withhold 15% of the rent (10% before Law 30-26). Residents then pay the normal 0% to 25% income tax scale.
As a non-resident, budget for Dominican income tax on your rental profit: the general rate for non-residents is 27%. Short-stay owners usually file through a local accountant, and 18% ITBIS may apply to tourist lodging. How that applies to an individual's Airbnb isn't settled, so check with an accountant.
The 15% withholding comes from Law 30-26.
What insurance is common and how much in the Dominican Republic in 2026?
In 2026, a rough home-insurance budget in the Dominican Republic is about 0.25% to 0.70% of the building's insured value a year. On a $300,000 home, that's about $750 to $2,100 (RD$46,100 to RD$129,000). This is our estimate: no one publishes average premiums.
Most owners carry fire and major-damage cover, then add hurricane, earthquake, flood, theft and liability when the location or the bank asks for it.
Hurricane, flood and coastal exposure move the price the most, especially for beachfront villas. The hurricane season runs from 1 June to 30 November. In a condo, the building's policy usually doesn't cover your contents or your liability as a landlord.
What does Law 30-26 change for a foreign buyer?
Law 30-26, the tax reform passed in June 2026, is in force. It didn't change the right of foreigners to buy, the 3% transfer tax or the IPI rules, but it changes what you pay when you borrow, rent and sell.
Selling: an individual now pays a flat, final 10% on the gain. Before, the gain was taxed at 27% after an inflation adjustment. On a property bought for $250,000 and sold for $300,000, that's about $5,000. Gains on your main home are exempt if you reinvest in a new main home within 6 months, and so are sales of a main home by owners over 65. Companies still pay 27%.
Borrowing and renting: the mortgage registration tax drops from 2% of the loan in 2026 to 1% in 2027 and 0 from 2028, so if you plan to borrow and can wait, waiting saves money. Withholding on rent paid by companies to individuals went from 10% to 15%.
Confotur: the law didn't repeal it, but it says you can't use two incentive regimes on the same operation. Lawyers at Pellerano & Herrera say the effect on Confotur projects is still unclear. If the tax savings are a big part of why you're buying a unit, ask your lawyer to confirm them in writing.
The resale example is our own calculation.
Related blog posts
- Can foreigners buy and own land in the Dominican Republic?
- Can Americans buy property in the Dominican Republic?
- Can you get residency in the Dominican Republic by buying property?
- What are the risks of buying property in the Dominican Republic?
- What are the property taxes and fees in the Dominican Republic?
Our methodology
This article explains what a foreigner can buy and own in the Dominican Republic in 2026, how residency and visas fit in, how a purchase works, which checks to run, how foreigners borrow, and what they pay in closing costs, yearly taxes, rental tax and insurance.
Ownership and title rules come from the Registro Inmobiliario, Law 108-05, Law 5038 on condominiums, Law 16-95 and Law 305-68. Residency thresholds come from the Dirección General de Migración. Mortgage figures come from BCRD averages (June 2026), Banco BDI's May 2026 reference rates, bank product pages and broker reports. Closing-cost ranges come from 2026 broker guides (1122 Real Estate, Inmobiliaria Puntual), off-plan supply from RE/MAX and CLIC, and Airbnb occupancy from AirROI only.
Tax rules (transfer tax, IPI, rental tax, capital gains, mortgage tax) come from DGII and the text of Law 30-26. Confotur rules come from MITUR and Law 158-01, with Pellerano & Herrera's reading of the Law 30-26 overlap. The RENATUR status comes from MITUR's July 2026 withdrawal.
We checked these figures in October 2026. Conversions use about 61.5 Dominican pesos per US dollar.
Where we had no direct figure, we estimated it and say so: the 45-to-90-day timeline, the 10-year title look-back and home-insurance premiums. Your own costs will depend on the property's title, the project, your bank profile and whether you live in the country.
Key sources used for this analysis include Registro de Títulos, Registro Inmobiliario sale-transfer procedure, Law 108-05 on Real Estate Registration, Law 16-95 on Foreign Investment, U.S. State Department Investment Climate Statement, Law 5038 on Condominiums, DGII IPI property tax page, DGII IPI guide, DGII real estate transfer brochure, DGII withholding guide, Dirección General de Migración investor residence, CONFOTUR (Ministry of Tourism), Banco Popular mortgage page, Superintendencia de Bancos, Superintendencia de Seguros, Ministry of Environment, BCRD exchange-rate reference, DGM pensionado residency, DGM rentista residency, Ministry of Environment page on the 60-meter strip, MITUR Confotur project search, Pellerano & Herrera on Confotur and Law 30-26, Law 30-26, Presidency on Law 30-26, DGII fideicomiso page, 1122 Real Estate closing costs 2026, Inmobiliaria Puntual closing costs, Tropical Assets on financing as a foreigner, Tropical Assets on Confotur, Banco BDI reference rates (May 2026), Banreservas mortgages for residents abroad, BCRD policy-rate decision, El Dinero on the mortgage stock, RE/MAX Metropolitana, CLIC Inmobiliaria H1 2026 report, AirROI Punta Cana, Host My Spot, MITUR Registro Nacional Turístico and Registro Inmobiliario FAQ.